





According to investment banking industry sources on Sept. 4, SK Innovation announced on Aug. 25 that it would absorb SKIET through a merger. The merger ratio was set at 1 to 0.1174540.
SKIET is a specialist maker of battery separators. It was spun off from SK Innovation in 2019 and went public in 2021. Its IPO price was KRW 105,000 per share, and the stock is now trading at around KRW 16,000 — a roughly sixfold decline in about five years since listing.
Because SKIET was separated through a so-called "physical division" — a spin-off structure in which the parent company retains full ownership of the new subsidiary rather than distributing shares to existing shareholders — SK Innovation's shareholders received no direct benefit from SKIET's stock market listing.
At the time of its listing, SKIET's market capitalization stood at about KRW 10.23 trillion, while SK Innovation's market capitalization was about KRW 25.9 trillion. Even factoring in SK Innovation's current roughly 52 percent stake in SKIET, the dual-listing ratio came to about 14.7 percent.
Korea's dual-listing ratio, which is higher than in global markets, has long been cited as one of the causes of the so-called "Korea discount." SK Innovation shareholders had no choice but to watch as they suffered a double blow: first the physical division, then the dual-listing discount.
Through its IPO, SKIET raised roughly KRW 900 billion. Immediately after listing, it posted net cash of KRW 205 billion and a debt ratio of 43.7 percent, placing it among what were considered high-quality companies.
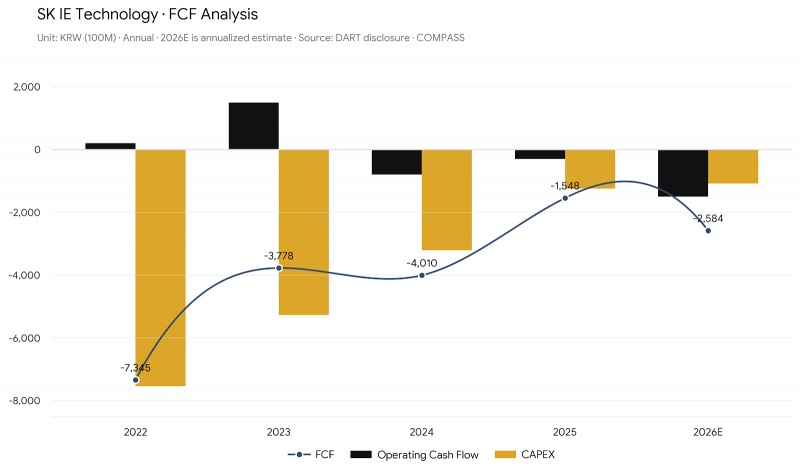
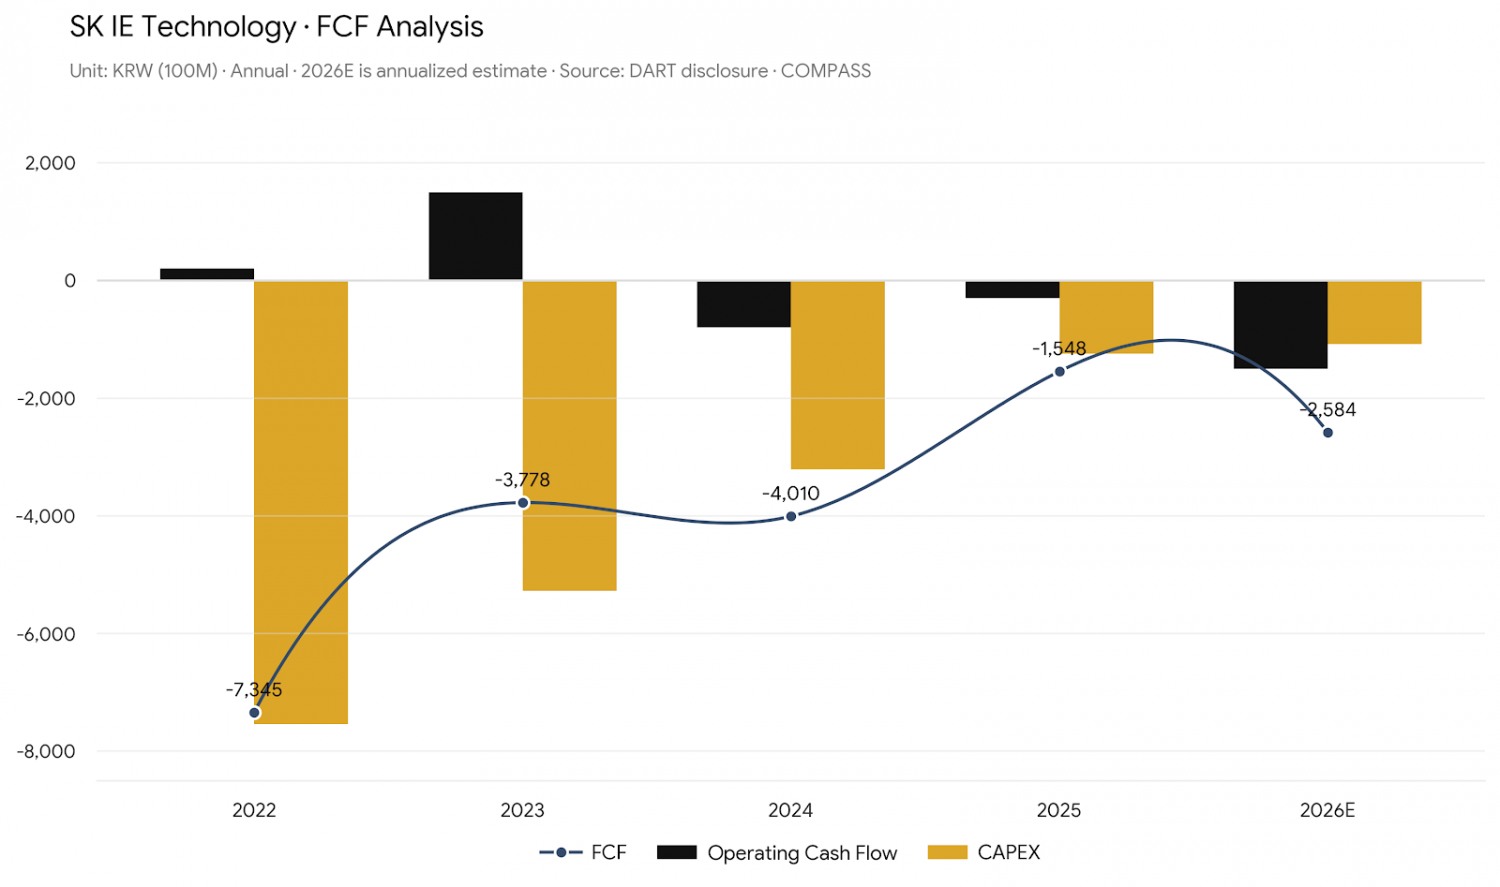
Since then, however, massive capital expenditure has coincided with a sharp deterioration in cash flow. SKIET's operating margin, which stood at 14.8 percent in 2021, plunged to -8.9 percent in 2022. Free cash flow (FCF) has remained negative ever since.
"Turned to a Millstone by the Chasm": SK's EV Trio — When Will Normalization Come?SK's Holding Subsidiaries Diverge: SK Discovery Falls Behind the PackBeyond Hynix: SK's Three-Company AI Alliance Eyes Full-Stack JackpotGS Stock Hits Record High, Yet Still Trades at Half Its Book ValueLG Electronics Transcends Manufacturing: Robotics Is Only the Tip of the Iceberg
As of the end of the first half of this year, SKIET's net loss totaled KRW 1.4095 trillion. Its net borrowings climbed to KRW 1.45 trillion — a stark reversal from its position at the time of its IPO.
Market Judgment and Capital Allocation: A Complete Missed Opportunity for Management
As a result, the fundraising and growth strategy that followed SK Innovation's physical division of SKIET have ended in complete failure. As noted above, SK Innovation's shareholders had no means of intervening in this process.In the merger, SKIET shareholders are being granted appraisal rights — the right to demand that the company buy back their shares. If the total value of exercised appraisal rights exceeds KRW 350 billion, the merger agreement can be terminated.
However, SKIET's short-term borrowings stand at KRW 1.2533 trillion, while its cash and cash equivalents amount to just KRW 386.3 billion. If the total value of appraisal rights claimed by SKIET shareholders exceeds KRW 350 billion, the merger would collapse — but SKIET could then face a liquidity crisis, given the difficulty it would have raising funds on its own.
For SKIET shareholders, given the company's questionable prospects for standalone survival and its liquidity burden, it remains unclear whether appraisal rights offer any real negotiating leverage.
By contrast, because the merger is being structured as a small-scale merger — a simplified procedure available when the shares to be issued fall below a certain threshold relative to the acquirer's total shares outstanding — SK Innovation shareholders are not granted appraisal rights at all. Having already endured the physical division and the dual-listing discount, SK Innovation's shareholders are now being forced to directly absorb the financial burdens left behind in the subsidiary.
In the end, shareholders of both SK Innovation and SKIET are being denied any real opportunity to defend their interests. The merger has become a textbook example of the chronic governance problems and shareholder disregard that persist in Korea's capital markets.
"The absorption merger of SKIET is primarily intended to head off the risk of default," said an investment banking industry source. "That direction isn't necessarily wrong, but from the spin-off to the merger, SK Innovation's shareholders have only ever been on the losing end." The source added: "At its root, this is a governance problem — but it's ironic that the merger itself will eliminate the governance penalty," referring to the higher funding costs stemming from the company's governance structure.
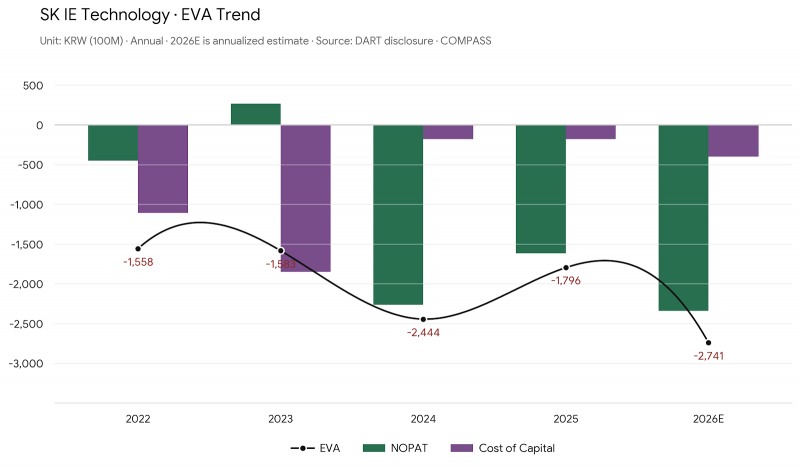
*SK IE Technology's Economic Value Added (EVA) Trend / Source: THE COMPASS Recreated using AI.
이미지 확대보기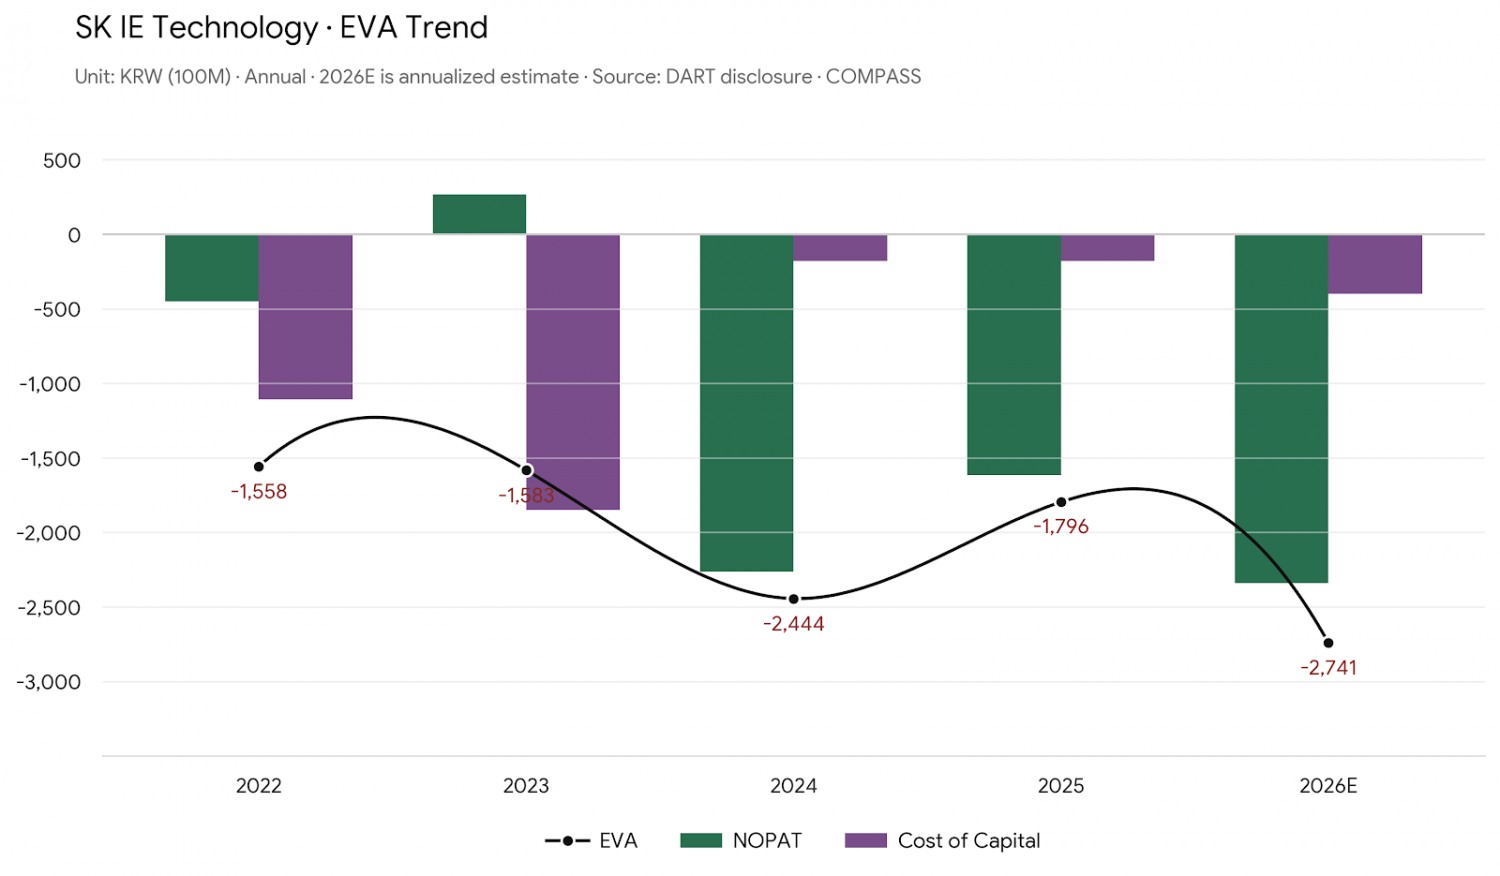
Lee Sungkyu (lsk0603@fntimes.com)





















