






While SK On has succeeded in raising funds through private placements, its financial instability continues to worsen. Adding to concerns, Chief Financial Officer Kim Kyung-hoon, a key figure behind the company’s investment strategy, is set to leave the company. In response, SK On plans to expand R&D investments and focus on securing orders in anticipation of a temporary downturn—or “chasm”—in the electric vehicle (EV) market.
According to industry sources on May 27, SK On raised approximately KRW 120 billion this year through three separate private bond issuances for operating capital. Specifically, the company issued KRW 30 billion in three-year notes with a 4.03% annual interest rate on May 13 under the lead of Shinhan Investment Corp. Earlier, on March 27, it issued another KRW 30 billion in three-year notes at 4.28%, and on March 12, it secured KRW 60 billion in two tranches (KRW 30 billion each in two- and three-year notes) at 4.08% and 4.23%, respectively.
At the beginning of the year, SK On had sought a formal credit rating and explored the public bond market alongside other SK Group affiliates. However, due to a downturn in the secondary battery sector triggered by the EV “chasm,” and declining performance, the company ultimately veered away from a public offering.
Over the past three years, SK On has posted cumulative operating losses totaling approximately KRW 2.74 trillion. In the first quarter of this year, the company narrowed its losses compared to KRW 331.5 billion in the same period last year, but still recorded a KRW 163.2 billion operating loss.
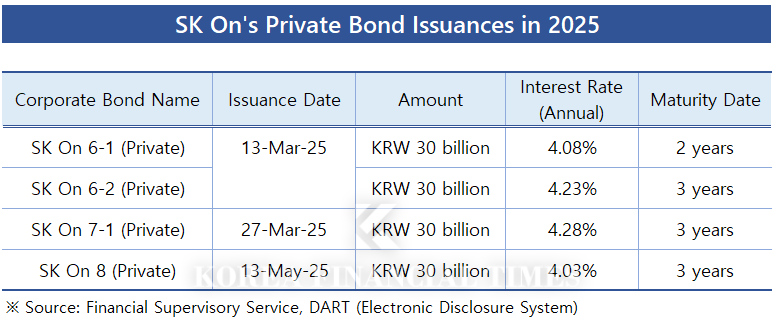
As a result, the company turned to the private bond market, which allows for quicker issuance and poses less reputational risk compared to public offerings. However, private bonds typically carry higher interest rates and shorter maturities, meaning SK On may face increasing financial strain if its business performance does not improve.
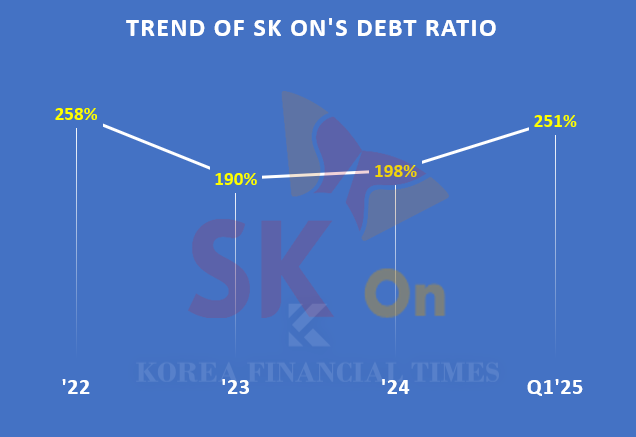
Actually, SK On’s debt ratio hit 258% in 2022, eased to 190% in 2023, but rose again to 198% in early 2024. In the first quarter of this year, the debt ratio further increased to 251%, surpassing the psychologically significant 200% threshold. Net debt, excluding cash-equivalent assets, also climbed from approximately KRW 16 trillion in 2022 to around KRW 20 trillion by the end of last year—highlighting the company’s growing reliance on borrowed capital.
SK Group Doubles Cash Generation on Semiconductor Gains... Energy Sector Increases BorrowingLG Energy Solution, Samsung SDI and SK-on Aim for 'K-Battery Comeback'LG Energy Solution, Samsung SDI, SK On Brace for Prolonged EV Battery Slump"Why SK On Pins Its Hopes on Hyundai and Kia's Performance in the U.S."
Compounding the challenge is the imminent departure of Vice President Kim Kyung-hoon, a key player in SK On’s financial strategy. A former executive at Lehman Brothers and other global investment firms, Kim helped SK On secure KRW 1.2 trillion in funding from an MBK Partners-led consortium in 2022, eventually driving investments totaling around KRW 5 trillion. He also played a critical role in SK On’s joint venture with Ford—BlueOval SK—securing a KRW 13 trillion loan from the U.S. government.
Source: SK On Business Report and others
SK On says it is committed to reversing its fortunes by investing in next-generation battery technology and ramping up order volumes. The company allocated KRW 77.6 billion to R&D in the first quarter of this year, a 10% increase compared to the same period last year. This investment is focused on securing a lead in all-solid-state battery technology.
SK On is currently developing two types of all-solid-state batteries—polymer-oxide composite-based and sulfide-based—targeting commercial production by 2028 and 2030, respectively.
CEO Lee Seok-hee stated, “The battery industry must prioritize R&D to deliver the technologies and products that customers demand,” adding, “We will not hesitate to invest in that.”
Recent increases in battery orders from the U.S. and Japan offer a positive outlook. SK On recently signed a contract with U.S. EV startup Slate Auto to supply 20 GWh of batteries from 2026 to 2031. Prior to that, the company inked a deal with Nissan to deliver 99.4 GWh of batteries from 2028 to 2033.
Additionally, its Kentucky plant, jointly built with Ford under the BlueOval SK partnership, and a Georgia-based facility under construction with Hyundai Motor Group, are both set to begin full-scale production in 2026.
Kim JaeHun (rlqm93@fntimes.com)




















