





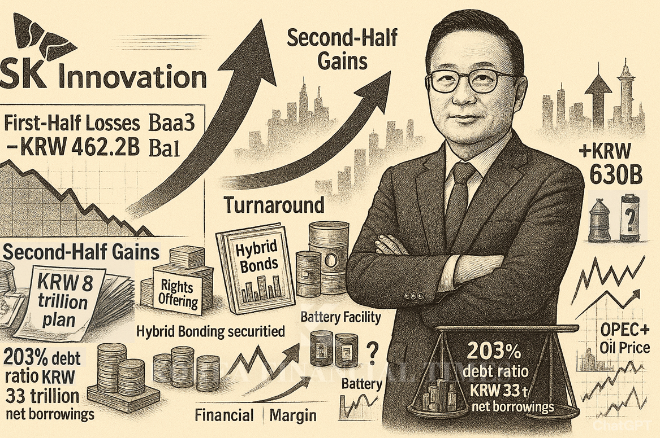
According to financial information company FnGuide's compilation on the 29th, the consensus (average estimate) for SK Innovation's second-half operating profit is KRW 368 billion. Securities firms that recently issued reports estimate this higher at KRW 600-630 billion. The refining division is particularly expected to lead the turnaround, buoyed by improved refining margins.
SK Innovation recorded an operating loss of KRW 462.2 billion in the first half of this year, turning to deficit from an operating profit of KRW 578.9 billion in the first half of last year.
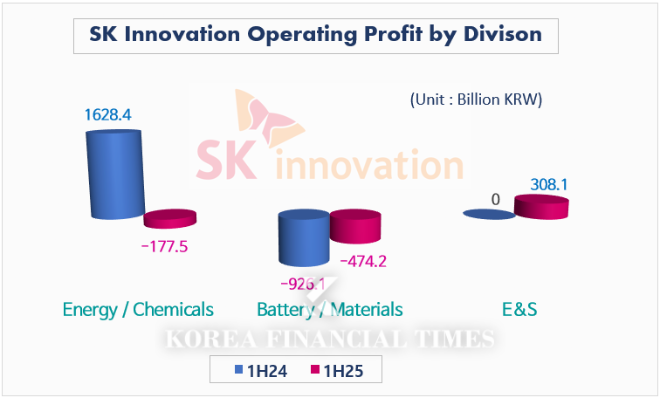
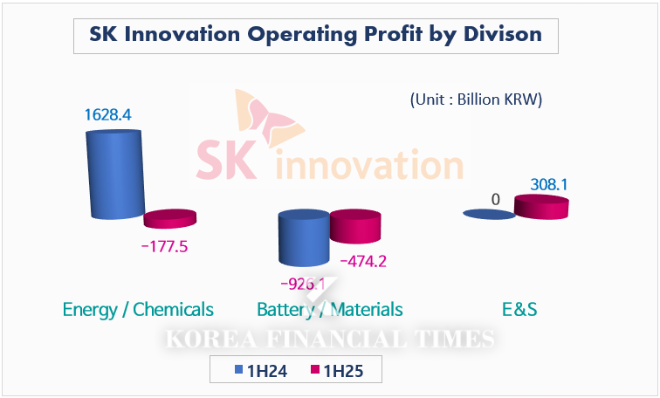
Losses in the battery and materials business divisions, including subsidiaries SK On and SKIET, were halved to KRW 474.2 billion compared to last year. There was also the effect of SK Innovation E&S, which merged in November last year (operating profit of KRW 308.1 billion).
However, the energy and chemicals division (refining, petrochemicals, lubricants, etc.) posted a loss of KRW 177.5 billion in the first half of this year from an operating profit of KRW 1.628 trillion in the first half of last year. In particular, the core refining business recorded a loss of KRW 466.3 billion in the second quarter, significantly deteriorating overall performance. US tariff threats and OPEC+ production increase stance pulled down international oil prices, which led to inventory losses for SK Innovation's refining operations.
Financial-related losses were KRW 685.6 billion, down KRW 320 billion from a year earlier. This was due to increased foreign exchange gains from won weakness, but interest expenses alone increased 21 percent to KRW 794.6 billion. Net borrowings surged from KRW 19 trillion at the end of the first half of last year to KRW 33 trillion at the end of the first half of this year, and the debt ratio increased 42 percentage points to 203 percent.
As the financial structure deteriorated, Moody's lowered SK Innovation's credit rating from 'Baa3' to 'Ba1' in March. In response, Jang Yong-ho, CEO of SK Inc., was appointed to concurrently serve as chief executive president of SK Innovation in May. Chief executive president Jang is an SK Group rebalancing expert, and this was a bold move of replacing the chief executive officer for financial improvement.
SK Safeguards Battery Business with Cash Cow Enmove, While LG Sells Non-Core Growth BusinessesFrom LOTTE and SK to LG and EcoPro… Battery and Petrochemical Firms Turn to Price Return Swap (PRS) for FundraisingPetrochemical Restructuring Underway… Will S-OIL’s ‘Time Bomb’ Go Off?Why Did Kakao and KT Fall Short Against Naver and SKT in Korea’s ‘National AI’ Selection?
However, the burden of SK On's accumulated losses remains a persistent challenge. The rebound timing continues to be postponed. SK On is expected to see expanded losses in the third quarter due to initial operating costs at the US Ford joint venture plant. Additionally, with the early termination of US electric vehicle purchase subsidies from the 30th, it is difficult to guarantee a return to profitability next year.
Chief executive president Jang also sees that SK On will need time. Along with the capital expansion plan, SK Innovation purchased all convertible preferred shares (CPS) held by SK On's financial investors (FI). This eliminated the obligation for SK On's initial public offering (IPO) promised for 2026. In November, SK On will be merged with lubricant subsidiary SK Enмove to improve the financial structure. Jang said "SK On needs to focus on maximising profitability and strengthening fundamental competitiveness for the time being. Currently, there are no IPO plans."
Gwak Horyung (horr@fntimes.com)


















