





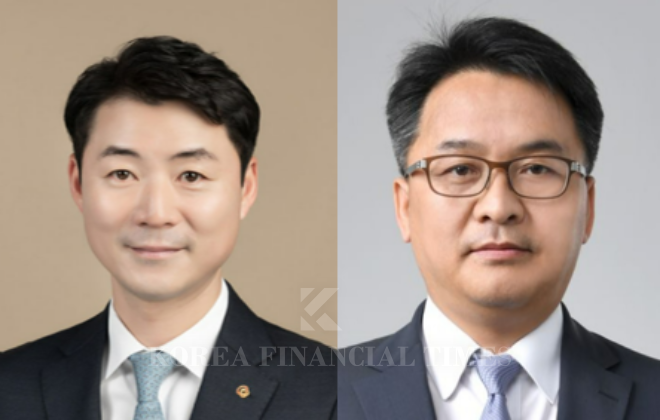
(From left) Park Seung-deok, CEO of Hanwha Solutions, and Park Jong-hwan, CEO of HD Hyundai Energy Solutions. /Photo courtesy of each company
이미지 확대보기
Despite both companies delivering strong performances in the solar energy business during the first half of this year, there are concerns that their paths may soon diverge sharply. As the nation’s leading solar firms, their business areas, outlooks, and potential for future policy benefits differ substantially, demanding close observation.
According to Korean Financial News’ analysis leveraging data from DeepSearch, the cumulative total shareholder return (TSR) of Hanwha Solutions and HD Hyundai Energy Solutions for the first half of 2025 has been calculated.
TSR measures the total return that shareholders can realize over a period, adding together share price appreciation and dividends, divided by the purchase price—a common indicator of both investment performance and shareholder rewards.
In the first half of this year, Hanwha Solutions posted a TSR of 98%, and HD Hyundai Energy Solutions 115%. An investor who put KRW10 million into either company on January 2 and held until June 30 would now have KRW19.8 million with Hanwha Solutions, and KRW21.5 million with HD Hyundai Energy Solutions.
HD Hyundai Energy Solutions achieved its 115% TSR exclusively through share price gains, as it hasn’t paid a dividend in the past two years since its 2022 year-end payout.
In contrast, Hanwha Solutions—despite recording a net loss of KRW1.369 trillion last year—distributed a year-end dividend of KRW300 per share and notched a 98% TSR through a 96% rise in share price and the dividend.
While such returns may stoke optimism around renewable energy, the outlooks for the two companies are split. One is positioned to bask in favorable solar market conditions in the latter half of the year, while the other may not be so fortunate.
Hanwha Solutions’ mainstay is the solar business, though it also encompasses chemical and construction units. Q CELLS (solar) accounts for 52% of revenue, whereas Chemicals—affected by an industry downturn—make up 35%, denting results recently.
Despite these headwinds, Hanwha Solutions delivered an operating profit exceeding KRW100 billion in the first half, turning around from a loss of over KRW300 billion last year. This was fueled by increased solar module sales and a narrowing deficit in the chemicals division.
However, during last month's Q2 earnings call, the company warned that its renewable energy business may swing to an operating loss in Q3.
Disruptions from cell quality issues at factories in Korea and Malaysia in June led to increased fixed costs, and the company foresees a Q3 operating loss in the low KRW100 billion range. However, A company spokesperson indicated the cell quality issue has been resolved, and exports to the US have normalized.
Uncertainty still lingers in Hanwha Solutions’ most important market—the United States—where fears persist that President Trump’s enactment of the “One Big Beautiful Bill Act (OBBBA)” could slow the residential energy market.
Nonetheless, the maintenance of the Advanced Manufacturing Production Credit (AMPC) and strengthened US restrictions on Chinese solar suppliers are expected to benefit Hanwha Solutions.
According to Samsung Securities analyst Cho Hyun-ryul, “Short-term earnings deterioration for Hanwha Solutions is inevitable, but after one-off factors in Q3 subside, a recovery is expected from Q4 onward.”
HD Hyundai Energy Solutions, which focuses on the domestic solar market, is considered comparatively stable.
A company representative said, “We expect new renewable energy policies under the new administration to kick off in earnest in the second half, supporting an even stronger performance than in H1.”
Kim Jin-hyung, analyst at DS Investment & Securities, forecasts, “HD Hyundai Energy Solutions is expected to post operating profits in excess of KRW10 billion in both Q3 and Q4. Rapidly rising solar demand in the US should also provide additional upside for the company.”
Shin Haeju (hjs0509@fntimes.com)




















