





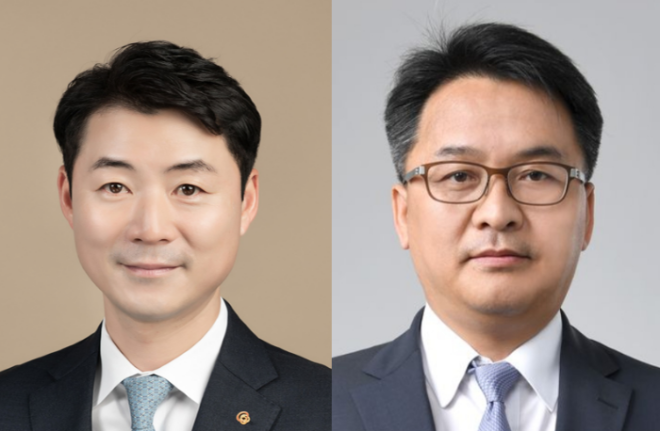
Park Seung-deok, newly appointed CEO-designate of Hanwha Solutions QCELLS Division (left), and Park Jong-hwan, CEO of HD Hyundai Energy Solutions. / Photo = respective companies
이미지 확대보기
In the solar sector, Hanwha Solutions currently leads. Hanwha Solutions is the top solar company in Korea, recording consolidated sales of KRW 12.394 trillion at the end of last year. Of this, the QCELLS division, which is dedicated to solar business, accounted for KRW 7.572 trillion.
HD Hyundai Energy Solutions is the second-largest player domestically, but the scale difference is significant. During the same period, HD Hyundai Energy Solutions posted sales of KRW 422.4 billion.
First-quarter results this year also show contrasting performances. On a consolidated basis, Hanwha Solutions’ sales rose 31.5% year-on-year to KRW 3.0945 trillion, with operating profit turning to KRW 214.6 billion from an operating loss of KRW 30.3 billion a year earlier.
In contrast, HD Hyundai Energy Solutions’ sales fell 12.6% year-on-year to KRW 85.3 billion, and the company swung to an operating loss of KRW 3 billion after posting an operating profit of KRW 14.2 billion in the same period last year.
A major factor is the difference in business regions. Hanwha QCELLS earns 89% of its revenue overseas, while HD Hyundai Energy Solutions derives 71% of its revenue from the domestic market.
HD Hyundai Energy Solutions focuses on domestic sales, with all its cell and module production facilities located in Korea. As a result, despite increased sales in Europe, Australia, and the US in Q1, overall performance declined due to weaker domestic demand for modules and inverters, the off-season for solar module and power system sales from January to March, and a surge in Chinese imports.
In contrast, Hanwha QCELLS’ main battleground is the US, where it holds the top market share in both the residential and commercial solar module markets. Since last year, most of its solar modules have been produced in its US factories.
Hanwha’s Third Son Kim Dong-seon Shuts Down SNS, Launches New BusinessesHanwha’s Kim Seung-youn and Kim Dong-kwan: Will the Father-Son 'Parallel Theory' Be Completed?Hanwha DK, the Only 1980s-born Heir to Complete SuccessionHD Hyundai, LIG, and KAI Team Up for 'Futuristic Unmanned Vessel Project' — Hanwha Left Out?
HD Hyundai Energy Solutions has a longer history, having started as Hyundai Heavy Industries’ Green Energy Division in 2004 and becoming an independent company in 2016. Hanwha QCELLS entered the solar business in 2012 by acquiring QCELLS, then the leading solar cell manufacturer in Europe.
HD Hyundai Energy Solutions has a longer history, having started as Hyundai Heavy Industries’ Green Energy Division in 2004 and becoming an independent company in 2016. Hanwha QCELLS entered the solar business in 2012 by acquiring QCELLS, then the leading solar cell manufacturer in Europe.
The solar industry is known to have limitations in self-sustained growth without government support and policy backing. Recently, both companies have drawn attention thanks to President Lee Jae-myung’s energy policy stance.
President Lee has pledged to develop profit-sharing renewable energy projects such as “Sunshine Pension” (solar power) to boost local incomes and to reform the power purchase agreement (PPA) system to allow direct renewable energy purchases without going through Korea Electric Power Corporation.
These expectations have moved the market. On the eve of the presidential election, HD Hyundai Energy Solutions’ closing price soared to KRW 52,600, its highest this year. On the same day, Hanwha Solutions re-entered the KRW 30,000 range, and on the 11th, the stock surged 19.6% to KRW 37,200.
Global solar installation forecasts continue to rise. According to the Korea Energy Economics Institute, new global solar power installations are expected to reach about 700 GW in 2025, a 17% increase from the previous year. SolarPower Europe also projects a significant increase in global solar power demand between 2025 and 2028.
Shin Haeju (hjs0509@fntimes.com)


















