





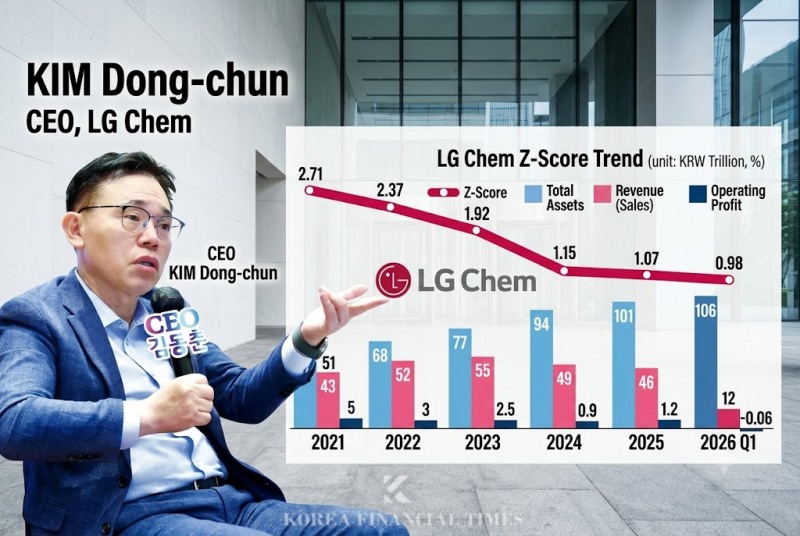
This infographic, originally published by Korea Financial Times, has been reconstructed using generative AI.
이미지 확대보기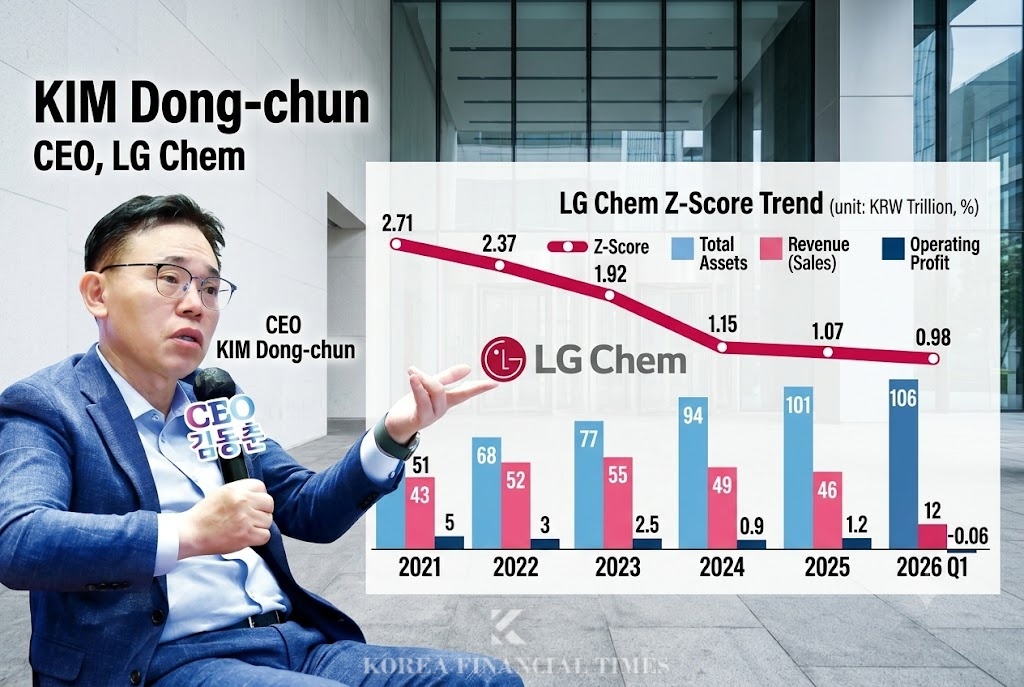
The bigger the dream, the better — or so goes the ambition LG Chem CEO Kim Dong-chun voiced to employees and executives late last month.
Reality is less forgiving. In the first quarter of this year, LG Chem's standalone operating margin — excluding subsidiaries such as LG Energy Solution — stood at just 3.2%.
Regardless, there is a task the company must tackle before it can reach its lofty goals: restructuring its traditional chemical business, whose profitability has been severely squeezed by competition from China and the Middle East.
LG Chem is South Korea's largest operator of naphtha cracking centers (NCCs), with a combined annual ethylene production capacity of 3.3 million tons — the basic raw material for petrochemicals — at its Yeosu No. 1 and No. 2 plants and its Daesan plant. The company had reportedly discussed selling a partial stake in its NCC operations to Kuwait's state-owned oil company, but that deal fell through last year.
LG Chem is now taking part in a government-led restructuring plan for the petrochemical industry. Under the plan, companies are voluntarily agreeing to consolidate or shut down NCC facilities in line with government guidelines for reducing overall capacity.
LG Corp. Taps Asset Sale Proceeds to Defend Dividend Amid Subsidiary SlumpA Shrimp Between Two Whales: Korea Petrochemical Caught Between S-Oil and China[Petrochemicals: A Shifting Landscape] Korea's Petrochemical Restructuring Accelerates as Middle East Crisis BitesLotte-HD Hyundai Daesan Merger Signals Full-Scale Petrochemical Restructuring in KoreaSK, LG, LOTTE: 'Secure Cash!' — Restructuring, Liquidity Drive 'All-In'
But LG Chem has little room to spare. Having poured resources into expanding its battery and battery materials facilities, the company's financial strength is being depleted quickly amid weak profitability.
According to THE COMPASS, an AI-based platform developed in-house by Korea Financial Times, LG Chem's Altman Z-Score has declined every year — from 2.71 in 2021 to 2.37 in 2022, 1.92 in 2023, 1.15 in 2024, and 1.07 in 2025. In the first quarter of this year, it fell below 1 for the first time, to 0.98.
The Altman Z-Score is a corporate distress prediction model developed by Professor Edward Altman in 1968. It is calculated by applying weights to five sub-indicators: working capital to total assets (X1), retained earnings to total assets (X2), earnings before interest and taxes to total assets (X3), market value of equity to total liabilities (X4), and sales to total assets (X5). A score above 3.0 is considered "safe," while a score below 1.8 signals "distress."
To be clear, interpreting this as meaning LG Chem faces imminent bankruptcy would be an overstatement. The petrochemical industry, which operates with large assets and heavy borrowing, tends to produce lower Z-Scores by nature. A more reasonable reading is that the worsening trend represents a "warning light" — a sign the company could be more vulnerable to additional external shocks.
Over the past five years, LG Chem's X3 (operating profit to total assets) has shrunk to about one-fifteenth of its previous level, while X5 (sales to total assets) has been cut in half. Sales and operating profit have failed to keep pace with the growth of its asset base — a clear illustration of the petrochemical industry's structural crisis.
Consolidating NCC facilities could help address this structural inefficiency. Rationalizing redundant capacity across the industry would reduce assets, while joint naphtha purchasing or vertical integration with refiners could lower costs and boost profitability.
But it looks unlikely that the company's own operations alone can turn the situation around anytime soon. LG Chem's consolidated operating cash flow swung to a deficit of KRW 175.9 billion in the first quarter. Although its petrochemical business staged a surprise rebound thanks to war-related demand, this was offset by LG Energy Solution posting a loss of roughly KRW 210 billion.
Consolidated capital expenditure over the same period came to KRW 2.2979 trillion. Although that is down 44% from the first quarter of last year, the company's investment spending still exceeds what its earnings can support. At this pace, its free cash flow (FCF) deficit could double from last year's level.
Beyond pushing for petrochemical consolidation, the company is also pursuing an asset-sale-driven "stay-the-course" strategy. In particular, selling a 9.4-percentage-point slice of its 79.4% stake in LG Energy Solution to raise cash is seen as a key card for easing its financial burden.
However, activist investors have argued that proceeds from any such stake sale should go toward shareholder returns, such as share buybacks and cancellations — meaning persuading them will likely be another challenge ahead.
Gwak Horyung (horr@fntimes.com)





















