





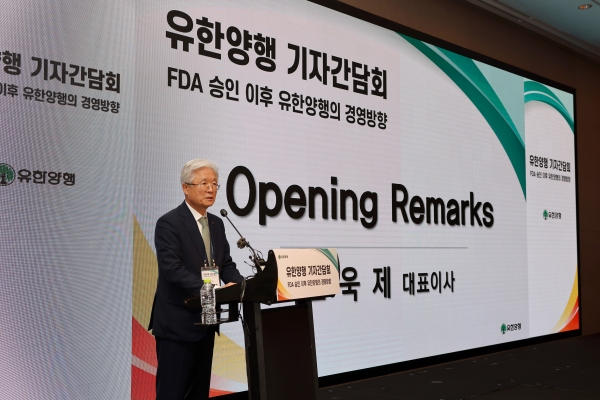
Cho Wook-je, CEO of Yuhan Corporation, speaks at a press conference. / Photo = Yuhan Corporation
According to financial reports filed with the Financial Supervisory Service on the 13th, Yuhan Corporation’s consolidated revenue for last year increased by 11.2% year-on-year, reaching KRW 2.0678 trillion.
Yuhan attributed its strong revenue performance to an increase in licensing revenue from technology exports as well as higher sales from both the parent company and its subsidiaries.
This marks the first time a domestic pharmaceutical company has exceeded KRW 2 trillion in annual revenue. A key contributor was 'Leclaza,' which received approval from the U.S. Food and Drug Administration (FDA). In August of last year, Yuhan secured a $60 million (approximately KRW 87 billion) milestone payment when 'Leclaza,' in combination with Johnson & Johnson’s antibody drug 'Rybrevant,' was approved in the U.S. as a first-line treatment for NSCLC. This milestone payment significantly boosted the company’s third-quarter performance, helping it achieve record-high quarterly revenue of KRW 598.8 billion. Operating profit surged to KRW 47.6 billion, marking a 5,288% year-on-year increase.
Additionally, 'Leclaza' was newly listed for insurance reimbursement in South Korea last year, leading to increased prescriptions. Sales of the drug rose by 53% year-on-year, reaching KRW 47.8 billion compared to KRW 22.8 billion the previous year.
Despite record-breaking revenue, annual profitability declined. Yuhan Corporation’s operating profit for last year dropped 16.4% to KRW 47.7 billion due to a substantial investment in research and development (R&D). The company spent KRW 277.1 billion on R&D, a 67.4% increase from the KRW 165.5 billion spent the previous year.
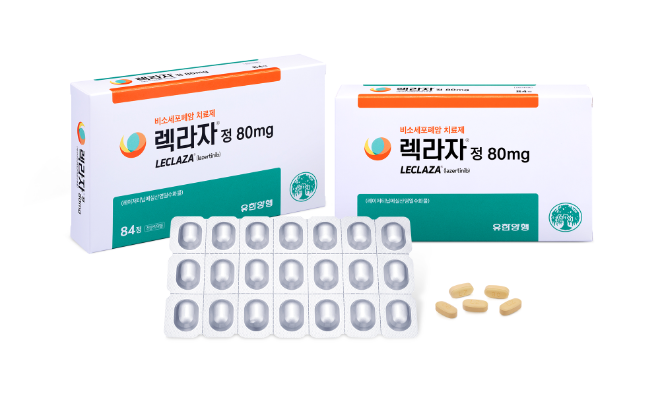

The delay in receiving milestone payments from 'Leclaza’s' European launch also impacted profitability. Although 'Leclaza' was granted marketing authorization in Europe in December last year, Yuhan has yet to receive its expected $30 million (approximately KRW 44 billion) milestone payment from Johnson & Johnson. Furthermore, the company will earn royalties of approximately 10% on 'Leclaza' sales in Europe.
Overseas is the answer?... Yuhan Corp. · GC Bio, etc. Pharmabio industry, Q3 profits soar on 'global' rideK-PharmaBio, Will 20 Years of R&D See the Light?… Expectations for 10th FDA and 1 Trillion Blockbuster Increase↑Samsung Biologics Replaces CFO and R&D Head... Will It Find New Momentum This Year?K-PharmaBio’s First 'KRW 4 Trillion Club' Member – Samsung Biologics Eyes KRW 5 Trillion with Unmatched Excellence in CapacityGC Group's 3 generations making their presence felt...'uncle-nephew' is gone, 'cousin management' is coming
There is also growing anticipation for the emergence of a 'next Leclaza.' The leading candidate is the allergy drug candidate 'YH35324.' On the 11th, Yuhan Corporation announced that YH35324 demonstrated superior efficacy compared to existing treatments in its Phase 1b clinical trial. The candidate showed positive results in improving symptoms and safety compared to the competing drug 'Xolair' in patients with chronic spontaneous urticaria (CSU). Detailed clinical results will be presented at the American Academy of Allergy, Asthma & Immunology (AAAAI) meeting later this month.
Industry experts believe that if the AAAAI presentation yields favorable results, YH35324 could be licensed out to a multinational pharmaceutical company this year. Yuhan Corporation has already outlined plans to secure at least one technology export deal annually from this year through 2027.
A Yuhan Corporation official stated, "During the Phase 1b trial for YH35324, we confirmed its potential for improved treatment efficacy and safety compared to existing therapies. Through further clinical development, we aim to bring a new treatment option to patients suffering from allergic diseases as soon as possible."
Kim Nayoung, Korea Finacial Times (steaming@fntimes.com)




















