





While the second shareholder letter contained the advantages of the spin-off merger that has been revealed so far, the third shareholder letter contained a rebuttal to the proxy exercise recommendation published by ISS (Institutional Shareholder Services), the world's largest proxy advisory firm. On the 28th of last month, ISS advised investors to oppose the 'Approval of the Spin-off Merger Agreement' that Doosan Enerbility had submitted as an agenda item for the extraordinary general meeting of shareholders.
CEO Park Sang-hyun said, "ISS's analysis contains significant errors and one-sided claims that do not match the facts," and "We found more than 10 errors, large and small, in the ISS report."
Park criticized, "ISS pointed out that this transaction was not reviewed by a special committee comprised only of outside directors, despite the fact that it involved a conflict of interest between the majority and minority shareholders, but this is due to ignorance of Korean commercial law."
According to the Commercial Law, a spin-off merger that requires approval from a general shareholders' meeting cannot be delegated to a committee within the board of directors, and the board of directors must directly resolve it and propose it to the general shareholders' meeting. It is impossible for a special committee, not the board of directors, to deliberate and decide on this transaction.
He said, "This spin-off merger is not a transaction to strengthen the control or profit of major shareholders," and "The only difference is which affiliate Doosan Bobcat becomes a subsidiary of, but the control is the same."
He added, “On the contrary, Doosan's voting rights in Doosan Robotics will be diluted from 68% to 57%, and there will be no dividend or other benefit to Doosan from the transaction.”
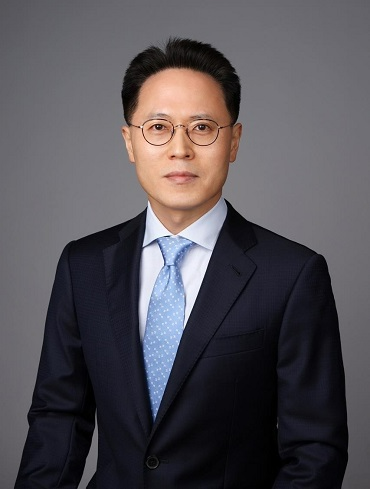
▲Park Sang-hyun, CEO of Doosan Enerbility
In the case of Doosan Bobcat, since most of its business sites are overseas, considering the size of its sales, it is necessary to report business combinations in more than 10 countries. It is difficult to predict when approval will be completed. There is also a risk that approval may be rejected depending on who the buyer is. For example, in the case of Korean Air and Asiana Airlines, which are currently in the process of merging, it took about 4 years to get approval for the overseas business combination.
Park said, "Considering the down cycle of Doosan Bobcat's business, the delay in the sale period or the success of the sale is even more uncertain," and "The success rate of recent M&A cases is around 20%."
In response to the suggestion that Doosan Bobcat is undervalued compared to other Asian peers, Mr. Lee emphasized that “the companies listed in the ISS report are not peers in terms of their focus, geography and size.
It is not reasonable to conclude that Doosan Bobcat is undervalued by directly comparing the value ratios of Doosan Bobcat and its Asian peers without considering the specifics of each market.
In the case of Chinese companies, it was pointed out that the domestic economic stimulus policy has a significant impact on sales growth and that it is an industry practice to exclude them from the same industry because the market characteristics are significant. It is also necessary to consider the fact that the domestic stock market itself is undervalued compared to the Japanese and Chinese markets.
Park said, "It is questionable whether the ISS dissenting opinion written based on incorrect facts can guarantee credibility."
Currently, Doosan Enerbility is proposing a merger ratio of 1 to 0.043 for Doosan Robotics and the new corporation of Doosan Enerbility that owns Doosan Bobcat.
Shin Haeju (hjs0509@fntimes.com)




















