





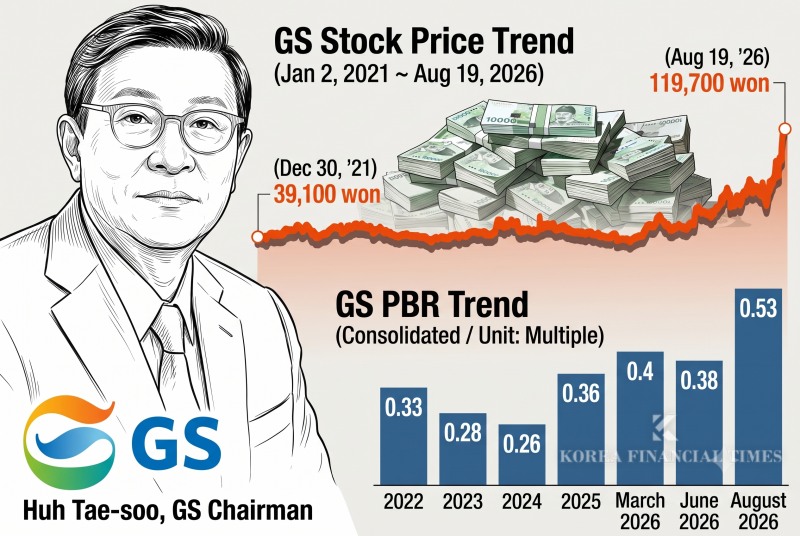
This infographic, originally published by Korea Financial Times, has been reconstructed using generative AI.
이미지 확대보기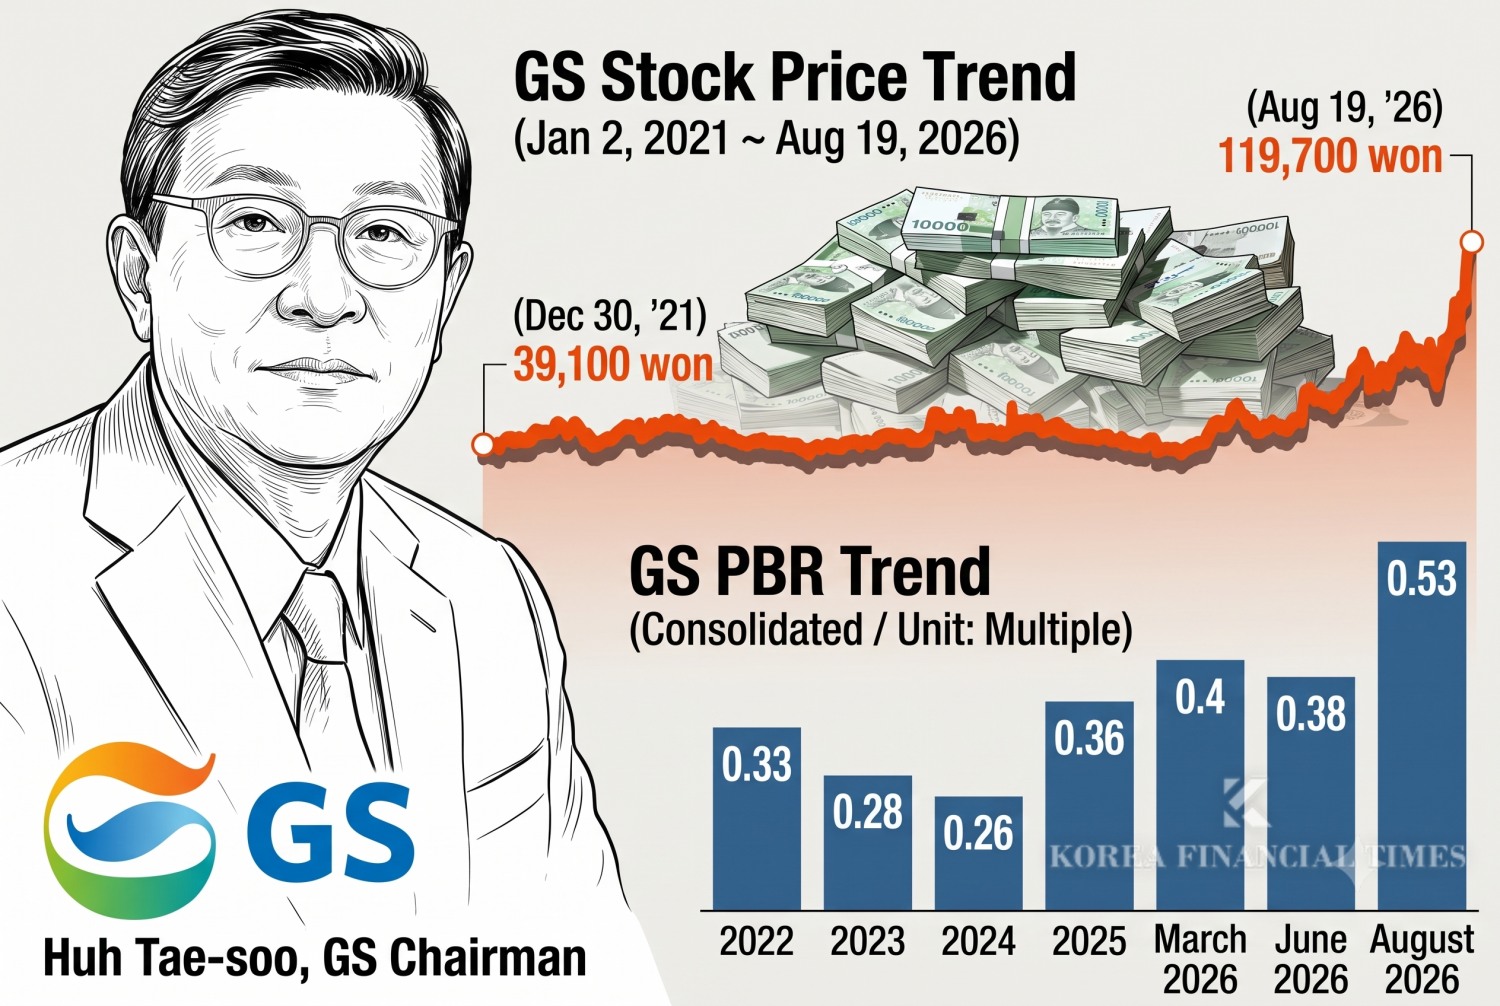
On August 13, the stock closed at KRW 107,400 per share, surpassing the previous all-time high of KRW 103,000 set on April 21, 2011 — during the era of the so-called "Cha-Hwa-Jeong" boom (automobiles, chemicals and refining) — for the first time in roughly 15 years and four months. The stock closed at KRW 114,600 on August 24, down 1.38% from the previous session.
GS shares began their rally in July, just as the KOSPI turned weak. Over the 30 trading sessions from July 3 to August 18, the KOSPI fell 15%, while GS surged 63%.
Behind this sharp rise is widely seen as the solid earnings performance centered on GS Caltex, a grandchild subsidiary of the group. Refiners SK Innovation and S-Oil have also shown strength since July.
Adding to the momentum is growing optimism that GS may finally shed its longtime image as "a conglomerate without a growth engine," after the company announced a roughly KRW 15 trillion data center project in Donghae, Gangwon Province. Most of the funding is expected to come from project financing (PF) and other outside investors.
Under the plan, holding company GS will oversee the overall investment, while affiliates — GS E&C (construction), GS EPS (power generation) and GS Caltex (cooling systems) — work together to maximize business synergies. The move is seen as significant in that it marks the start of new-business investment aimed at reducing the group's traditional reliance on energy, construction and retail.
Alongside this business momentum, active discussion of the so-called "anti stock-price suppression law" is also seen as having influenced the share price.
The bill, originally proposed in May last year by Rep. Lee So-young of the Democratic Party of Korea, was centered on imposing higher inheritance and gift taxes — calculated based on a company's actual assets or earnings — on listed firms with a price-to-book ratio (PBR) below 0.8x. GS was widely cited as a prime target of the legislation.
'Expansion' S-OIL vs. 'Caution' GS Caltex [KFT Topic]LS, L&F Reunite Founding Families in Business After 18 YearsAs Ambitions Grow, LG Chem's Financial Health Quietly Erodes[Petrochemicals: A Shifting Landscape] Korea's Petrochemical Restructuring Accelerates as Middle East Crisis BitesLotte-HD Hyundai Daesan Merger Signals Full-Scale Petrochemical Restructuring in Korea
However, in the tax reform plan the government unveiled on August 3, the scope was effectively narrowed to companies whose PBR has ranked in the bottom 25% of their sector on the KOSPI over the past six years.
In response, the Korea Corporate Governance Forum issued a statement criticizing the change as "effectively granting amnesty to low-PBR companies," saying it would exclude GS, Lotte Corporation, DL, Taekwang Industry, Hanwha Life, Daishin Securities and Emart from the list of target companies.
The government is currently conducting a full review of the reform plan, meaning the issue of correcting undervaluation remains a key policy watchpoint.
Yet despite this combination of new-business momentum and policy developments, GS shares remain deeply undervalued.
Even at KRW 120,000 per share, the company's PBR stands at just 0.53x on a consolidated basis (0.68x excluding non-controlling interests) — meaning the stock is trading at a discount of roughly 30–50% to book value.
What's more, GS joined the rally relatively late. As of the end of the second quarter this year, when the stock was still trading in the KRW 60,000–70,000 range, GS's PBR stood at around 0.4x. Among the holding companies of Korea's ten largest conglomerates, the only one with a lower PBR than GS is Lotte Corporation (0.37x), which has yet to resolve its treasury-stock issue.
This stands in contrast to SK Inc. (1.53x) and HD Hyundai (1.31x), which have emerged from severe undervaluation on the back of optimism over affiliate businesses and plans to retire existing treasury shares in line with revisions to the Commercial Act.
The fundamental reason behind GS's chronic undervaluation is widely attributed to its passive approach to shareholder returns. The company retired treasury shares in May, but the volume canceled amounted to less than 0.03% of the total — a token gesture toward complying with the revised Commercial Act, offering little in the way of meaningful shareholder-value enhancement.
Dividends, however, are relatively generous.
Although payouts fluctuate with GS Caltex's earnings, the company has maintained a high dividend yield of 4–7% annually.
The reason behind this high-dividend policy lies in GS Group's dispersed ownership structure. A 43.53% stake in GS is split among 58 members of the founding family, including family-owned entities. Seventeen related parties alone hold stakes of 1% or more.
GS Group traces its roots to the eight sons of Huh Man-jung — a co-founder of LG Group — and their descendants, and today, fourth-generation family members who are rising to leadership positions hold divided stakes and jointly participate in management across generations. In an ownership structure marked by frequent succession and gift transfers, it is more advantageous for the founding family to take home large dividends while keeping the share price relatively low.
Gwak Horyung (horr@fntimes.com)





















