





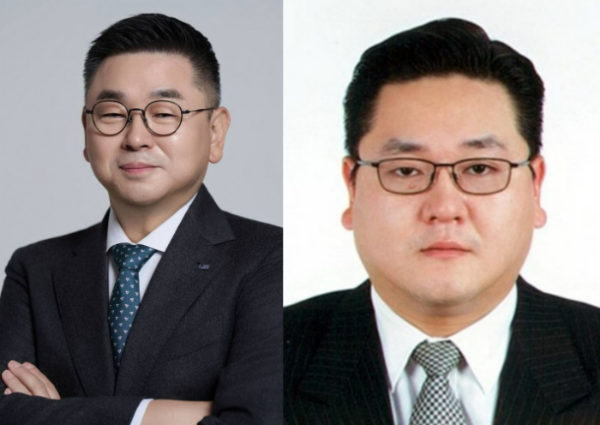
(From left) LIG Chairman Koo Bon-sang and Vice Chairman Koo Bon-yeop. /Photo provided by LIG Group
According to the Fair Trade Commission's "2025 Analysis of Holding Company Ownership and Investment Status," the founding family's stake in holding company LIG reaches 75%.
This significantly exceeds the average of 47.4% for the 47 major conglomerates' holding companies in Korea. LIG is currently controlled by two brothers, Chairman Koo Bon-sang and Vice Chairman Koo Bon-yeop, who hold 41.17% and 26.20% stakes respectively. Compared to the average stake of 24.80% for general holding company chairmen, Chairman Koo Bon-sang's control is relatively high.
However, considering that LIG is an unlisted holding company, the founding family's ownership stake follows a similar pattern to other unlisted companies. In fact, among the total 47 companies, the 10 unlisted holding companies show an average founding family ownership rate of 80%. Examples include Celltrion, where the chairman holds 98.13%, and Joongheung Construction, Hyosung, and Bandoo Holdings, where founding families hold 100%.
LIG's revenue structure is characterized by a small proportion of dividend income and high dependence on brand royalties. Last year, the company collected KRW 7.5 billion in trademark royalties from affiliates. In contrast, dividend income accounted for only 4.5% of total revenue. This falls far short of the holding company average dividend income ratio of 51.5%. Typically, holding company revenue sources consist of dividend income, non-dividend income such as trademark royalties, real estate rental fees, management and consulting fees, and business sales.
The existence of "off-system affiliates" subject to private benefit extraction regulations is also a variable. LIG owns "KJ Rental," where the founding family's stake reaches 87.5%. This company is owned by Koo Ji-jeong and Koo Ji-yeon, Chairman Koo Bon-sang's elder sisters, who hold 50% and 37.5% stakes respectively. Off-system affiliates are affiliates that are not holding companies or their subsidiaries, grandchild companies, or great-grandchild companies, and among these, domestic affiliates where the founding family holds more than 20% are subject to private benefit extraction regulations under the Fair Trade Act.
Some in the industry are raising the opinion that governance risk management is necessary, as LIG Nex1, LIG's core affiliate, recently changed its name to "LIG Defense & Aerospace (LIG D&A)" and is accelerating its global market expansion. Currently, LIG is the largest shareholder of LIG Nex1 with a 37.74% stake.
Cho Yong-doo, visiting professor of business administration at Sungkyunkwan University, noted in a contribution to Samil Accounting Corporation titled "The Future of K-Corporate Governance for Growth and Innovation" that "according to the Korea Institute of Corporate Governance and Sustainability, companies that have maintained top governance rankings over the past 20 years are mainly those that have adopted professional management systems." He added, "While owner management has strengths in terms of long-term investment and value creation, risks such as abuse of power and infringement of minority shareholder rights also persist."
LIG Nex1 Accelerates Global Expansion Amid Surging Defense ExportsK-Defense Gets an AI Boost as HD Hyundai and LIG Nex1 Join Forces with PalantirWhich Korean Companies Are Partnering with Palantir, co‑founded by PayPal alumni?Hanwha Systems' Operating Profit Down 60% Due to Philly Shipyard Investment: "Nuclear Submarine Plan Undecided"
He emphasized, "This is a time when wisdom is needed to reduce institutional risk factors for large corporations to sustain innovation and long-term growth."
Shin Haeju (hjs0509@fntimes.com)





















