





According to industry sources on the 17th, Celltrion disclosed on the 16th that it would cancel the entirety of the treasury shares (544,299 shares) it acquired this month. The cancellation is worth KRW 96.2 billion, reducing the number of shares outstanding from 232,617,176 to 232,072,877.
Share buybacks and cancellations are typically positive catalysts for stock prices. In Celltrion's case, however, the scale of the cancellation is negligible relative to its total shares outstanding, resulting in a muted market response. The company's cumulative share cancellation this year will expand to KRW 200 billion, but even that is not enough to meaningfully move corporate value.
Celltrion has carried out share buybacks and cancellations continuously more than 10 times since 2022. The latest cancellation is being viewed as an extension of the company's existing shareholder return policy, suggesting the event itself may have already been priced into the stock.
Various forms of amortization (from asset revaluation, intangible assets and distribution rights) and higher selling, general and administrative (SG&A) expenses stemming from the 2023 merger with Celltrion Healthcare have weighed on profitability improvement. Celltrion's operating margin fell to 13.8% in 2024 before beginning to recover, but the market remains cautious, wanting confirmation that the amortization burden has been fully resolved.
Healthcare Merger Expanded Asset Base, Exposing the True Nature of Profitability
Behind Celltrion's decision to absorb Celltrion Healthcare was a desire to resolve complex intercompany transactions and lingering doubts over accounting transparency — issues the market had raised consistently since Celltrion's initial listing. The merger was also expected to improve the company's financial fundamentals through cost savings from integration and greater efficiency in investment strategy from unifying its capital resources.
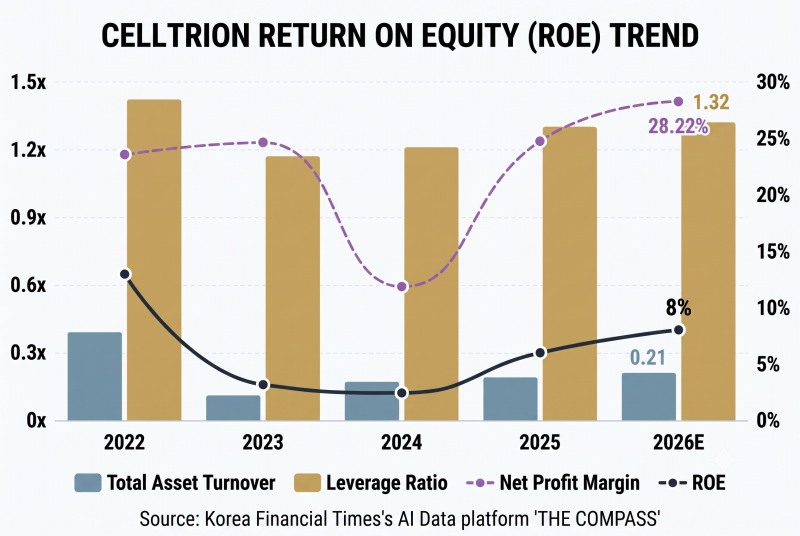
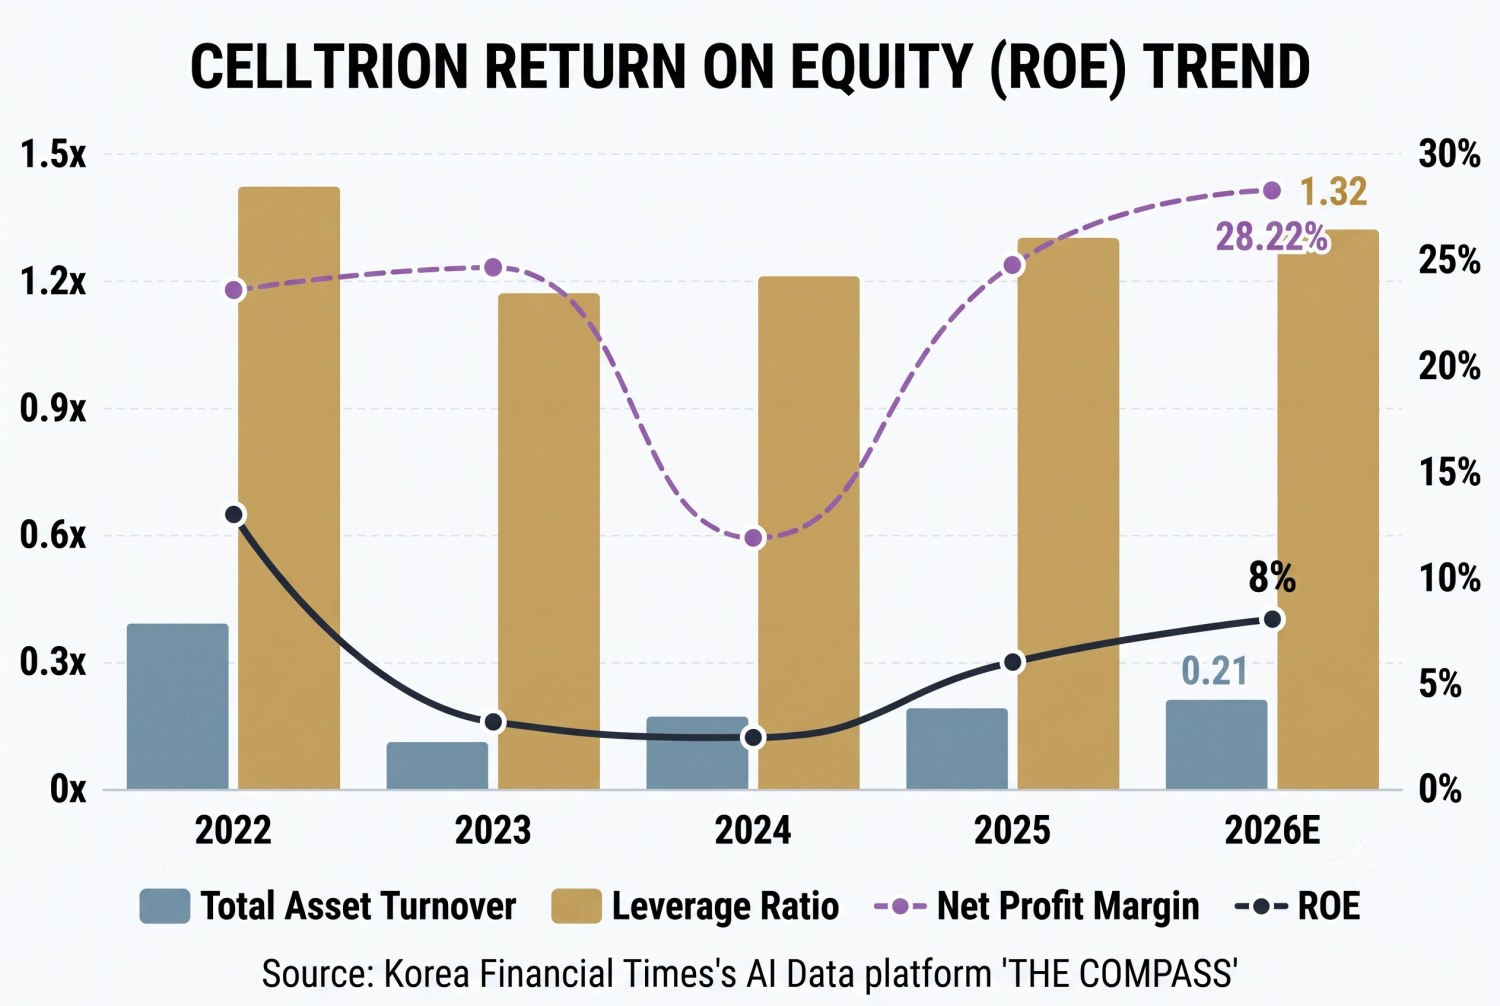
However, return on equity (ROE) — a metric that directly reflects corporate value — fell sharply from 12.99% in 2022, before the merger, to 3.15% in 2023. The biggest driver of the decline in ROE was the drop in total asset turnover, from 0.39x to 0.11x. While the merger nearly tripled the company's asset base, revenue saw little corresponding change.
Celltrion Fires on All Cylinders with Profitability and Shareholder Returns, but Stock Price LagsCelltrion's Share Cancellation Undercut by New Issuance Plan [Treasury Share Report]Bear Robotics IPO Rumors Lift LG Electronics SharesSK Innovation's Shareholders Sidelined From SKIET's Spin-off to MergerKorea's New Inheritance Tax Rule Targets Just 130 of 1,500 Undervalued Stocks
The merger secured accounting transparency, but it did not fully dispel market doubts such as concerns over "duplicate revenue recognition."
As of the end of last year, Celltrion's ROE stood at 5.98%, and is projected to reach 8% on an annualized basis using first-half 2026 figures. Net profit margin has recovered back into the 20% range, surpassing pre-merger levels, but the low asset turnover ratio continues to act as a drag.
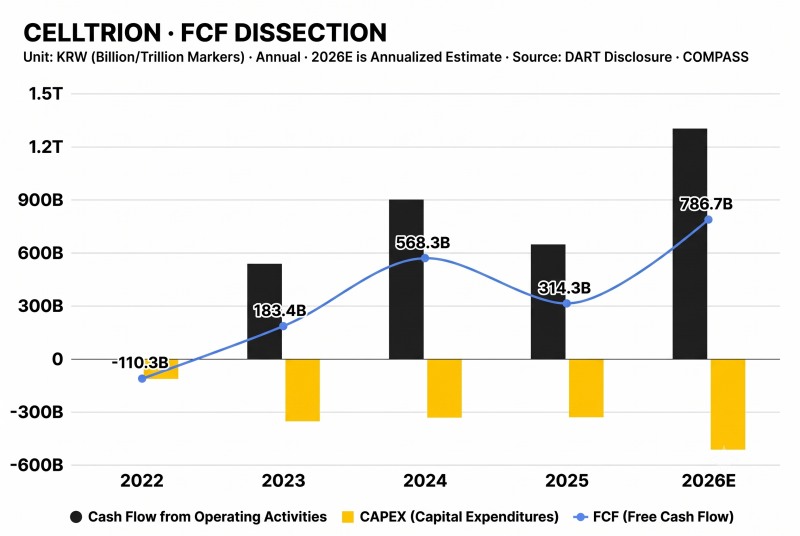
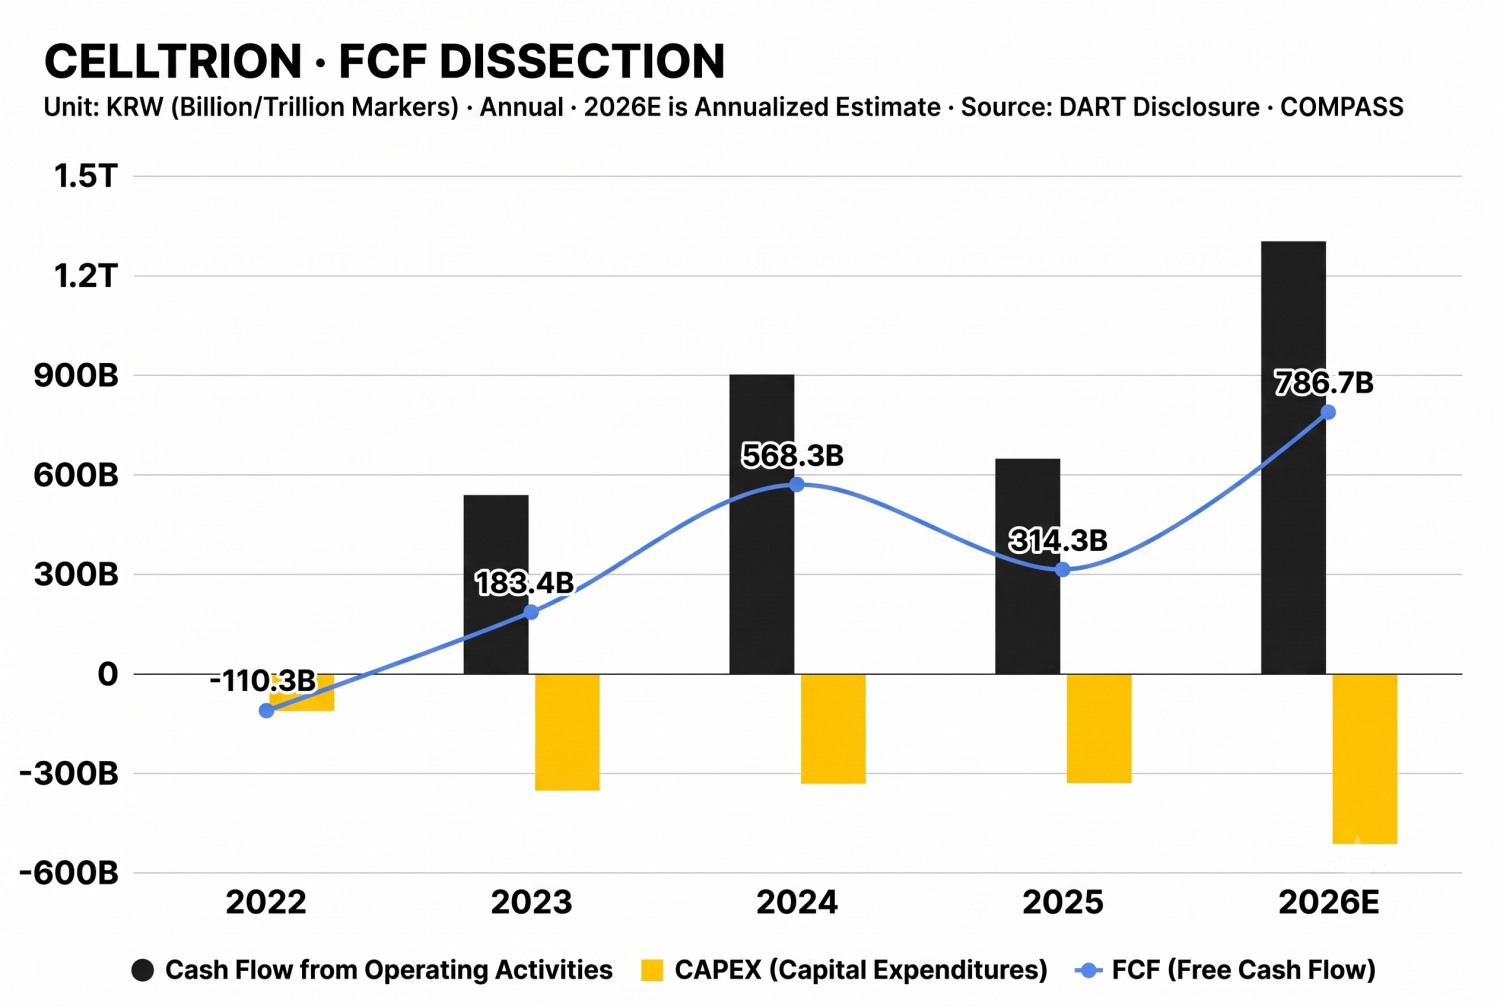
Free cash flow (FCF) — a factor with a significant impact on corporate value and shareholder returns — is expected to reach KRW 786.7 billion this year (annualized based on first-half figures). While this represents more than a twofold increase year-on-year, it also underscores that how explosively revenue can grow going forward remains the most critical variable.
This ties back to lingering doubts over past duplicate revenue recognition. Ultimately, post-merger top-line growth could resolve concerns over capital efficiency as well as past negative perceptions, thereby lifting corporate value. Alternatively, the company could raise per-share value by significantly expanding the scale of shareholder returns beyond current levels.
An investment banking (IB) industry official said, "Since the merger, Celltrion's revenue has been steadily expanding, and its share price has also been gradually trending upward." The official added, "Profitability is improving as well, but it has yet to reach pre-merger levels," and continued, "As it becomes harder to boost profitability the larger a company gets, the scale of shareholder returns needs to be calibrated to the company's size."
Lee Sungkyu (lsk0603@fntimes.com)





















