





Samsung SDS: No. 2 in Cloud, but the Stock Says Otherwise
According to the "2024 Domestic Public Cloud Service (CSP) Market Share" report recently released on the 14th by market research firm IDC, Samsung SDS ranked second in the market with an 11.3% share, trailing only AWS (22%). Excluding global providers, the company also claimed the top spot among domestic players.Earnings have been stable as well. Samsung SDS has posted year-on-year growth in both revenue and operating profit, maintaining consolidated revenue of more than KRW 13 trillion over the past five years.
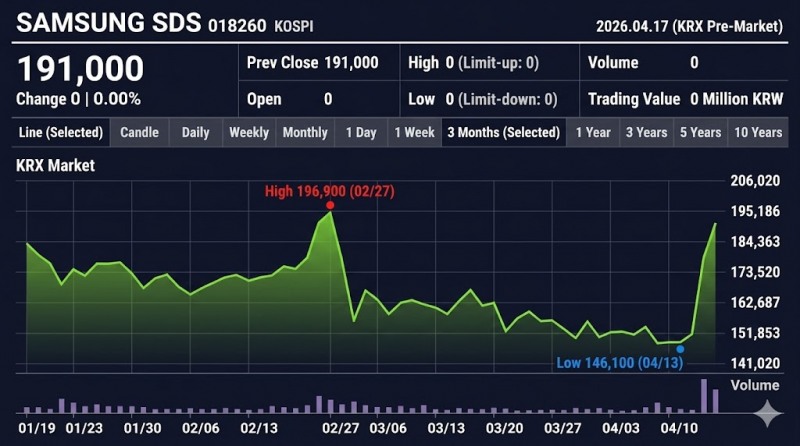
Samsung SDS's Share Price Trend Over the Past Three Months. / Source: Korea Exchange (KRX) / Reconstructed by AI Based on Naver Finance Screen Capture Data.
이미지 확대보기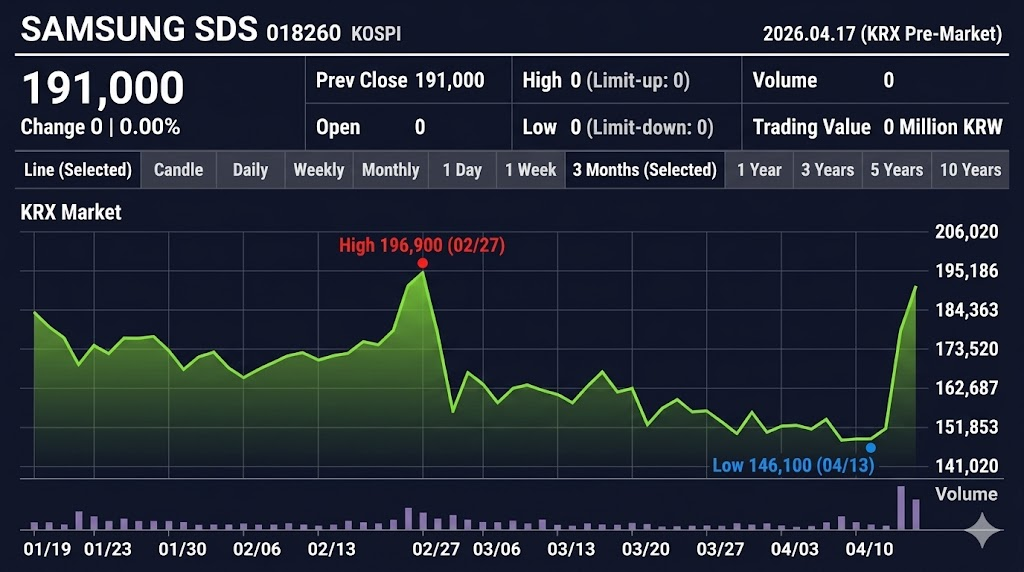
At the same time, the company's cash and cash equivalents stand at roughly KRW 6.0382 trillion — nearly half of its total assets of about KRW 13.5 trillion — giving it an abundant liquidity cushion.
However, given the rapid growth of its AI and cloud-related businesses in recent years, the company's earnings, cash reserves, and growth narrative do not appear to be properly priced in.
Samsung SDS shares hit an intraday high of KRW 196,900 on February 27. Amid a broader KOSPI decline driven by issues such as the Middle East crisis, the stock recently slid to as low as KRW 146,100 before rebounding to close at KRW 191,000 on the 16th. Still, compared with the IPO offering price of KRW 190,000, the share price has been largely stagnant.
Analysts interpret this as a sign that the market is weighing not just revenue and profits but also growth constraints and shareholder return prospects.
Intra-Group Transactions Top 80%… Group Dependence Stands Out More Than Growth
Samsung SDS's growth may look impressive on the surface, but a closer look at the numbers reveals a shadow: rising dependence on the Samsung Group.According to the Data Analysis, Retrieval and Transfer System (DART), Samsung SDS's consolidated revenue last year totaled KRW 13.9299 trillion, of which KRW 11.3712 trillion came from related parties — putting the intra-group transaction ratio at 81.6%. This marks a 1.3 percentage-point increase from 80.3% the previous year.
Companies with a high share of intra-group business face structural limitations. Work tends to be concentrated in specific affiliates, making it difficult to fully separate pricing and quality from external competition. As a result, such companies are more likely to be stuck at low valuations over the long term.
Samsung SDS is no exception. As its image as the Samsung Group's core digital transformation supplier strengthens, its presence as an independent platform company targeting external customers has grown somewhat faint, observers note.
KRW 6 trillion in Cash, Zero Share Buybacks
Within this structure, Samsung SDS's capital allocation policy and return on equity (ROE) are emerging as key variables.
The company's annual EBITDA (earnings before interest, taxes, depreciation, and amortization) stood at about KRW 1.5871 trillion, up 5% year-on-year, while capital expenditures (CAPEX) fell 23% to around KRW 364.8 billion. With more cash coming in and less going out, cash and cash equivalents have swelled to KRW 6.3802 trillion — leaving the company's coffers fully stocked.
Investors, however, are worried about growth uncertainties and insufficient shareholder returns. Samsung SDS has not bought back a single share since its listing in November 2014.
The company's recent payout ratio stands at 32.5%, and while it raised its year-end dividend by 10%, this is not considered particularly high compared with other platform and IT companies. Shareholder coalitions are also demanding that the company present a medium- to long-term return roadmap, including share buybacks and cancellations, arguing that "shareholder return policies fall short given the massive cash pile."
ROE at 8%: Capital Efficiency Falls Short
As the company continues to accumulate cash without actively deploying it through dividends, share buybacks, or growth investments, net profit growth has lagged relatively behind.As a result, ROE fell from 8.42% in 2024 to 7.89% last year. ROE measures how effectively equity is used to generate profits, and analysts say that while capital has grown, the returns flowing back to shareholders have not kept pace.
In the end, while the earnings, cash position, and growth story are all compelling, rising affiliate dependence combined with conservative capital allocation has left investor sentiment divided.
Some see upside potential, particularly in the cloud and AI segments. Samsung SDS has recently been expanding its business scope by winning a series of AI system development and cloud migration projects from public and financial-sector clients outside the group, including the National Assembly and Woori Bank. Others, however, point out that the company's reliance on group-affiliated work remains firmly entrenched.
Going forward, the key challenge for Samsung SDS will be twofold: expanding its external customer base to shed its image as a captive group supplier, and unlocking its KRW 6 trillion cash pile through a concrete roadmap spanning AI infrastructure investment, mergers and acquisitions (M&A), share buybacks, and dividends.
Jeong Chaeyun (chaeyun@fntimes.com)





















