





Kim Jong-woo (English name Michael Kim), CEO of SK Signet, who declared the beginning of the SK Signet 2.0 era. / Photo = SK Signet
이미지 확대보기
SK Group has drawn a clear line against the sale rumors, instead stepping in with capital support to save SK Signet. The company itself has also focused on normalizing management, appointing Kim Jong-woo, a strategist from within the group, as its new CEO last year.
On the 25th, SK Signet held a corporate briefing for analysts and institutional investors. The company stated, “This briefing is to explain our future business direction and plans for business normalization.”
Last month, SK Signet declared its “SK Signet 2.0” initiative, aiming for structural innovation across all operations—including strengthening manufacturing capabilities, enhancing quality, innovating cost structures, and redefining organizational culture. The company also plans to advance ultra-fast charging technology and bolster its software competitiveness to expand globally in markets such as the U.S. and the Middle East.
SK Signet became an SK Group affiliate in August 2021, when the group acquired EV charger manufacturer Signet EV. At the time, SK Inc., the group’s holding company, purchased 1,620,087 shares of Signet EV from Rio Investment for 81 billion KRW, and also acquired 5.92 million newly issued convertible preferred shares (CPS) for 212.2 billion KRW, investing a total of about 300 billion KRW. This was a forward-looking investment to expand the group’s value chain in EV infrastructure ahead of the coming EV era.

(Source : Company Disclosures)
However, in 2023, SK Signet’s performance fell short of expectations due to the EV chasm and persistent charger quality issues. In particular, the company suffered a major blow when its business with Electrify America, the largest charging operator in the U.S., was suspended due to ongoing component failures. Electrify America accounted for 80% of SK Signet’s total charger supply.
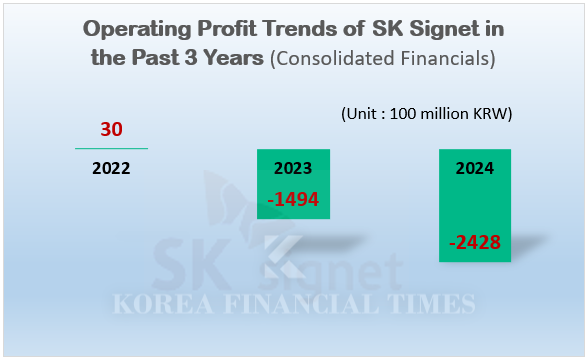
SK Signet posted a consolidated operating profit of 3 billion KRW in 2022, the year after joining SK Group, but swung to an operating loss of 149.4 billion KRW in 2023. Last year, the operating loss widened further to 242.7 billion KRW. Over the same period, revenue halved from 162.3 billion KRW to 83.8 billion KRW.
Total borrowings also soared from 1.2 billion KRW in 2022 to 120 billion KRW last year—a 100-fold increase. Of particular concern is the 99.6 billion KRW in short-term borrowings (due within one year) that must be repaid this year.
SK Signet’s cash reserves to cover these borrowings are running low. The company has posted negative operating cash flow for three consecutive years, and its cash holdings dropped from 89.2 billion KRW in 2022 to 33.5 billion KRW last year. As losses have mounted, accumulated deficits have ballooned from 1.3 billion KRW in 2022 to 375 billion KRW last year.
As SK Signet’s struggles continued, rumors of a sale began to circulate in the industry. This is partly because SK Group has been rebalancing its portfolio since last year, focusing on AI and semiconductors while divesting non-core businesses.

However, SK Group has denied the sale rumors. Instead, it has provided additional capital and is focusing on business normalization. Last month, SK Inc. participated in a third-party rights offering by SK Signet worth about 150 billion KRW, raising its stake from roughly 52% to 63%. SK Inc. explained that this demonstrates its commitment to normalizing SK Signet.
SK Signet has also been undergoing internal restructuring since appointing Kim Jong-woo (Michael Kim) as CEO in December last year. Kim, who joined SK Networks in 1998, has proven his capabilities at key SK Group affiliates such as SK Enpulse, SKC, and SK Holdings.
As CEO of SK Enpulse, he was highly regarded for successfully growing the advanced materials business for semiconductor front-end processes. At SKC, he led the Business Model Innovation Task Force and headed business development at Solmics, uncovering new business opportunities. At SK Holdings, he was responsible for portfolio management, and during his time at SK Global (now SK Networks), he excelled in crisis management and portfolio building.
Upon taking office at SK Signet, Kim Jong-woo (Michael Kim) prioritized quality management. As a result, SK Signet has improved its field defect rate, maintaining a failure rate of just 0.1% for public rapid charging facilities as of 2025, according to Korea Environment Corporation standards. The company also reduced material costs by more than 19%, achieving significant results in both quality and cost competitiveness.
CEO Kim Jong-woo (Michael Kim) stated, “We are rebuilding the organization to become a quality-focused company trusted by customers. By 2026, we will further enhance our quality-centered competitiveness, and from 2027, we will transition to a stable profit-generating structure.”
Kim JaeHun (rlqm93@fntimes.com)


















