



• 구독신청
  • My스크랩
  • 지면신문
FNTIMES 대한민국 최고 금융 경제지
ad

'Battery Savior' SK Innovation-SK E&S Merger to be finalized on Sunday...Merger Ratio?

곽호룡 기자

horr@fntimes.com

기사입력 : 2024-07-16 19:17 최종수정 : 2024-07-24 11:55

[KOREA FINANCIAL TIMES, Gwak Horyung] SK Group's rebalancing (business portfolio adjustment) program, "Revitalizing SK on," is in full swing. The plan to merge SK innovation and SK E&S, the parent company of SK on, is moving forward.

According to financial reports on the 16th, SK innovation and SK E&S will hold a board meeting on the 17th to discuss the merger.

The key is the merger ratio.
'Battery Savior' SK Innovation-SK E&S Merger to be finalized on Sunday...Merger Ratio?
The Enforcement Decree of the Capital Market Act specifies the merger value calculation method for mergers between listed and unlisted companies. For unlisted companies (SK E&S), the merger price is calculated as the arithmetic average of asset value (1x) + earnings value (1.5x). For listed companies (SK innovation), the ransom price is calculated by averaging the closing prices of the last one day to one month. However, if the reference stock price is lower than the asset value, the merger price can be calculated using the asset value.

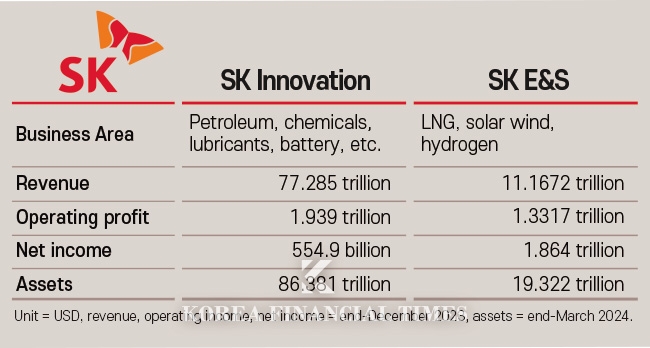
SK E&S is overvalued, while SK innovation is undervalued. Compared to SK E&S, SK Innovation has seven times the sales and assets, but its recent profits are similar. Moreover, SK Innovation's price-to-earnings ratio (PBR) is 0.5x, which is half of the average for KOSPI companies, due to a decline in its stock price due to the sluggish industry.

In conclusion, SK E&S shareholders are favored if the merger ratio is calculated based on stock price, while SK Innovation shareholders are favored if it is evaluated based on asset value under the exception rule.

The industry is expected to discuss the merger ratio based on stock prices. In this case, it is estimated that the merger ratio between SK innovation and SK E&S will be 1:2.

The largest shareholder of both companies is SK Corporation. It owns 36% of SK innovation and 90% of SK E&S. The higher the valuation of SK E&S, the lower the diluted share value after the merger. Convincing private equity firm KKR, which holds redeemable convertible preference shares (RCPS) in SK E&S, is also inevitable. KKR holds 3.1 trillion won worth of SK E&S RCPS. If the merger proceeds by increasing the valuation of SK innovation and KKR opposes the merger, it will have to repay the funds.

However, it is expected to face a backlash from SK innovation's minority shareholders, whose stake value will be diluted. The company is expected to present its future vision through the merger or boost its stock price through a shareholder return policy.
'Battery Savior' SK Innovation-SK E&S Merger to be finalized on Sunday...Merger Ratio?
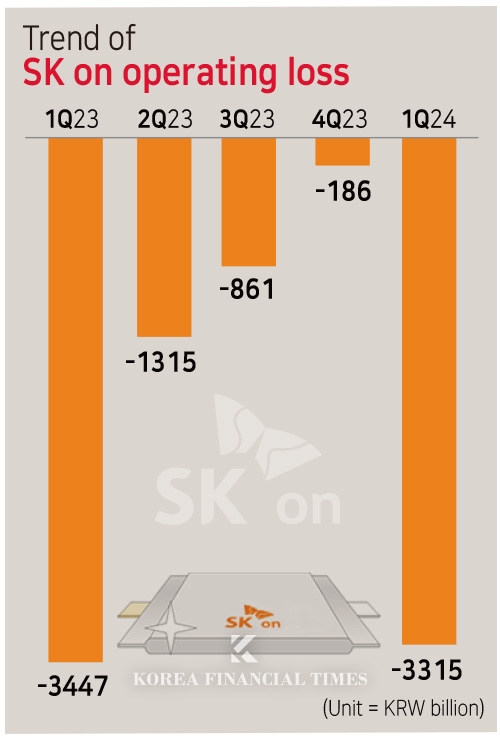
Analysts say the merger is focused on reviving SK Innovation's battery subsidiary, SK on. Since its launch in 2021, the company has lost money for 10 consecutive quarters until the first quarter of this year. A rebound in the electric vehicle industry in the second half of this year is uncertain. SK innovation has been raising trillions of won through capital increase, pre-IPO, and the issuance of subordinated bonds to build new batteries, but its borrowing capacity has reached its limit. The company raised another 500 billion won through a perpetual bond issue at the end of last month.

If SK E&S, a cash-generative company, were to merge with its parent company, SK Innovation, it could provide more support for SK Energy.

Of course, this is not a fundamental solution to SK E&S's funding crisis, so it needs to secure its own profitability. SK innovation had previously proposed a merger of its lubricant subsidiary SK Enmove and SK On, but it was reportedly canceled due to stakeholder opposition. More recently, SK Innovation has also been considering a merger with SK Trading International and SK Enterm.

SK innovation said, "We are reviewing various strategic measures to strengthen the competitiveness of the SK ON business, but no specific decisions have been made."

Gwak Horyung (horr@fntimes.com)

데일리 금융경제뉴스 FNTIMES - 저작권법에 의거 상업적 목적의 무단 전재, 복사, 배포 금지
Copyright ⓒ 한국금융신문 & FNTIMES.com

가장 핫한 경제 소식! 한국금융신문의 ‘추천뉴스’를 받아보세요~

산업 다른 기사

1 LG화학, NCC 재가동에도 석유화학 적자…첨단소재는 회복세 LG화학의 고민은 다시 석유화학이다. 배터리 자회사와 첨단소재의 실적이 개선되는 가운데 상반기 흑자 전환에 성공한 석유화학은 하반기 다시 적자로 돌아설 전망이다. 6개월여간 가동을 멈췄던 여수 나프타분해설비(NCC) 2공장도 재가동에 들어갔지만, 원료 가격 하락에 따른 재고 래깅 효과와 물류비 부담이 겹치면서 수익성 회복은 쉽지 않을 것으로 보인다.16일 금융정보업체 에프앤가이드에 따르면 LG화학의 3분기 연결 기준 매출 컨센서스는 14조7113억원, 영업이익은 2756억원이다. 삼성증권은 지난 12일 보고서에서 매출 15조5620억원, 영업이익 6136억원을 전망했다. 배터리 자회사 LG에너지솔루션의 실적 개선이 연결 기준 이익을 끌어 2 국내 최대 셀 라인 지킨 한화큐셀…'제조부터 전력거래까지' 선순환 그린다 한화솔루션 큐셀부문(한화큐셀)이 중국산 공세 속에서도 지켜온 국내 셀 공장을 발판 삼아 전력거래 사업까지 영역을 넓히고 있다. 국내생산세액공제로 제조 기반을 살리고, 직접 PPA·VPP로 모듈 판매 이후 20년 운영 기간까지 고객을 붙잡겠다는 전략이다.이를 통해 한화솔루션은 전력거래에서 생긴 국산 모듈 수요가 다시 국내 생산을 키우는 선순환을 구상하고 있다.진천공장, 세액공제 도입 시 곧바로 증산한화솔루션은 지난 15일 '2026 솔루션 아카데미'를 열었다. 이 자리에서 유재열 한화솔루션 큐셀부문 한국사업부장(전무)은 '태양광 시대, 한화큐셀이 함께하는 에너지 대전환'을 주제로 국내생산세액공제의 필요성과 한화큐셀 한국 사 3 ‘배그 IP 확장 숨고르기’ 크래프톤 김창한...'데드넷'에 쏠리는 눈 크래프톤이 배틀그라운드(PUBG) 지식재산권(IP)을 활용한 신작 프로젝트를 잇달아 정리하면서 김창한 대표가 추진해 온 PUBG 프랜차이즈 확대 전략이 시험대에 올랐다. 원작 배틀로얄을 넘어 다양한 장르로 IP를 확장하려던 시도가 개발 중단과 서비스 종료로 이어지면서다.이런 가운데 신규 슈팅 게임 ‘PUBG: 데드넷’이 첫 비공개 베타 테스트에서 차별화 가능성을 확인하면서 관심이 쏠린다. 다만 게임 독창성에 대한 긍정적 반응과 함께 전투 밸런스와 완성도에 대한 개선 요구도 나온 만큼, 데드넷이 앞선 프로젝트의 한계를 넘어 PUBG IP 확장의 새로운 성공 사례가 될 수 있을지가 관건이다.배그 IP 기반 ‘데드넷’ 이용자 첫 선 16일 게
ad
ad

한국금융 포럼 사이버관

더보기

FT카드뉴스

더보기
[그래픽 뉴스] ‘순대’가 경제용어라고? 순(純)대외자산, 한국의 진짜 해외자산은 얼마일까?
[그래픽 뉴스] ISA 대개편! 나에게 유리한 계좌는?
[그래픽 뉴스] 미국 증시 새로운 키워드 'MANGOS'
환전·로또·육아휴직까지 하반기부터 달라지는 제도 TOP11
[그래픽 뉴스] 은퇴후 30년 부모님 세대의 생존전략

FT도서

더보기










