





While solid core profitability provides a cushion, further out-licensing of follow-up obesity drugs and a resolution of governance risk are expected to be the main turning points for a revaluation.
Inheritance Tax Sparked the Feud, Now a KRW 60 Billion Lawsuit
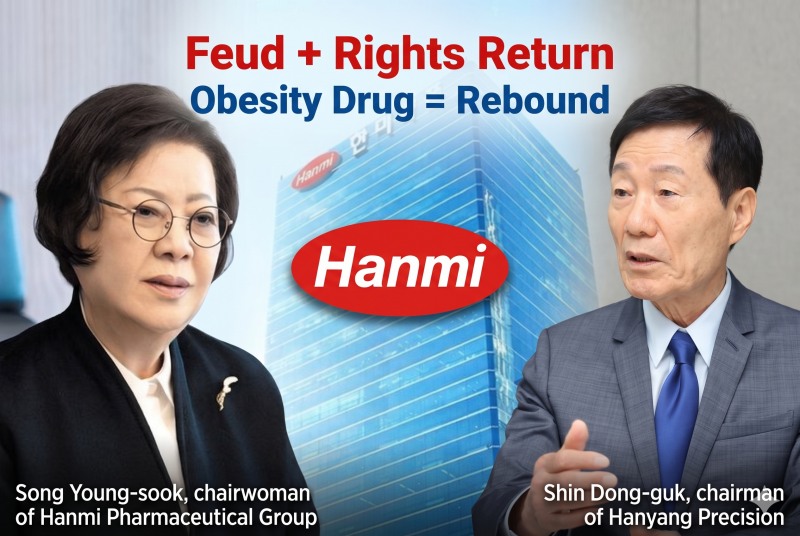
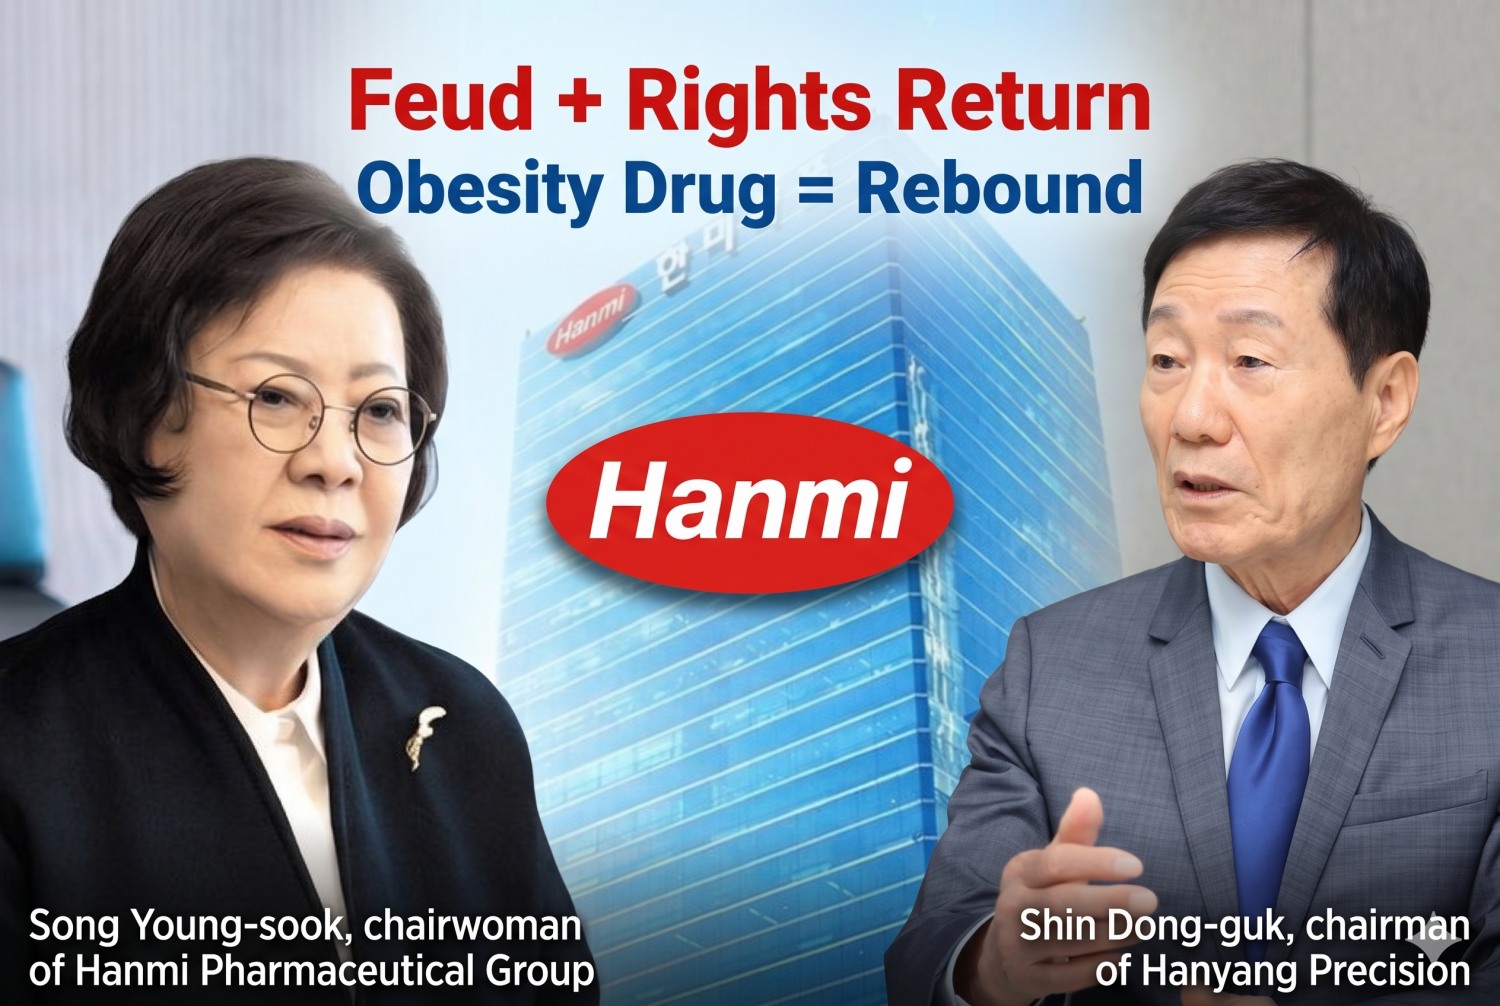
Hanmi Pharmaceutical Group’s operating environment is clouded from every direction, industry sources said on Oct. 18. The governance risk began after the death of founder Lim Sung-ki in August 2020, which left the family with an inheritance tax bill of about KRW 540 billion.As the family’s major shareholders grew divided over how to fund the tax, Chairwoman Song Young-sook and her daughter Lim Ju-hyun, vice chairwoman of Hanmi Science, pushed for a sudden merger with OCI Group in January 2024.
Her sons, Lim Jong-yoon, chairman of COREE Group, and Lim Jong-hoon, CEO of Hanmi Fine Chemical, objected, setting off a full-scale fight for management control.
In March 2024, Shin Dong-guk, chairman of Hanyang Precision, emerged as the key figure and sided with the brothers, scuttling the OCI merger.
The governance picture was soon thrown into turmoil again. In July that year, Chairman Shin bought a 6.5% stake from Song and her daughter and formed a “three-party alliance,” and in December the private equity firm La Defense Partners joined to create a “four-party alliance.”
Last February, brothers Lim Jong-yoon and Lim Jong-hoon stepped back from management, and the family feud appeared to be over for the time being. But internal rifts resurfaced before governance could stabilize.
Dong-A Socio Holdings Absorbs Dong-A Pharmaceutical, Becoming Operating Holding Company to Close Valuation GapSolid Finances, Underwhelming Returns: Yuhan Corporation's Capital Efficiency ChallengeCelltrion Fires on All Cylinders with Profitability and Shareholder Returns, but Stock Price LagsKolmar Group Joins South Korea's Large Business Tier After 36 Years — HK inno.N at the Core
Last June, a conflict among major shareholders over investment in a senior care business escalated into a legal fight. This year, Chairman Shin bought additional shares from Lim Jong-yoon’s side in March and August, redrawing the shareholding map again.
On Oct. 1, Chairman Shin won the first-instance ruling in a lawsuit over a contractual penalty of about KRW 60 billion related to the senior care business. With the dispute between the holding company and its affiliates now becoming a court battle, governance uncertainty looks set to drag on.
“Belvarafenib” Rights Returned, “Record Earnings” Overshadowed by Falling P/E
Beyond governance risk, the company has also struggled in research and development (R&D). Rights to belvarafenib (HM95573), a targeted cancer drug candidate that Hanmi out-licensed to the global drugmaker Genentech in September 2016 in a deal worth up to USD 910 million (about KRW 1.2 trillion), have reverted to Hanmi after roughly 10 years.The contract ended because Genentech revised its global clinical strategy. Even so, the commercialization timeline for a key pipeline asset has been pushed back, and the financial burden of running its own clinical trials is growing, making a pipeline overhaul unavoidable.
The problem is that the string of setbacks is keeping the market from awarding a valuation despite strong earnings.
Hanmi Pharm is posting record results, driven by steady sales growth from its own products, including Rosuzet, a combination drug for dyslipidemia, and Amosartan, a hypertension treatment.
According to financial data provider FnGuide, Hanmi Pharm’s third-quarter sales are estimated to rise 24% from a year earlier to KRW 450.1 billion, and operating profit to jump 96% to KRW 107.9 billion.
For all of 2026, sales are projected to grow 15% from the previous year to KRW 1.7791 trillion, operating profit 52% to KRW 391.9 billion and net profit 62% to KRW 304 billion.
Yet its price-to-earnings ratio (PER) has been heading downward. Hanmi Pharm’s PER, which stood at around 34 times last year, fell to 23 times as of the first half of this year, and the securities industry expects the full-year PER to drop to around 20 times.
PER shows how high a company’s share price is relative to its earnings. In Hanmi Pharm’s case, that means profits are rising while the stock price is falling.
The decline in PER can be read not as simple undervaluation but as the loss of a growth premium. A company’s value is built not only on current earnings but also on high multiples assigned to the value of future drugs and the stability of governance.
In the end, the PER drop shows that even as Hanmi Pharm posts record results in its core business, investors are applying a markdown to future growth because of the owner family’s prolonged fight for control and the return of rights. Governance and R&D uncertainty are outweighing the good news of strong earnings and cancelling out the market premium.
A KRW 5 Trillion Jackpot This Summer... Obesity Drugs Are the Key to a Rebound
The card Hanmi Pharm has put forward to escape the swamp of governance risk and returned pipeline assets and normalize its valuation is major R&D-driven out-licensing success.In the three months from June to August alone, Hanmi Pharm closed two large out-licensing deals with global big pharma companies in succession, worth a combined KRW 5.0865 trillion.
In June, it signed a licensing agreement with Eli Lilly worth USD 1.26 billion (about KRW 1.8973 trillion) for sonefpeglutide, a treatment for short bowel syndrome. In August, it transferred HM17321, an obesity drug candidate aimed at both weight loss and muscle preservation, to Genentech, a subsidiary of Roche, in a deal worth up to USD 2.3 billion (about KRW 3.19 trillion).
The non-refundable upfront payments from the two contracts total KRW 375.8 billion, exceeding the company’s operating profit of KRW 257.8 billion last year. The result is the payoff of Hanmi’s patience in consistently investing 14% to 15% of sales in R&D and running its own obesity drug project, H.O.P (Hanmi Obesity Pipeline).
Separately, EPPE (generic name efpeglenatide), a Korean-developed obesity drug that won approval from the Ministry of Food and Drug Safety as the 45th domestically developed new drug, is set to begin its first supply as early as the end of this month, launching full-scale domestic commercialization.
In the market for glucagon-like peptide-1 (GLP-1) obesity drugs, already led by Novo Nordisk’s Wegovy and Eli Lilly’s Mounjaro, Hanmi plans to prove the prescription competitiveness of a domestic drug. Its strengths are Phase 3 clinical data on Korean patients, supply stability from its Pyeongtaek bio plant, and a sales force that has ranked No. 1 in outpatient prescriptions for eight consecutive years.
Analysts are also looking beyond the already completed KRW 5 trillion-range out-licensing deals to the possibility of further licensing of follow-up obesity pipeline assets.
Representative examples are the triple agonists HM15275 and HM500197, which are in U.S. Phase 2 trials targeting weight loss of 25% or more in severely obese patients.
Hanmi Pharm plans to pursue additional out-licensing around the end of Phase 2 (first half of 2027) to solidify its position in the global obesity drug market.
“Hanmi Pharm is proving its fundamentals through unrivaled sales of its own products despite the double burden of the owners’ feud and the returned pipeline,” said an official in the financial investment industry. “If governance uncertainty is resolved quickly and further out-licensing of follow-up obesity drugs becomes visible, the company’s valuation will be re-rated.”
Jeong Chaeyun (chaeyun@fntimes.com)





















