• 구독신청
  • My스크랩
  • 지면신문
FNTIMES 대한민국 최고 금융 경제지
ad

SK Group Doubles Cash Generation on Semiconductor Gains... Energy Sector Increases Borrowing

곽호룡 기자

horr@fntimes.com

기사입력 : 2025-05-26 10:49

◇ EBITDA Margin Doubles from 12% to 24% in One Year
◇ Chip Rally Led by Hynix Creates Illusion... Energy Sector Slump Deepens

Illustration by ChatGPT

Illustration by ChatGPT

이미지 확대보기
[Korea Financial Times, Gwak Horyung] SK Group’s cash generation capacity has rebounded for the first time in three years, yet Chairman Chey Tae-won remains highly vigilant about the current crisis. From the beginning of the new year, Chairman Chey emphasized, “What we need now is the courage to take action despite knowing the difficulties,” and stressed, “We must strengthen our fundamental competitiveness through operational improvements.” This is because the accounting figures are merely an optical illusion created by the semiconductor business, while the sluggish performance of the energy sector continues.

According to the Korea Ratings data package, SK Group’s consolidated EBITDA margin reached 23.8% in 2024, nearly doubling from 12.3% in 2023 in just one year.

The EBITDA margin is the ratio of EBITDA to sales revenue. While similar to the operating profit margin, it reflects profitability excluding depreciation, interest expenses, and taxes, thus indicating the actual cash-generating capability.
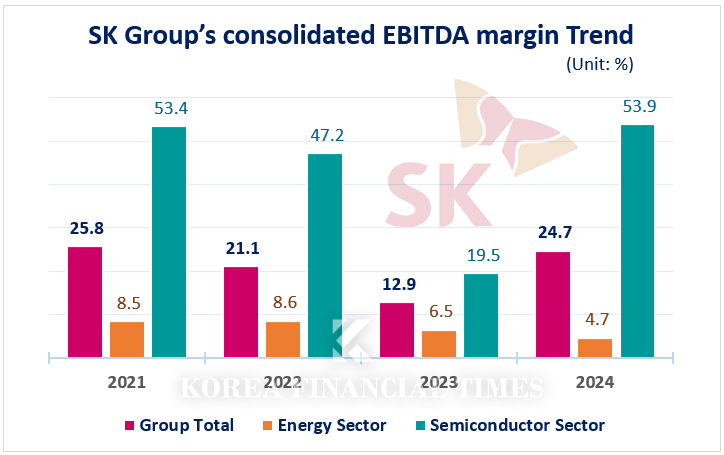
* Energy Sector = SK Innovation, SKC, SK Gas, SK Chemicals, SK Advanced ; * Semiconductor Sector = SK hynix, SK Siltron / Data Source: Korea Investors Service, Inc.(KIS) Data Package

* Energy Sector = SK Innovation, SKC, SK Gas, SK Chemicals, SK Advanced ; * Semiconductor Sector = SK hynix, SK Siltron / Data Source: Korea Investors Service, Inc.(KIS) Data Package

이미지 확대보기

SK Group’s main concern is the pronounced reliance on semiconductors. The EBITDA margin of semiconductor affiliates such as SK hynix and SK siltron surged from 19.5% in 2023 to 53.9% in 2024. In contrast, the EBITDA margin of the energy affiliates, which account for the largest portion of sales, declined from 6.5% to 4.7% over the same period.

SK innovation, which accounts for 81% of sales among SK’s energy affiliates, is experiencing poor performance across all major business segments, including refining, chemicals, and batteries. As a result, even though its cash generation capacity is weakening, it faces a structural burden to continue large-scale investments such as battery facility expansions.

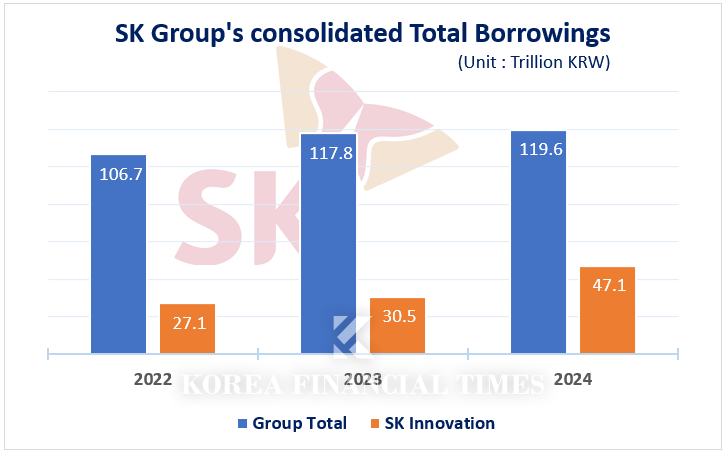
Consequently, dependence on external financing has increased, leading to a vicious cycle of expanding borrowings.

In fact, SK innovation’s consolidated total borrowings surged by approximately 54%, from KRW 30.535 trillion in 2023 to KRW 47.129 trillion in 2024.
The merger of SK innovation with SK E&S, which has strong cash generation capacity, in November last year was also a measure to overcome its financial crisis. Subsequently, in February this year, three SK innovation affiliates—SK on, SK Enterm, and SK International Trading—also underwent mergers. However, with SK on expected to remain in the red this year due to the prolonged EV market downturn, concerns are rising that additional support measures may be necessary.

Data Source: Korea Investors Service, Inc.(KIS) Data Package

Data Source: Korea Investors Service, Inc.(KIS) Data Package

이미지 확대보기


Gwak Horyung (horr@fntimes.com)

데일리 금융경제뉴스 FNTIMES - 저작권법에 의거 상업적 목적의 무단 전재, 복사, 배포 금지
Copyright ⓒ 한국금융신문 & FNTIMES.com

가장 핫한 경제 소식! 한국금융신문의 ‘추천뉴스’를 받아보세요~

KFT Topic 다른 기사

1 SK On Builds Non-Chinese LFP Supply Chain With POSCO Future M, L&F SK On is stepping up efforts to build a supply chain free of Chinese dependence for cathode materials, the core component of lithium iron phosphate (LFP) batteries. It is partnering with leading Korean battery materials makers, including POSCO Future M and L&F. The company's strategy is to significantly strengthen its price and technological competitiveness in the energy storage system (ESS) market by securing high-quality Korean-made materials ahead of competitors.This move to strengthen its domestic supply chain is expected to give SK On a major competitive advantage in the race for lead 2 Doosan Doubles Down on Troubled HyAxiom, Eyes Nasdaq Listing Amid AI Power Boom Doosan Corp. is moving to rescue its US subsidiary HyAxiom, which has been in capital impairment since 2022, transforming the loss-making unit into its fuel cell hub in the United States.Doosan has continued to inject capital into HyAxiom through payment guarantees and convertible preferred share issuances, with an eye toward stabilizing its finances enough to pursue a Nasdaq listing.KRW 823.6 Billion in Orders Within Two WeeksDoosan Fuel Cell disclosed on Sept. 15 that it had signed an additional supply contract worth KRW 322.2 billion for phosphoric acid fuel cells (PAFC).The deal follows a 3 Beyond Samsung and SK hynix: Jusung Engineering Leads Korean Chip Stocks with 610% Return Among semiconductor stocks other than Samsung Electronics and SK hynix, Jusung Engineering posted the highest shareholder return over the past three years. Expanded investment in artificial intelligence (AI) chips lifted share prices across the board. The drivers differed by company, depending on business area, including memory, back-end processing and foundry.Korea Financial Times used the corporate data platform DeepSearch to calculate cumulative total shareholder return (TSR) for semiconductor and chip equipment companies from Jan. 2, 2024, to Sept. 16, 2026. Excluding Samsung Electronics,
ad
ad

한국금융 포럼 사이버관

더보기

FT카드뉴스

더보기
[그래픽 뉴스] ‘순대’가 경제용어라고? 순(純)대외자산, 한국의 진짜 해외자산은 얼마일까?
[그래픽 뉴스] ISA 대개편! 나에게 유리한 계좌는?
[그래픽 뉴스] 미국 증시 새로운 키워드 'MANGOS'
환전·로또·육아휴직까지 하반기부터 달라지는 제도 TOP11
[그래픽 뉴스] 은퇴후 30년 부모님 세대의 생존전략

FT도서

더보기