






SK Hynix held an earnings presentation on the 24th and announced that it recorded KRW 17.57 trillion in sales, KRW 7.03 trillion in operating profit (40% operating profit ratio), and KRW 5.75 trillion in net profit (33% net profit ratio) in the 3rd quarter of this year. This was the biggest quarterly performance ever, with revenue surpassing the previous record of KRW 16.42 trillion in the 2nd quarter of this year by more than KRW 1 trillion, and its operating profit and net profit also exceeded the record of KRW 6.47 trillion and KRW 4.69 trillion in the 3rd quarter of 2018, when the semiconductor super boom was held.
In particular, operating profit is expected to exceed the operating profit of Samsung Electronics' DS division in the third quarter. Samsung Electronics' operating profit in the third quarter is KRW 9.1 trillion. This is a provisional performance announced by Samsung Electronics on the 8th, and the business-specific performance will be disclosed on the 31st. According to the industry, operating profit of the DS division is estimated to be around KRW 4 to KRW 5 trillion.
SK Hynix's achievement is attributable to its competitive advantage in AI-flavored D-RAM memory semiconductor HBM. Currently, SK Hynix is leading the industry with a global HBM share of more than 40%
SK Hynix CFO (Vice President) Kim Woo-hyun said in a conference call held after the third quarter's earnings announcement, "The demand for AI memories continued to be strong, focusing on data center customers, and the company expanded sales of high value-added products such as HBM and eSSD, achieving its largest sales since its foundation." "In particular, HBM sales increased by more than 70% compared to the previous quarter and more than 330% compared to the same period last year."
He added, "We have solidified our position as the world's No. 1 AI memory company by achieving the largest-ever management performance in the third quarter of this year."
SK Hynix predicted that this trend will continue next year amid clear growth in memory demand for AI servers such as HBM and eSSD this year. This is because Generative AI is developing into a multimodal form and global big tech companies continue to invest in developing general-purpose artificial intelligence (AGI).
In addition, the PC and mobile product markets, which have been slow to recover demand compared to AI server memory, are expected to balance supply and demand from next year as AI memory optimized for each device is released.
SK Hynix's Strong Challenge... Can Samsung Electronics Maintain 'Super Gap' in NAND Flash?6th Generation HBM Competition... Samsung Electronics 'All-in-One' vs SK Hynix 'Super Gap'"Crisis Surrounding Samsung... Will Lee Jae-yong Return as a Registered Director in His Second Year as Chairman?"'Special from the name' Samsung Electronics aims to take the top spot in foldables with 'Galaxy Z Fold SE''Memory boom' Samsung Electronics, when will foundry and system LSI recover?
SK Hynix will continue to focus on profitability by increasing sales centered on high value-added products based on its world-leading technology in AI memory.
First of all, the DRAM division is continuing the rapid transition from the existing HBM3 to the HBM3E 8-layer product, and the supply of the HBM3E 12-layer product, which started mass production last month, will start in the fourth quarter as scheduled. Through this, the share of HBM sales, which accounted for 30% of total DRAM sales in the 3rd quarter, will increase to 40% in the 4th quarter.
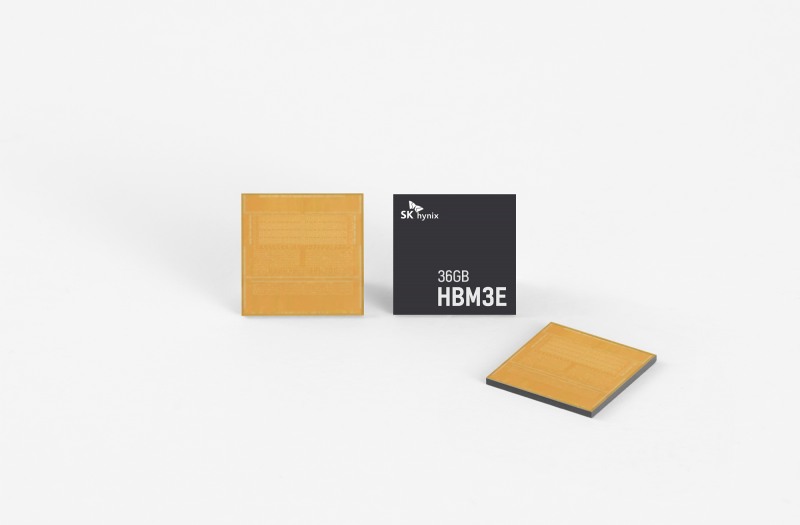

Vice President Kim Woo-hyun said, "HBM3E shipments exceeded HBM3 in the third quarter, and HBM3E 12-layer products will start shipping as scheduled in the 4th quarter, and the proportion of 12-layer products will account for more than half of the total HBM3E shipments in the first half of next year," adding, "Based on the competitiveness of AI-related products, we will continue to use strategies to respond flexibly to market demand."
SK Hynix recently drew a line on the prospect of slowing demand due to oversupply of HBMs mentioned in the industry. He stressed that AI business expansion and diversification are still underway and that all product supply contracts have been completed.
"It is too early to talk about slowing demand for HBM at this point," said Kim Kyu-hyun, head of SK Hynix's DRAM. "On the contrary, it is not easy for the memory industry to supply enough quality that customers want in a timely manner as the technology difficulty of developing new HBM products is gradually increasing. Contrary to some concerns in the industry, HBM demand for AI continues to exceed expectations and additional supply requests are continuing."
"Unlike general D-RAM, HBM has a long-term contract structure," he said. "Since most of the price consultations with customers in 2025 are completed, the visibility is very high in terms of demand."
Furthermore, SK Hynix plans to expand its investment to increase production. In particular, the company plans to expand production mainly to product lines where demand is certain, instead of reducing products whose demand is slowing. It also plans to expand sales of high-capacity eSSDs, which are rapidly increasing in market demand, while focusing on investment efficiency and production optimization in NAND.
Vice President Kim Woo-hyun said, "With M15X fab and Yongin cluster 1 fab investment, which are preparing for future growth, infrastructure investment is expected to increase next year from this year," adding, "However, we expect that the M15X, which will be completed first, will contribute to DRAM production in 2026, and we plan to flexibly adjust the mass production time and size of new fabs to meet the demand environment."
"Instead of reducing DDR4/LPDDR4, which is slowing demand this year, we will accelerate the transition of the front-end process needed to expand the production of HBM and DDR5/LPDDR5," he said. "We plan to focus on investments to convert to fleet processes to stably supply products such as HBM, DDR5/LPDDR5, and eSSD next year."
In addition, Vice President Kim Woo-hyun said, "Considering the HBM and M15X fabs, this year's investment will be in the mid-to-late 10 trillion won range, higher than at the beginning of the year," adding, "Although next year's facility investment plan has not been finalized, it will increase slightly from this year considering fan expansion."
Kim JaeHun (rlqm93@fntimes.com)




















