





According to THE COMPASS, an artificial intelligence (AI) platform built in-house by the Korea Financial Times, some common characteristics have been confirmed among companies that become targets of activist funds, the outlet reported on the 30th.
These companies post a return on invested capital (ROIC) lower than their return on equity (ROE), while their price-to-book ratio (PBR) stands at 1x or below. A total of 668 domestic listed companies meet these conditions.
Ranked by market capitalization, Hyundai Motor, Kia, and Hyundai Mobis are representative examples. The so-called "Hyundai Motor Group trio" saw its group governance restructuring plan collapse in the past after Elliott Management intervened. More recently, the Korea Corporate Governance Forum has also criticized Hyundai Motor over inefficient capital allocation and called for improvement.
Other companies that have become activist targets — including holding companies LG and Hanwha, as well as KT, Korean Air, Youngone, KCC, and Kumho Petrochemical — were likewise found to have notably inefficient capital allocation structures.
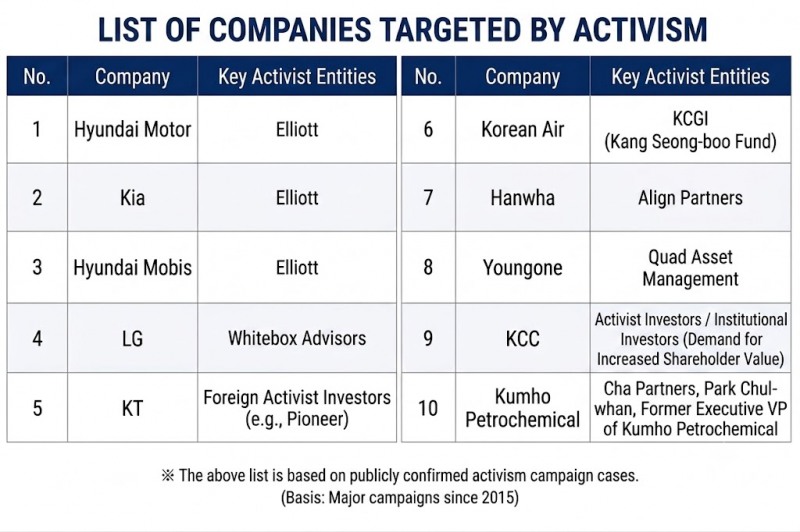
Companies with ROIC Below ROE and PBR Under 1x (Market Cap of KRW 3 trillion or More) / Image Generated Using AI
이미지 확대보기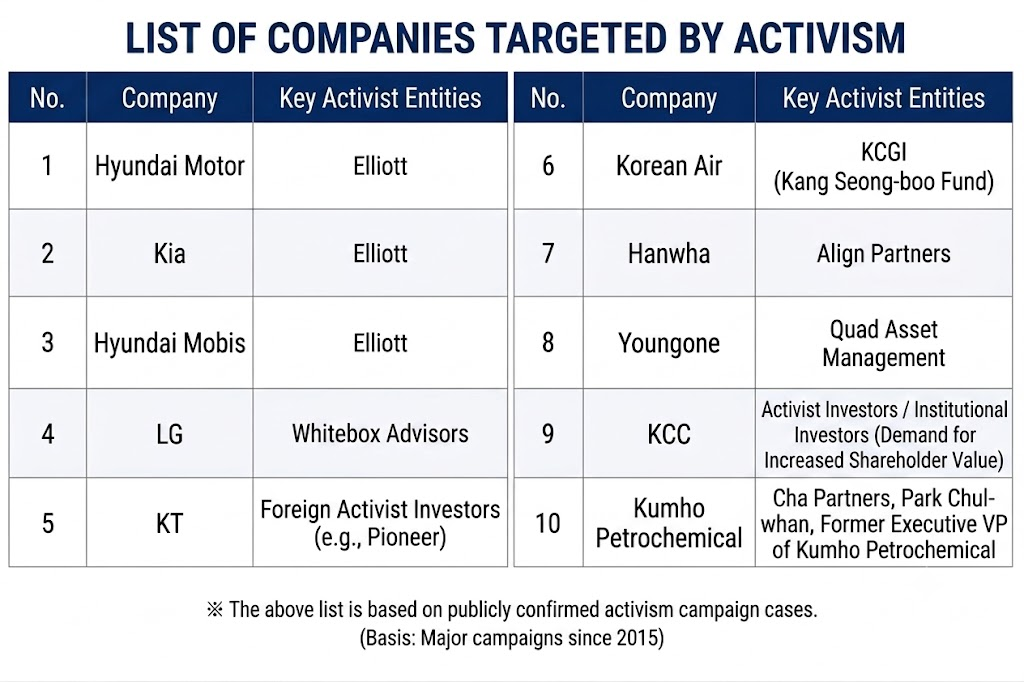
What Lies Behind ROIC Falling Below ROE, and the Role of PBR
ROIC shows how much a company earns from the capital invested in its operating assets. A low ROIC indicates weak efficiency in the core business or operating assets.In some cases, ROE appears relatively higher than ROIC. The first scenario involves reliance on leverage through debt. The second occurs when non-operating income — such as real estate or securities holdings unrelated to the core business — makes up a large share of earnings.
That said, activist pressure tends to ease somewhat when PBR is high. Even if ROIC falls below ROE, a high PBR makes it harder to justify shareholder value campaigns on the basis of "undervaluation."
However, a company can still become an activist target if it shows a high dual-listing discount ratio. Garena — Gabia is a representative case. [Note: see translation note below] Gabia's PBR stood at around 2.5x before its tender offer. Yet its ROIC failed to exceed its ROE, and its dual-listing discount ratio came to 21.1%, above the domestic average of 15.5%.
Revised Commercial Act's '3% Rule' Raises Concerns Over Expanding Activist Targets
Under the revised Commercial Act, which took effect on the 23rd, the voting rights of the largest shareholder and related parties are capped at 3% when electing or dismissing outside directors who serve on the audit committee. This dramatically improves the odds for activist funds or coalitions of minority shareholders when they nominate their own audit committee candidates against management and contest the vote.For companies and management, simply securing voting rights is no longer enough to maintain control, unlike in the past. Among the 668 companies mentioned above, 26 were found vulnerable due to weak controlling-shareholder stakes or complex governance structures.
But under the revised law, even companies with strong controlling-shareholder power can no longer rest easy. Factoring in companies with high dual-listing discount ratios as well, defending management control is expected to become far more difficult.
Still, the basic precondition for capital markets is generating returns that exceed invested capital. Companies must seek growth by disposing of idle assets, while also raising asset efficiency through share buybacks and cancellations, and expanded dividends.
An investment banking (IB) industry source said, "Activist funds have focused on companies with weak controlling-shareholder power and visibly inefficient capital allocation," adding that "the revised Commercial Act will broaden and strengthen their activity." The source stressed that "since a company is a profit-seeking entity that must raise asset efficiency, companies should focus on enhancing corporate value rather than on defending against activist funds."
Lee Sungkyu (lsk0603@fntimes.com)





















