






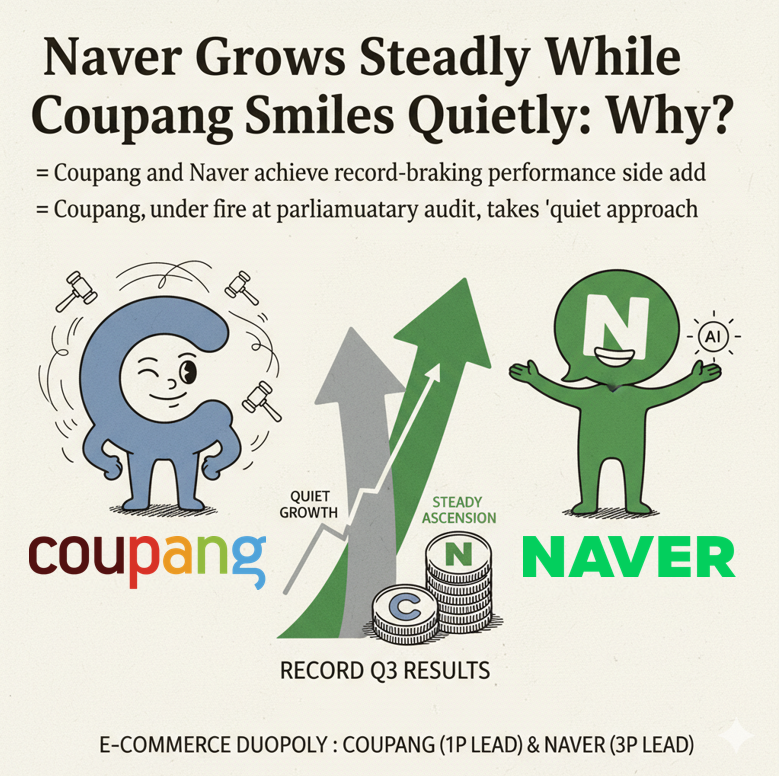
While Coupang, which faced concentrated fire over various issues at this year's parliamentary audit, chose a "quiet approach" over an "earnings celebration," Naver is increasingly expanding its presence in the retail industry by highlighting its commerce business that grew significantly based on artificial intelligence (AI).
According to the industry on November 17, Coupang recorded consolidated revenue of KRW 12.8455 trillion (USD 9.27 billion at an average quarterly exchange rate of KRW 1,386.16) in Q3 2025. This represents a 20% increase compared to the same period in 2024. During this period, operating profit increased 51.5% to KRW 224.5 billion (USD 162 million), and net profit rose 51% to KRW 131.6 billion (USD 95 million).
During the same period, Naver's consolidated revenue increased 15.6% from Q3 2024 to KRW 3.1381 trillion. Within this, Naver commerce revenue grew 35.9% year-over-year to KRW 985.5 billion, accounting for 31% of total revenue. This represents a 4 percentage point expansion from Q3 2024 (27%), establishing itself as a business division driving the group's overall growth.
The fortress of these two giants is already solid. Coupang is the overwhelming number one in the direct purchase (1P) market, while Naver is the number one player in the open market (3P) sector. According to National Data Office statistics, Coupang held 22.7% and Naver held 20.7% of the domestic e-commerce market share in 2024.
The two companies share nearly half of the domestic market. In terms of gross merchandise value (GMV), both companies exceed KRW 50 trillion, dividing the market between them. According to Wiseapp Retail, Coupang's GMV in 2024 was KRW 55.0861 trillion, while Naver's was KRW 50.3 trillion.
However, despite the "record-breaking performance" title, Coupang cannot simply smile. As the e-commerce leader, it has often been beaten like "the nail that sticks out gets hammered down." Concentrated fire continued at this year's parliamentary audit as well.
At the parliamentary audit, negative issues emerged daily, including allegations of pressuring an incumbent prosecutor, excessively long settlement cycles, controversies over high intermediary fees and forced advertising, and labor environment problems. Given the symbolism of being the industry's number one, the company is keeping a low profile despite strong performance, receiving greater attention.
Kim Bom-Suk’s ‘Korean-Style WOW Strategy’ Works: Coupang Achieves Record Quarterly Results with Rapid Global GrowthNaver Cloud, “Inference AI is Essential to Sovereign Strategy… Launch Set for First Half of This Year”'Retail Giant' Coupang Takes the Crown in Parcel Delivery, Overtaking CJ LogisticsIs Coupang's 41-Trillion-Won Empire in Danger? The Advance of Naver and DaisoNaver Focuses on 'AI Enhancement,' Kakao on 'Stabilization'... Contrasting Atmospheres in Board Restructuring
Perhaps understanding Coupang's sentiment, Bloomberg recently published an article titled "Coupang Sets Sales Record but Posts Disappointing Profit." The background is that although Coupang recorded an operating profit of KRW 224.5 billion in Q3 2025, up 51.5% from the same period in 2024, it fell short of Wall Street analyst expectations (approximately KRW 291.3 billion).
Bloomberg analyzed that "Coupang is in fierce competition with other e-commerce companies including AliExpress, Temu, and Naver."
While Coupang fell short of market expectations, it clearly achieved outstanding results across the entire domestic retail industry. This contrasts with competitors like SSG.com and Lotte ON, which are still focused on improving profitability and struggling to reduce their deficits.
Shinsegae Group's SSG.com and Gmarket posted poor results again in Q3. SSG.com's revenue decreased 18.3% year-over-year to KRW 318.9 billion, with operating losses increasing by KRW 25.7 billion to KRW 42.2 billion. Gmarket also saw revenue decline 17.1% to KRW 187.1 billion, with operating losses expanding by KRW 6.4 billion to reach KRW 24.4 billion. Lotte Shopping's Lotte ON saw revenue and operating losses decrease 16.0% and 50% to KRW 22.6 billion and KRW 9.6 billion, respectively.
C-commerce platforms (AliExpress, Temu) targeting the Korean market are also experiencing slowing growth due to limitations in product reliability and delivery quality, while mid-sized platforms like WeMakePrice (bankrupt) and TMON (reopening delayed) are threatened with survival itself.
Ultimately, as Bloomberg pointed out, it is becoming clear that Naver is Coupang's real competitor. Bloomberg noted that "Naver, Korea's mainstream portal, is competing with Coupang based on its massive existing user base and comprehensive user data," and that "it has launched the shopping-dedicated platform Naver Plus Store to take market share from Coupang." The publication added that "Naver is expanding its business into fresh food through partnerships with popular platform Kurly, while making massive investments in logistics."
Naver recently announced that its largest annual online shopping event, "Nepda Sale" (a rebranded version of its previous Naver Shopping Festa), surpassed KRW 1 trillion in cumulative sales over two weeks. This represents an average daily sales of KRW 77.2 billion. Naver attributed the success to various events ranging from exclusive products to lowest-price items, delivery competitiveness, and generous discounts and rewards.
Naver's presence is expected to grow further. This is because Naver, the number one open market operator, will reportedly be included in the government's retail statistics survey subjects starting next year. If actually included, this will be the first time Naver is classified as a retail company in official government statistics.
An industry official said, "The duopoly system of Coupang and Naver has become solid enough that it won't be broken in the short term," adding, "However, while Coupang focuses on logistics and infrastructure, Naver is advancing commerce centered on AI and data, so the two companies' growth directions are gradually diverging." The official continued, "Ultimately, which company secures higher efficiency and customer loyalty will be the key variable determining future market share."
Park seulgi (seulgi@fntimes.com)


















