





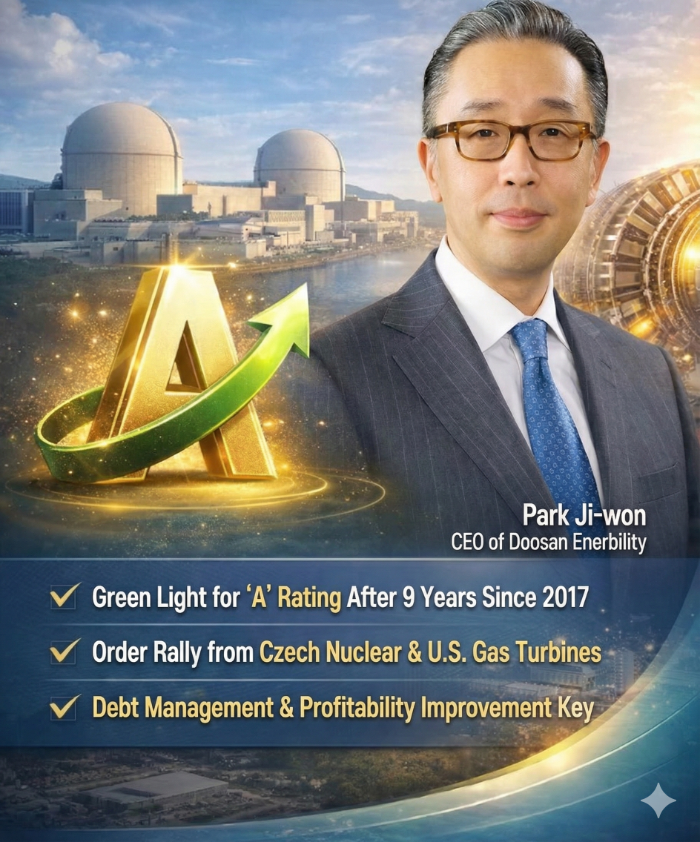
Korea Ratings and NICE Credit Rating recently upgraded Doosan Enerbility's corporate bond credit rating outlook from 'BBB+/Stable' to 'BBB+/Positive.' This indicates a high probability that the credit rating itself will improve within the next one to two years.
Doosan Enerbility lost its A rating in 2017. At that time, NICE Credit Rating and Korea Ratings successively downgraded the company from 'A-/Negative' due to the government's nuclear phase-out and coal phase-out policies, along with increased borrowings.
However, the atmosphere has reversed this year. Cumulative sales for the third quarter reached KRW 5.0252 trillion, a 15.9% increase compared to the same period last year. The Saudi Rumah and Nairyah combined-cycle power plant projects alone generated KRW 1.1343 trillion in sales, driving performance.
This month alone, the company secured a KRW 5.6 trillion contract to supply main equipment and turbine-generators for the Czech Dukovany nuclear power plant. In October and December, the company signed contracts to directly export five large gas turbines (GT) to U.S. big tech companies. Accordingly, the order backlog is expected to reach KRW 20 trillion at the end of December, up from KRW 14.9427 trillion at the end of September.
While net debt increased 19.5% year-over-year to KRW 4.3 trillion as of the end of September due to large-scale project execution, the company is also making efforts to improve its financial structure. It recently secured approximately KRW 330 billion to KRW 370 billion in cash through the sale of its Vietnamese subsidiary, Doosan Vina.
The company is also making investments to respond to increased small modular reactor (SMR) orders stemming from growing global data center demand. From March next year through 2031, it will invest KRW 806.9 billion at its Changwon plant site to construct a dedicated SMR factory and build innovative manufacturing facilities. Additionally, the company plans to invest KRW 300 billion from next year through 2028 to expand GT production capacity.
Korea Ratings cited maintaining an EBITDA margin of 8% or higher and a borrowings-to-assets ratio of 27.5% or lower as conditions for upgrading to an A rating. The EBITDA margin represents cash generation capability, while the borrowings-to-assets ratio indicates the proportion of interest-bearing debt to total assets. As of the end of September, the borrowings-to-assets ratio stood at 31.9%, up 3.4 percentage points (p) year-over-year.
Doosan's Park Jeong-won Makes Bold Moves for the Future Ahead of 130th AnniversaryDoosan Enerbility Gains Traction in Global Gas Turbine Market with Fast Delivery EdgeDoosan Enerbility: "Operating Cash Flow Negative KRW 947.5 Billion in H1," Czech Nuclear Project Becomes a Source of ConcernHD Hyundai Raises KRW 150 Billion… How Much Synergy Will the Merger of Construction Equipment · InfraCore Bring?
NICE Credit Rating ordered the company to maintain an operating profit margin of 6% or higher while lowering the 'net debt/EBITDA' ratio to below 5 times. The 'net debt/EBITDA' ratio indicates how many years it would take to pay off all debt with earnings. As of the end of September, the operating profit margin was 5.4%, and the 'net debt/EBITDA' ratio was 8.4 times.
Lee Min-jae, a researcher at NH Investment & Securities, explained, "There have been several successful project orders in December alone. We expected KRW 4 trillion for the large nuclear main equipment order amount, but the contract was completed at a level far exceeding that."
He forecasted, "Large-scale nuclear power plant projects to be ordered from the United States, Europe, and the Middle East starting next year will also be contracted at similar scales. With cooperation between Korea and the U.S. in the nuclear sector, large-scale nuclear power orders including the U.S. will begin in earnest from next year."
Shin Haeju (hjs0509@fntimes.com)


















