



• 구독신청
  • My스크랩
  • 지면신문
FNTIMES 대한민국 최고 금융 경제지
ad

'Battery Savior' SK Innovation-SK E&S Merger to be finalized on Sunday...Merger Ratio?

곽호룡 기자

horr@fntimes.com

기사입력 : 2024-07-16 19:17 최종수정 : 2024-07-24 11:55

[KOREA FINANCIAL TIMES, Gwak Horyung] SK Group's rebalancing (business portfolio adjustment) program, "Revitalizing SK on," is in full swing. The plan to merge SK innovation and SK E&S, the parent company of SK on, is moving forward.

According to financial reports on the 16th, SK innovation and SK E&S will hold a board meeting on the 17th to discuss the merger.

The key is the merger ratio.
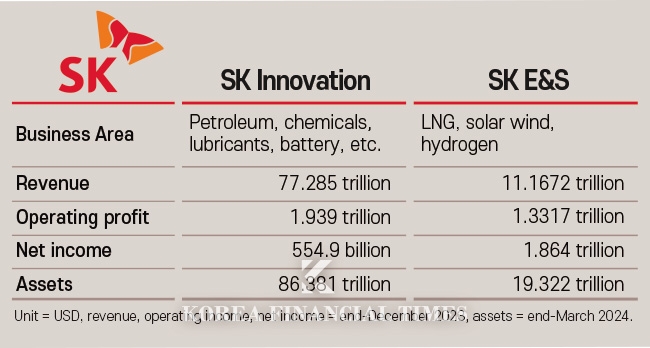
'Battery Savior' SK Innovation-SK E&S Merger to be finalized on Sunday...Merger Ratio?
The Enforcement Decree of the Capital Market Act specifies the merger value calculation method for mergers between listed and unlisted companies. For unlisted companies (SK E&S), the merger price is calculated as the arithmetic average of asset value (1x) + earnings value (1.5x). For listed companies (SK innovation), the ransom price is calculated by averaging the closing prices of the last one day to one month. However, if the reference stock price is lower than the asset value, the merger price can be calculated using the asset value.

SK E&S is overvalued, while SK innovation is undervalued. Compared to SK E&S, SK Innovation has seven times the sales and assets, but its recent profits are similar. Moreover, SK Innovation's price-to-earnings ratio (PBR) is 0.5x, which is half of the average for KOSPI companies, due to a decline in its stock price due to the sluggish industry.

In conclusion, SK E&S shareholders are favored if the merger ratio is calculated based on stock price, while SK Innovation shareholders are favored if it is evaluated based on asset value under the exception rule.

The industry is expected to discuss the merger ratio based on stock prices. In this case, it is estimated that the merger ratio between SK innovation and SK E&S will be 1:2.

The largest shareholder of both companies is SK Corporation. It owns 36% of SK innovation and 90% of SK E&S. The higher the valuation of SK E&S, the lower the diluted share value after the merger. Convincing private equity firm KKR, which holds redeemable convertible preference shares (RCPS) in SK E&S, is also inevitable. KKR holds 3.1 trillion won worth of SK E&S RCPS. If the merger proceeds by increasing the valuation of SK innovation and KKR opposes the merger, it will have to repay the funds.

However, it is expected to face a backlash from SK innovation's minority shareholders, whose stake value will be diluted. The company is expected to present its future vision through the merger or boost its stock price through a shareholder return policy.
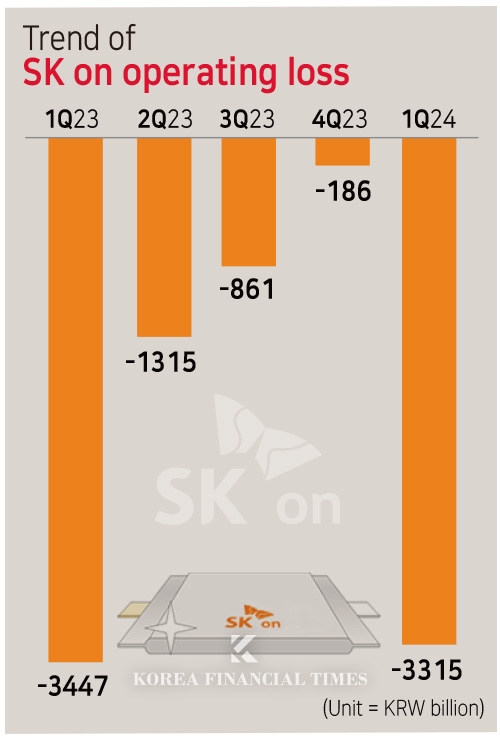
'Battery Savior' SK Innovation-SK E&S Merger to be finalized on Sunday...Merger Ratio?
Analysts say the merger is focused on reviving SK Innovation's battery subsidiary, SK on. Since its launch in 2021, the company has lost money for 10 consecutive quarters until the first quarter of this year. A rebound in the electric vehicle industry in the second half of this year is uncertain. SK innovation has been raising trillions of won through capital increase, pre-IPO, and the issuance of subordinated bonds to build new batteries, but its borrowing capacity has reached its limit. The company raised another 500 billion won through a perpetual bond issue at the end of last month.

If SK E&S, a cash-generative company, were to merge with its parent company, SK Innovation, it could provide more support for SK Energy.

Of course, this is not a fundamental solution to SK E&S's funding crisis, so it needs to secure its own profitability. SK innovation had previously proposed a merger of its lubricant subsidiary SK Enmove and SK On, but it was reportedly canceled due to stakeholder opposition. More recently, SK Innovation has also been considering a merger with SK Trading International and SK Enterm.

SK innovation said, "We are reviewing various strategic measures to strengthen the competitiveness of the SK ON business, but no specific decisions have been made."

Gwak Horyung (horr@fntimes.com)

데일리 금융경제뉴스 FNTIMES - 저작권법에 의거 상업적 목적의 무단 전재, 복사, 배포 금지
Copyright ⓒ 한국금융신문 & FNTIMES.com

가장 핫한 경제 소식! 한국금융신문의 ‘추천뉴스’를 받아보세요~

산업 다른 기사

1 금호석화, 예상 깬 3분기 적자…주력 합성고무 이익 급감 금호석유화학이 올해 3분기 적자로 돌아섰다. 2분기 3390억 원에 달했던 영업이익이 한 분기 만에 208억 원 영업손실로 전환했다. 주력 사업인 합성고무의 수익성이 급격히 악화된 데다 페놀유도체와 합성수지도 적자를 기록하면서 실적을 끌어내렸다. 주요 원료와 제품의 고원가 재고가 실적에 반영된 역래깅이 가장 큰 부담으로 작용한 것으로 풀이된다.금호석유화학은 연결 기준 올해 3분기 매출 1조9215억 원, 영업손실 208억 원을 기록했다고 6일 밝혔다. 매출은 전년 동기 대비 16.9% 증가했지만 영업이익은 지난해 3분기 845억 원에서 적자로 전환했다. 전 분기와 비교하면 매출은 15.3% 줄었고 영업이익은 3598억 원 감소했다. 당기순손실 2 차입금 1.6조 물려받은 동국제강 권주혁…차입 관리·주주환원 ‘저울질’ [나는 CFO다] 권주혁 동국제강 재경실장(CFO)이 취임 첫 반기 영업활동현금흐름을 차입금 상환과 현금 확보에 우선 투입했다. 사옥 재매입과 운전자금 조달이 겹치며 1년 새 76% 넘게 불어난 차입금을 물려받은 상황에서 자금 관리에 나선 것이다.동국제강은 인적분할 이후 공모 회사채 없이 금융기관 차입에 기대 자금을 조달해 왔다. 지난 6월 말 기준 총차입금 1조6689억 원 가운데 1년 안에 만기가 돌아오는 유동성 차입금이 약 70%에 달한다. 여기에 2027년까지 지켜야 할 최저 배당 약속도 걸려 있다. 권 실장으로서는 빚을 관리하면서 주주와의 약속도 지켜야 하는 셈이다.지주사 재경팀장에서 핵심 계열사 재무 수장으로1970년생인 권주혁 실장은 동국 3 LS, 금속 밸류체인 구축·자금 마련 '두 마리 토끼' 잡는다…LS글로벌, LS메탈 사업 인수 LS그룹이 계열사 사업을 재배치해 금속 밸류체인 구축과 투자 자금 마련을 동시에 노린다. 원자재를 사고팔던 LS글로벌에 가공 사업을 붙여 조달부터 가공·판매까지 한 회사가 맡는 구조를 만들고, 사업을 내놓은 LS메탈 모회사 LS일렉트릭은 그 대금을 전력 투자에 돌리겠다는 구상이다.이에 더해 지주사 LS가 LS글로벌 증자에 참여하며 계열사 간 사업 이동을 뒷받침했다. 증자 금액과 LS글로벌이 치를 사업 인수대금은 비슷한 규모다.다만 사업 양도대금은 자회사 LS메탈로 들어가는 만큼, LS일렉트릭이 이를 투자에 활용하려면 자금을 모회사로 옮기는 별도 절차가 필요하다.LS글로벌, 1504억에 사업 양수…LS, 1501억 원 증자 '뒷받침'6일
ad
ad
ad

한국금융 포럼 사이버관

더보기

FT카드뉴스

더보기
[그래픽 뉴스] ‘순대’가 경제용어라고? 순(純)대외자산, 한국의 진짜 해외자산은 얼마일까?
[그래픽 뉴스] ISA 대개편! 나에게 유리한 계좌는?
[그래픽 뉴스] 미국 증시 새로운 키워드 'MANGOS'
환전·로또·육아휴직까지 하반기부터 달라지는 제도 TOP11
[그래픽 뉴스] 은퇴후 30년 부모님 세대의 생존전략

FT도서

더보기











