





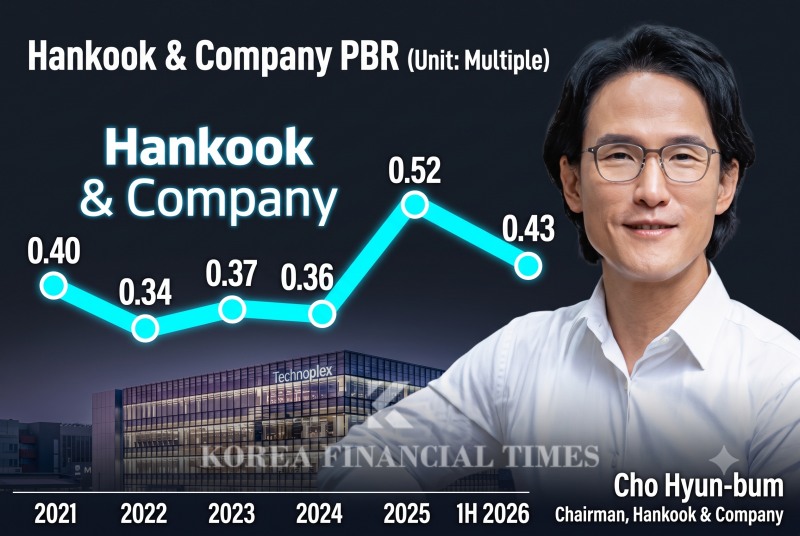
This infographic, originally published by Korea Financial Times, has been reconstructed using generative AI.
이미지 확대보기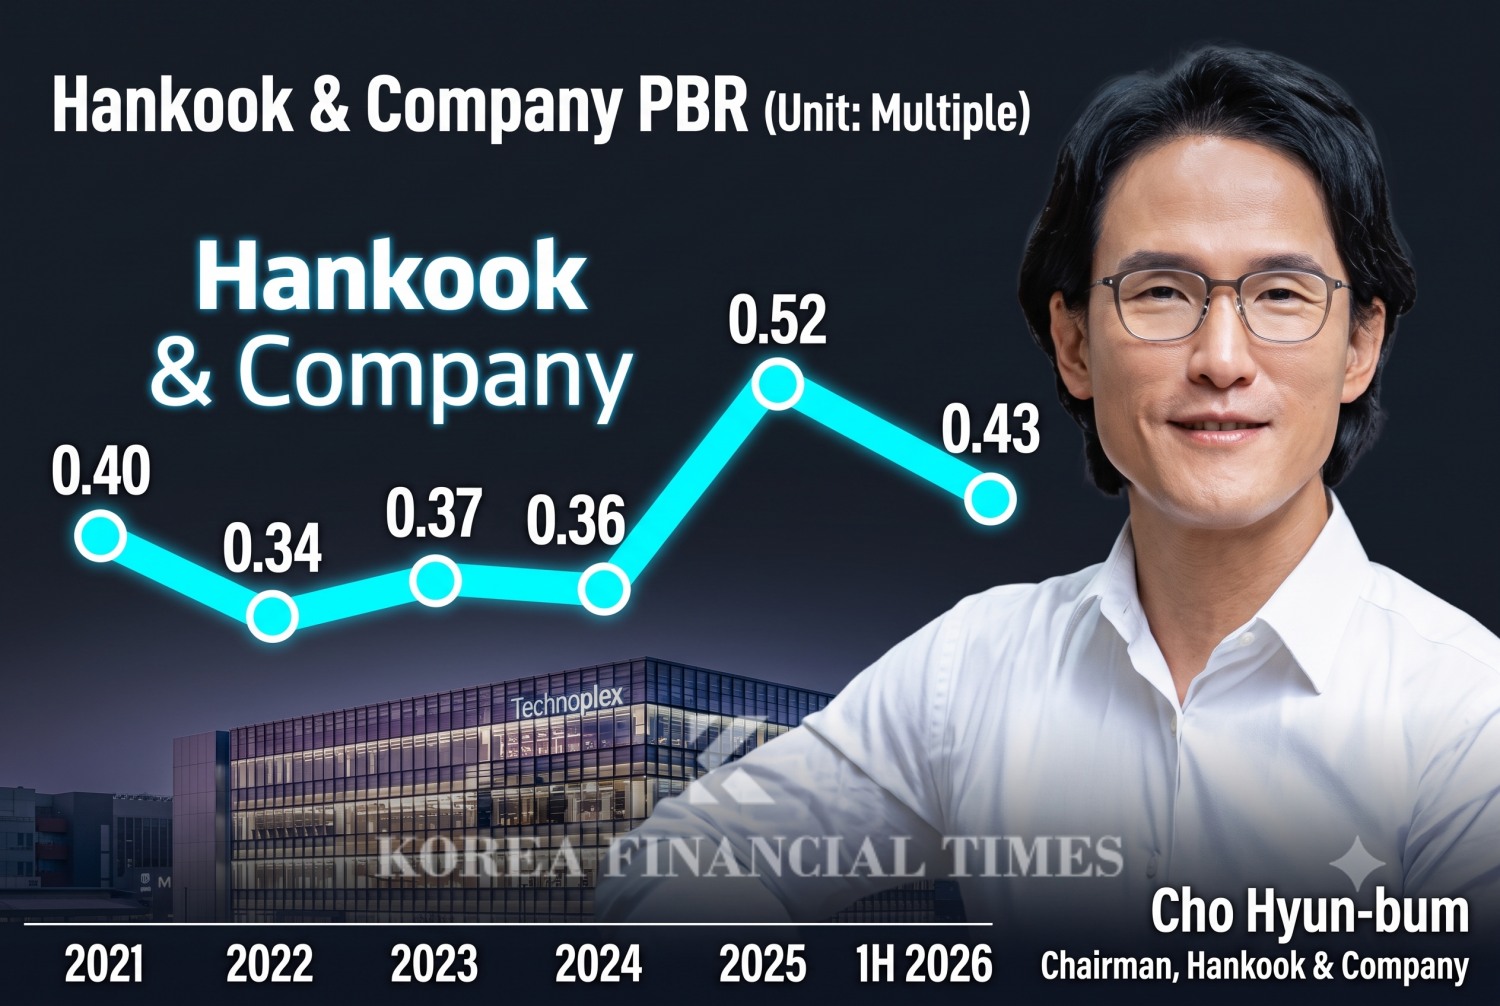
Analysts say this stems from a combination of factors — the structural holding-company discount, disputes within the founding family, and low capital efficiency — despite the solid cash flow provided by Hankook Tire.
With the legal risks surrounding Chairman Cho Hyun-bum, who has led the group's business restructuring, now largely resolved, attention is turning to whether his full return to management will also help resolve the company's undervaluation.
Trapped in the 'Holding Company Discount'
According to the Korea Exchange and other sources, Hankook & Company's PBR stood at 0.43x as of the second quarter of this year. PBR measures how a company's share price compares to its asset value; a reading below 1 means the stock is trading below its book value.Hankook & Company's PBR has remained stuck in long-term undervaluation since its conversion into an operating holding company. The company was spun off in 2012 from Hankook Tire's investment division, and in 2021 it converted into an operating holding company through a merger with Hankook Atlas BX, which handles the automotive lead-acid battery business.
Its PBR came in at 0.40x in 2021, the year of the conversion, then fell to 0.34x in 2022, rose slightly to 0.37x in 2023, and slipped again to 0.36x in 2024. Last year it rebounded to 0.52x amid a rally in holding company stocks driven by revisions to the Commercial Act, but it fell back to 0.43x by the end of the second quarter of this year.
The primary reason cited for Hankook & Company's low PBR is the "holding company discount" characteristic of the Korean stock market. Hankook & Company holds its core operating unit, Hankook Tire, as a separately listed company, owning a stake of approximately 30.7%. More than 60% of the group's revenue and incoming cash flow is generated by Hankook Tire.
From an investor's perspective, buying shares of the operating company Hankook Tire directly is more advantageous than buying the holding company Hankook & Company when betting on growth in the tire business. As a result, the asset values of the holding company and its subsidiary end up being counted twice, and the market typically applies a discount of 50% to 60% to Hankook & Company.
Indeed, as of the first half of this year, Hankook Tire's market capitalization stood at KRW 8.2501 trillion, while that of holding company Hankook & Company was just KRW 2.3449 trillion.
Hankook & Company's relatively passive approach to shareholder returns has also failed to win over investors. Its dividend payout ratio has averaged around 30%, coming in at 28.89% in 2021, 37.17% in 2022, 35.41% in 2023, 27.01% in 2024, and 30.01% in 2025. Meanwhile, retained earnings — the funding source for dividends and other shareholder returns — grew from KRW 2.2024 trillion to KRW 3.0484 trillion over the same period. The debt ratio has been kept at around 10%.
A Noisy Family, Damaged Market Trust
Weak investor sentiment toward Hankook & Company stems not only from the holding company discount but also from two rounds of management disputes within the founding family and Chairman Cho Hyun-bum's legal troubles.In 2020, Honorary Chairman Cho Yang-rae finalized the succession structure by transferring his 23.6% stake via block deal to his younger son, Chairman Cho Hyun-bum, rather than his elder son, former advisor Cho Hyun-sik.
This provoked a backlash from Cho Hyun-sik and his elder sister, Cho Hee-kyung, chair of the Hankook Tire Nanum Foundation, sparking a management dispute between the siblings.
In 2023, while Chairman Cho Hyun-bum was in custody on embezzlement and breach-of-trust charges, former advisor Cho Hyun-sik attempted to expand his stake through a tender offer in partnership with MBK Partners. However, Chairman Cho Hyun-bum successfully defended his control by raising his stake to roughly 48% with the help of allies including Honorary Chairman Cho Yang-rae and Hyosung Group.
Having lost both rounds of the management dispute, former advisor Cho Hyun-sik stepped back from active management, but continued to exert influence — effectively exercising veto power over board agenda items on the strength of his 18.93% personal stake.
Last year, after Chairman Cho Hyun-bum was handed a prison sentence over embezzlement and breach-of-trust charges involving roughly KRW 20 billion, Cho Hyun-sik rallied minority shareholders to pressure his younger brother. Ahead of the ordinary shareholders' meeting in March this year, he also made behind-the-scenes moves to build a minority-shareholder coalition and exert influence over the board.
In the end, Chairman Cho Hyun-bum stepped down as CEO and inside director of Hankook & Company, saying he wanted to prevent the family conflict from spilling into the boardroom. Even so, he retained the group chairmanship and his roughly 48% stake, keeping his grip on control intact.
An investment banking industry source said the repeated exposure of the management dispute between Chairman Cho Hyun-bum and former advisor Cho Hyun-sik has driven foreign and institutional investors away, adding that Chairman Cho's ongoing legal troubles last year further eroded market trust in the company's transparency.
Cho Hyun-bum's Return Fuels Hopes of Ending the Undervaluation
Chairman Cho Hyun-bum was released on parole last month, bringing what appears to be closure to the owner-risk overhang on Hankook & Company. He has recently begun signaling his return to management, appearing at an internal AI transformation (AX) strategy meeting.This is notable given that the group's AX transformation has been a key agenda item for Chairman Cho since he took office. At his first official appearance since being paroled, he reportedly reviewed the status of the group's AX initiatives before anything else.
The business diversification Chairman Cho has pursued is also expected to gain momentum. Through the acquisition of Hanon Systems, the country's leading thermal management solutions provider, he has been building a future mobility value chain spanning batteries (Hankook & Company), tires (Hankook Tire), and thermal management (Hanon Systems).
While Hankook & Company maintains solid financial reserves thanks to its core cash cow, Hankook Tire, its return on equity (ROE) — a key profitability metric showing how much profit a company generates from shareholders' equity over a year, with 15% or higher generally considered efficient — has remained underwhelming.
Hankook & Company's ROE has never exceeded 10% since its conversion into an operating holding company, coming in at 5.53% in 2021, 4.37% in 2022, 4.76% in 2023, 8.28% in 2024, and 7.52% in 2025. As of the first half of this year, ROE stood at 8.27%.
Alongside the resolution of Chairman Cho's legal risk, news that Hankook & Company is reviewing a management buyout of Lotte Rental is also seen as part of a broader push toward business diversification and improved capital efficiency through large-scale M&A.
Hankook & Company also plans to strengthen shareholder returns — it paid an interim dividend for the first time since its founding in 2024 — and intends to raise and maintain its dividend payout ratio above 35% over the next three years.
An investment banking industry source said that following Chairman Cho's return to management, the company is expected to focus on strengthening accountable management and stabilizing its major business initiatives, adding that resolving the company's chronic undervaluation will require both raising the ratio of net income generated relative to net assets and pursuing more proactive shareholder-return measures such as treasury share retirement.
Kim JaeHun (rlqm93@fntimes.com)





















