





Coupang recorded its highest-ever sales of KRW 10.6 trillion in the 3rd quarter of this year. / Photo courtesy of Coupang
이미지 확대보기
In the third quarter conference call, Coupang Chairman Kim Beom-seok said about this performance, “This was largely due to the expansion of existing categories and the expansion of the latest services such as Rocket Growth (FLC),” and “Customer participation is increasing as we add more products to Rocket Delivery and provide more services.”
According to Coupang Inc.'s third quarter report submitted to the U.S. Securities and Exchange Commission (SEC) on the 6th (Korean time), Coupang's sales in the third quarter of this year amounted to KRW 10.69 trillion (USD 7.866 billion, exchange rate 1,359.02), up 32% from the same period last year (KRW 8.1028 trillion, USD 6.18355 billion). It is the highest quarterly sales ever.
Operating profit for the same period was KRW 148.1 billion (USD 109 million), up 29% from KRW 114.6 billion (USD 87.48 million) the previous year. However, Coupang's operating profit ratio to sales was 1.38%, a slight decrease from the previous year (1.41%) in profitability indicators. Net income for the period was KRW 86.9 billion (USD 64 million), down 27% from KRW 119.6 billion (USD 91.3 million) the previous year. However, after recording a net loss for the first and second quarters, it turned a profit in the third quarter.
Active customers ↑ · commerce sales ↑ despite monthly fee increase
Coupang raised its monthly paid membership fee in August of this third quarter. It increased it by 58% from KRW 4,990 to KRW 7,890 per month. It was expected that the number of ‘Escapees’ would increase due to the prolonged high prices, but instead, the number of consumers using Coupang increased. At the same time, sales in the commerce sector also increased.
The number of active customers in the product commerce sector, including Rocket Delivery, Rocket Fresh, Rocket Growth, and Marketplace, reached 22.5 million, an 11% increase from the same period last year (20.2 million). Active customers refer to the number of customers who have purchased items from Coupang at least once. It is an increase of 800,000 from the second quarter of this year (21.7 million).
The sales per customer of product commerce customers was KRW 432,160 (318 dollars), an 8% increase from the same period last year, and an increase from the second quarter of this year (KRW 423,400, 309 dollars).
In addition, the adjusted EBITDA surplus (operating profit before interest, taxes, depreciation, and amortization) in the product commerce sector increased by 18% year-on-year to USD 470 million.
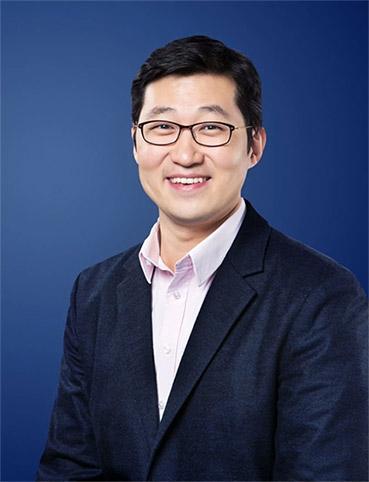
Chairman Kim Beom-seok emphasized the remaining growth potential during this conference call, saying, “We are only a very small part of the large-scale commerce market.” / Photo courtesy of Coupang
Chairman Kim Beom-seok “Adding more products and services… Customer participation ↑”
Chairman Kim Beom-seok said in this conference call, “Active product commerce customers increased by 11% compared to the same period last year,” and “Participation is increasing as we add more products to Rocket Delivery and provide more services. Customer spending increased at a high level this quarter as well.”
He continued, “The frequency of orders from Wow members, such as food delivery and Rocket Fresh delivery, is 9 times higher than the frequency of orders from non-Wow members,” and “Long-time Wow members spend 2.5 times more on average than new members.”
In particular, Chairman Kim emphasized the powerful benefits of ‘Wow Membership’ as one of the driving forces behind the increase in customer spending. He also mentioned the recently launched luxury beauty vertical service ‘R.LUX’ and announced plans to provide more services.
He said that the growth of Rocket Growth will also expand the range of customer choices. Rocket Growth is a service that allows small and medium-sized merchants to upload goods and Coupang will then provide full fulfilment services such as storage, packaging, delivery, and returns.
Chairman Kim emphasized, “FLC’s units, sellers, and total transaction volume are each increasing by more than 130% this quarter compared to the same period last year, continuing to grow at a strong pace,” and “FLC is still in its early stages, and its growth potential is limitless.”
In addition to this, Chairman Kim also said that he expects growth in Coupang Eats and Taiwanese services.
He said, “Only a quarter of customers purchase in more than nine of the 20 categories we currently offer,” adding, “We are only a small part of the large-scale e-commerce market. Most of the growth opportunities for the next few years have not yet been realized.”
Park seulgi (seulgi@fntimes.com)




















