





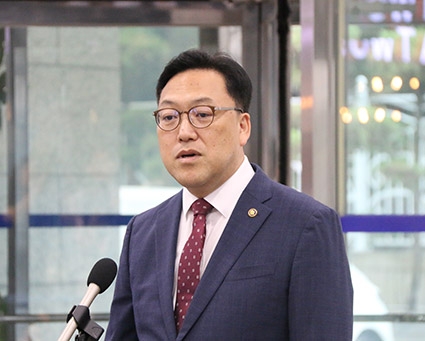
Kim Byung-hwan, Commissioner of the Financial Services Commission
Through this, the household debt ratio was lowered, indicating a willingness to fundamentally solve the financial system transfer concerns that occur every time an economic crisis occurs.
The previous government has pushed for DSR early to catch household loans, but it is interpreted as a plan to take this opportunity to bring House-Rental deposit loans into regulation and manage them under the name of"end-user loans."
According to the financial sector, Kim, the new commissioner of the commission, until recently cited "strengthening the management of household loans" as the top priority for the authorities.
When he was a candidate for commissioner of the Financial Services Commission on July 5 this year, he met with reporters on his way to the office in the Korea Deposit Insurance Corporation building in Jung-gu, Seoul, to prepare for the hearing.
"The reason for the accumulation of risks (in the financial sector) is that it is overly dependent on debt," he said."If you look at the debt ratio, it is quite high compared to foreign countries and it can be a constraint on economic growth in terms of sustainability."
In particular, he pointed out the problem of weakening economic players' ability to withstand crises such as global inflation at a time when household debt to GDP exceeded 100% until last year.
"When there is an external shock, the system (to the crisis) can be transferred," he said. "I think it is necessary to improve the debt-dependent part of the big framework in a different way, and we need to improve it through institutional support."
In fact, household debt surged as the era of ultra-low interest rates opened after the COVID-19 pandemic, and until last year, the ratio of household debt to GDP exceeded 100%.
In addition, more than 70% of domestic household loans were applied as variable interest rates, so the central banks, including the Bank of Korea, are rapidly starting to raise the benchmark interest rate to curb global inflation, and crises such as rising delinquency rates and poor real estate project financing are still shaking the financial sector.
The International Monetary Fund (IMF) and the Bank of Korea have warned several times that if the ratio of household debt to GDP exceeds 80%, the negative impact on economic growth could be significant as the private debt repayment burden will reduce consumption capacity.
According to the International Financial Association's Global Debt Report, Korea's household debt-to-GDP ratio stood at 98.9 percent in the first quarter of this year. It ranks fourth among 59 countries surveyed.
Lee Chang-yong, Bank of Korea Governor, said in a parliamentary audit last year, "The goal is to gradually lower the ratio to 80% after 90% as the ratio of household debt to GDP can limit economic growth or financial stability."
The way to reduce household debt to GDP is to slow household debt growth by raising interest rates and tightening regulations amid a faster recovery in economic growth.
The reason why the banking sector has recently raised interest rates on household loans is to reduce the pace of debt growth.
However, the recent increase in interest rates on mortgage loans is only a slight increase. In the long run, the bank's household loan interest rate has been on the decline.
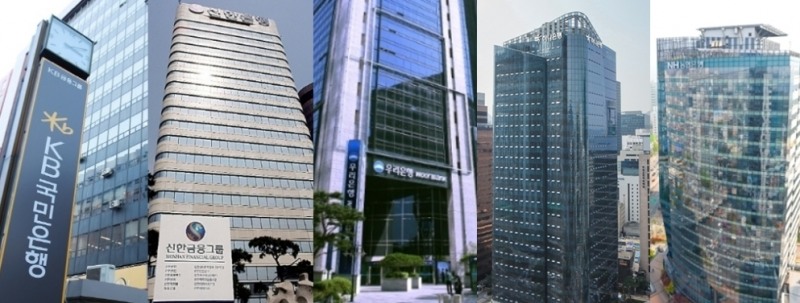
From left, the headquarters of KB Kookmin Bank, Shinhan Bank, Woori Bank, Hana Bank, and NH Bank. (Photo Image = each company)
이미지 확대보기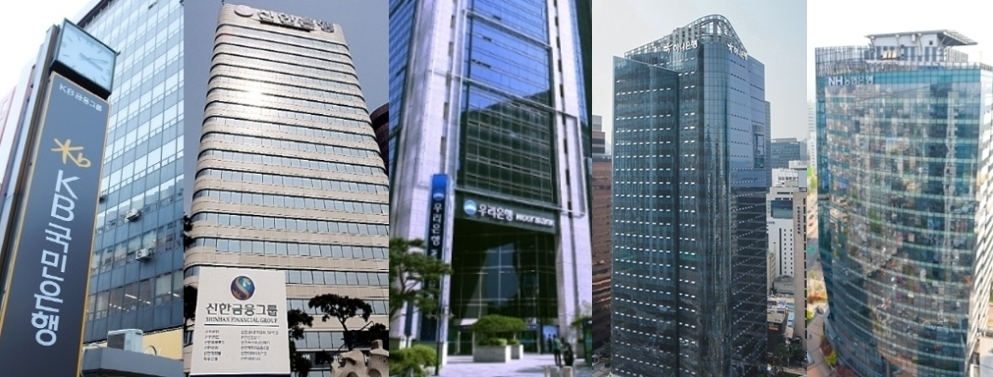
According to the Bank of Korea's June 2024 weighted average interest rate on financial institutions released on July 31, the loan interest rate based on the new handling amount of banks was 4.71percent last month, down 0.07 percentage points from a month ago.
In particular, the mortgage rate fell for eight consecutive months and entered the mid-3% range.
Because of this situation, household loans in the banking sector have been increasing rapidly this year. According to the Financial Services Commission's report on household loan growth this year, ▲ 4.1 trillion won in January ▲ 3.7 trillion won in February ▲ 20 billion won in March ▲ 4.1 trillion won in April, 5.6 trillion won in May ▲ 6.1 trillion won in June.
The nationwide housing sales volume also increased every month from 38,000 units in December last year to 43,000 units in January this year ▲ 43,000 units in February ▲ 53,000 units in March ▲ 58,000 units in April ▲ 57,000 units in May.
In response, an official from the Financial Services Commission explained, "The increase in mortgage loans has expanded due to the continued increase in policy loans such as Di-dim-dol mortgage loan and Beo-tim-mog reliable House-Rental deposit loan and the recovery of housing transactions."
In addition, domestic real GDP growth in 2Q 2024 contracted 0.2% from the previous quarter. There is also the impact of the base effect from the large growth (1.3%) in the first quarter, but it is also interpreted that it is difficult to lower the ratio of household debt to GDP.
The problem is that real estate loans are tied to 40% of DSR for each borrower, so even if the loan limit cannot be increased unless the borrower's income increases, House-Rental deposit loans are excluded from the regulation and "gap investment" is still possible when investing in real estate.If the base interest rate is lowered in the future, interest rates in the loan market will fall overall, which could encourage gap investment.
Analysts say that household debt management may become increasingly difficult.
For this reason, the Financial Stability Report released by the Bank of Korea in December last year advised that some DSR needs to be applied to lease loans as well, saying, "As lease loans were used as some gap investment funds, it acted as a factor for rising housing prices and increasing volatility in the housing market." Kim is also said to have talked about the importance of managing household debt before taking office as the commissioner of the Financial Services Commission because he is fully aware of these points.
However, the financial sector believes that the Financial Services Commission, as with the previous government, will gradually include the entire lease on a deposit basis loan in the DSR, such as regulations on interest and additional lease on a deposit basis loans. Because lease on a deposit basis loans are closely linked to housing stability for ordinary people, premature regulation can lead to market confusion.
Kim also said, "It is necessary to implement it step by step so that the expansion of regulations does not lead to a sudden shock to consumers."
The argument that regulations on lease on a deposit basis loans should be strengthened to the level of mortgage loans drew a line,saying, "It should be carefully considered."
It is believed that Kim also has no plans to suddenly regulate lease on a deposit basis loans enough to shock the market.
During his confirmation hearing for the new Treasury chairman, he said, "We need to phase in and implement regulations gradually so that the expansion of regulation does not lead to a sudden shock to consumers."
Lee Yongwoo (lee@fntimes.com)





















