





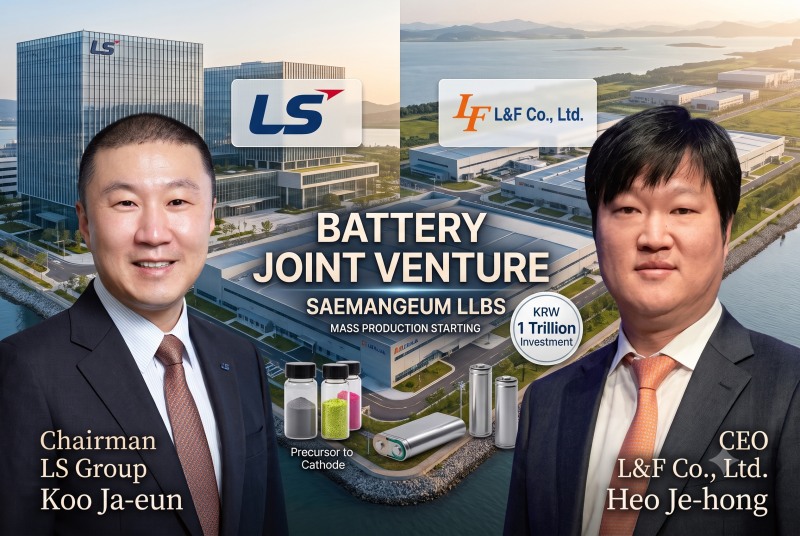
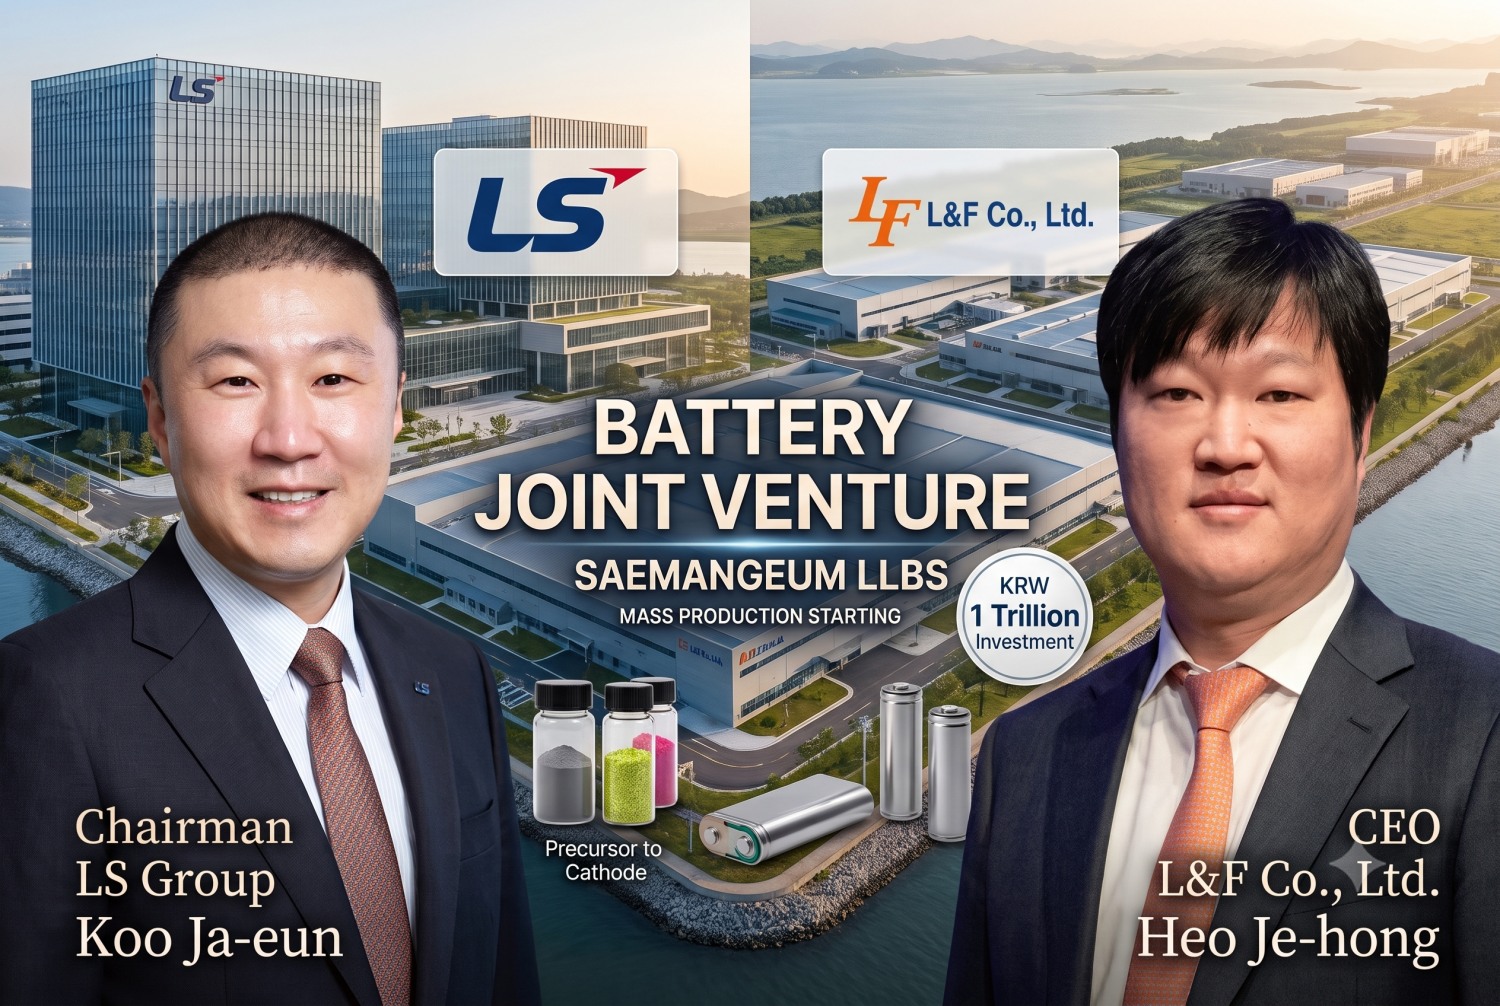
LS and L&F set up the precursor-production joint venture LS-L&F Battery Solution (LLBS) in October 2023, aiming to secure raw material supply stability and strengthen supply chain competitiveness. Precursor material is produced by combining nickel, cobalt and manganese, and serves as the core material in the stage immediately before cathode material production.
LLBS began trial operations at its Saemangeum plant in March last year. With a total investment exceeding KRW 1 trillion, the company plans to start mass production this year and expand annual capacity to 120,000 tons by 2029.
LS holds 55% of the joint venture and L&F 45%. As LLBS remains at the pre-commercial production stage, it posted revenue of KRW 224 million and a net loss of KRW 9.2 billion last year. L&F is effectively its only customer — the KRW 224.42 million worth of raw materials L&F purchased from LLBS last year nearly matches LLBS's total revenue for the year.
The joint venture marks the first time the Koo and Heo families have come together again since they officially split in 2005 through the separation of the LG and GS business groups — 18 years ago.
Chairman Koo Ja-eun, the third-generation head of LS Group, is leading the conglomerate under a "two-handed management" strategy that pursues both its core businesses — wire and cable, power infrastructure — and future growth areas such as batteries, electric vehicles and semiconductors.
CEO Heo Je-hong, a fourth-generation manager from the broader GS family, has built L&F into a global cathode material company. His late father, Heo Jeon-su, chairman of Saeronix, was a cousin of Huh Chang-soo, honorary chairman of GS Group — the two surnames "Heo" and "Huh" being alternate romanizations of the same Korean family name (許). Heo Je-hong took a more active role in management after his father's death in 2010.
The uneven equity split in favor of LS reflects differences in capital strength. L&F has long been seen as having a relative weakness in securing the large-scale funding needed to build out its raw material supply chain.
The 55:45 equity ratio set at the joint venture's founding in 2023 has remained unchanged through subsequent capital increases. In a 2024 capital injection, LS contributed KRW 59.95 billion and L&F KRW 49.05 billion, each in proportion to its respective stake.
The two companies also signed a shareholders' agreement. If either party sells its stake in LLBS, the other is granted a right of first refusal, and both sides can exercise tag-along rights. The agreement also includes a call-option clause allowing one party to buy out the other's stake in the event of a breach of contract.
For Chairman Koo Ja-eun, the joint venture completes a battery value chain running from nickel sulfate (LS MnM) to precursor material (LLBS) to cathode material (L&F).
L&F, for its part, is working to build a supply chain that meets overseas regulatory requirements, and the domestic joint venture is aimed at stabilizing that supply chain.
L&F's own value-chain reorganization took place around the same time. Saeronix sold its entire 24.61% stake in precursor affiliate JH Chemical to L&F last year.
JH Chemical also produces precursor material by combining nickel, cobalt and manganese, putting it in the same business area as LLBS. The move is widely interpreted as an effort to consolidate the group's scattered precursor-related holdings into a single entity, LLBS.
Of L&F's total raw material purchases last year — KRW 2.1212 trillion — precursor-inclusive raw materials such as NCM accounted for 99.53%, or KRW 2.1113 trillion. That heavy reliance on stable raw material supply, which is directly tied to the company's bottom line, was also a factor behind the joint venture.
Jung Jina (urzinnie@fntimes.com)





















