





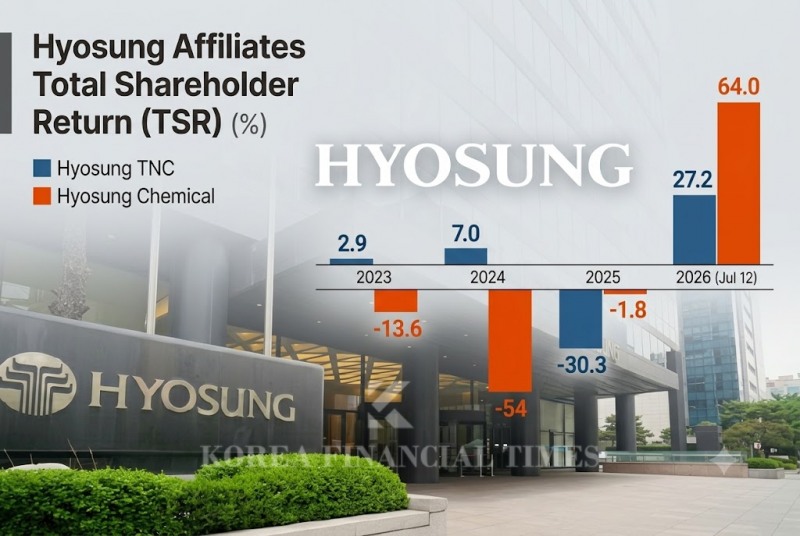
This infographic, originally published by Korea Financial Times, has been reconstructed using generative AI.
이미지 확대보기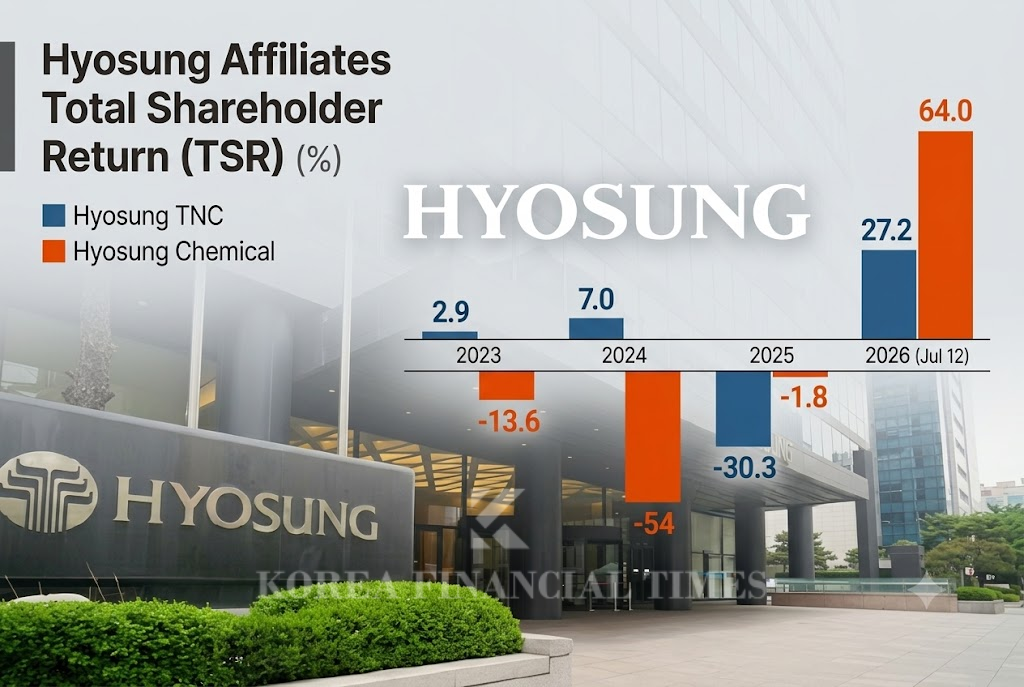
Hyosung TNC's recent share price trend has been somewhat weak. The stock closed at KRW 278,000 on July 16. That is up 30% from the start of the year, but it has given back much of the gain that had been driven earlier this year by hopes that a bankruptcy crisis at a Chinese spandex rival would ease the industry's oversupply.
Since hitting its year-to-date high of KRW 535,000 on April 28, the stock has weakened by nearly half. This is seen as the market correcting itself after the anticipated recovery in downstream industry conditions proved slower than expected.
By contrast, Hyosung Chemical closed at KRW 58,100 on July 16.
That is 49% higher than the KRW 38,900 closing price on the day trading was suspended in March last year amid a delisting crisis triggered by full capital impairment. It also marks a 5.6% gain from the KRW 55,000 closing price on the first day trading resumed, about one year and four months later, and a 39% rise from this year's closing low of KRW 41,800, recorded on July 2.
It was Hyosung TNC that rescued Hyosung Chemical from the brink of full capital impairment. Hyosung Chemical had originally sought to sell its specialty gas (NF3) business — used in semiconductor and display manufacturing — to an outside buyer to shore up its finances, but when that plan failed to materialize, Hyosung TNC stepped in and acquired the unit for KRW 930 billion.
Hyosung TNC persuaded shareholders to approve the deal by citing the prospect of higher profits from the semiconductor boom, synergies with its existing specialty gas business, and future portfolio diversification through expansion of related businesses.
The impact of the specialty gas acquisition remains unclear. According to Hyosung TNC's business report, Hyosung Neochem — the entity incorporated through the specialty gas unit acquisition — posted a net loss of KRW 18.6 billion last year, followed by a further loss of KRW 5.9 billion in the first quarter of this year. To be sure, investment to expand the related business is still underway, and since the company has pledged mid- to long-term growth through 2029, it may still be too early to judge the outcome of the acquisition.
HS Hyosung's Growth Gamble Backfires as Debt Fears ResurfaceHyosung's One-Engine Problem: Heavy Industries Soars While Textiles and Chemicals DragDoosan Fuel Cell Posts KRW 100 Billion Operating Loss, Yet Delivers 11x Returns to InvestorsLIG Calls for Global Leap, Faces 'Koo Family Company' Label Challenge [KFT Topic]
A more pressing concern is the criticism that the investment may have been overly aggressive given Hyosung TNC's financial condition.
According to THE COMPASS, Korea Financial Times' proprietary AI data platform, Hyosung TNC's free cash flow (FCF) came to KRW 339.3 billion in 2023, KRW 386.6 billion in 2024, turned negative at KRW -2.9 billion in 2025, and stood at KRW -26.0 billion in the first quarter of 2026.
FCF remained solid through 2024 but turned negative in 2025, the year Hyosung TNC acquired Hyosung Chemical's specialty gas business. Operating cash flow fell 30% year-on-year in 2025, while capital expenditure (CAPEX) rose 70%.
The company also expanded its borrowing to fund the specialty gas acquisition and other spending. Net debt rose 77%, from KRW 1.1985 trillion in 2024 to KRW 2.1262 trillion in 2025.
Net debt stood at KRW 2.2424 trillion as of the first quarter of 2026, with interest expenses of KRW 21.5 billion incurred in that single quarter alone. The interest expense-to-operating profit ratio came to 4 times — a level considered especially excessive amid the current rate-hike environment.
Hyosung TNC runs the trading business that was Hyosung Group's founding operation, as well as the textile division that built the group into what it is today, and it remains the core affiliate generating the most revenue.
Recently, however, it appears to have ceded the spotlight to Hyosung Heavy Industries, which has ridden the AI-driven boom in power equipment.
Looking at total shareholder return (TSR, dividend yield plus share price appreciation) from January 1, 2023 to July 12, 2026, Hyosung Heavy Industries posted a TSR of 3,658%.
That means an investment of KRW 1 million in Hyosung Heavy Industries three years and seven months ago would now be worth KRW 37.58 million, assuming dividends were not reinvested. Over the same period, Hyosung TNC's TSR was just 3.7%, meaning that same KRW 1 million investment would be worth only KRW 1.037 million.
Gwak Horyung (horr@fntimes.com)


















