





Steeling Against the Slump: Subsidiaries Hold the Line
POSCO Holdings recorded consolidated revenue of KRW 17.876 trillion and operating profit of KRW 707 billion for the first quarter of this year, representing increases of 2.5% and 24%, respectively, compared to the same period a year earlier.The steel segment faced limited profitability amid sluggish global demand and cost pressures, but steep earnings improvements at non-ferrous metal and energy affiliates drove the group's overall growth.
POSCO International was the standout performer, delivering a surprise earnings beat and serving as the most pivotal contributor to the group's overall results. POSCO International's first-quarter operating profit, disclosed on the same day, came in at KRW 357.5 billion — a 32% surge year-on-year that exceeded brokerage consensus by more than 10%. The outperformance was attributed to increased output at Australia's Senex Energy, as well as the operation of a high-margin portfolio in the LNG and crude oil trading businesses.
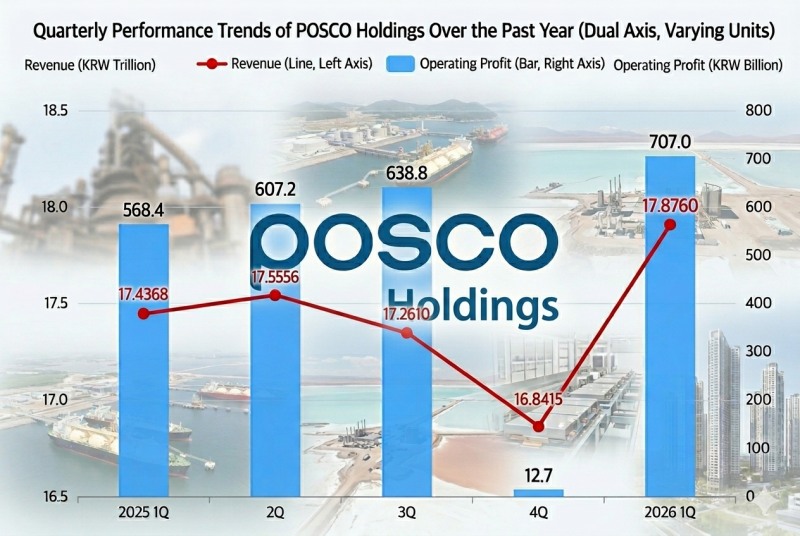
This infographic, originally published by Korea Financial Times, has been reconstructed using generative AI (Gemini). / Source = POSCO Holdings
이미지 확대보기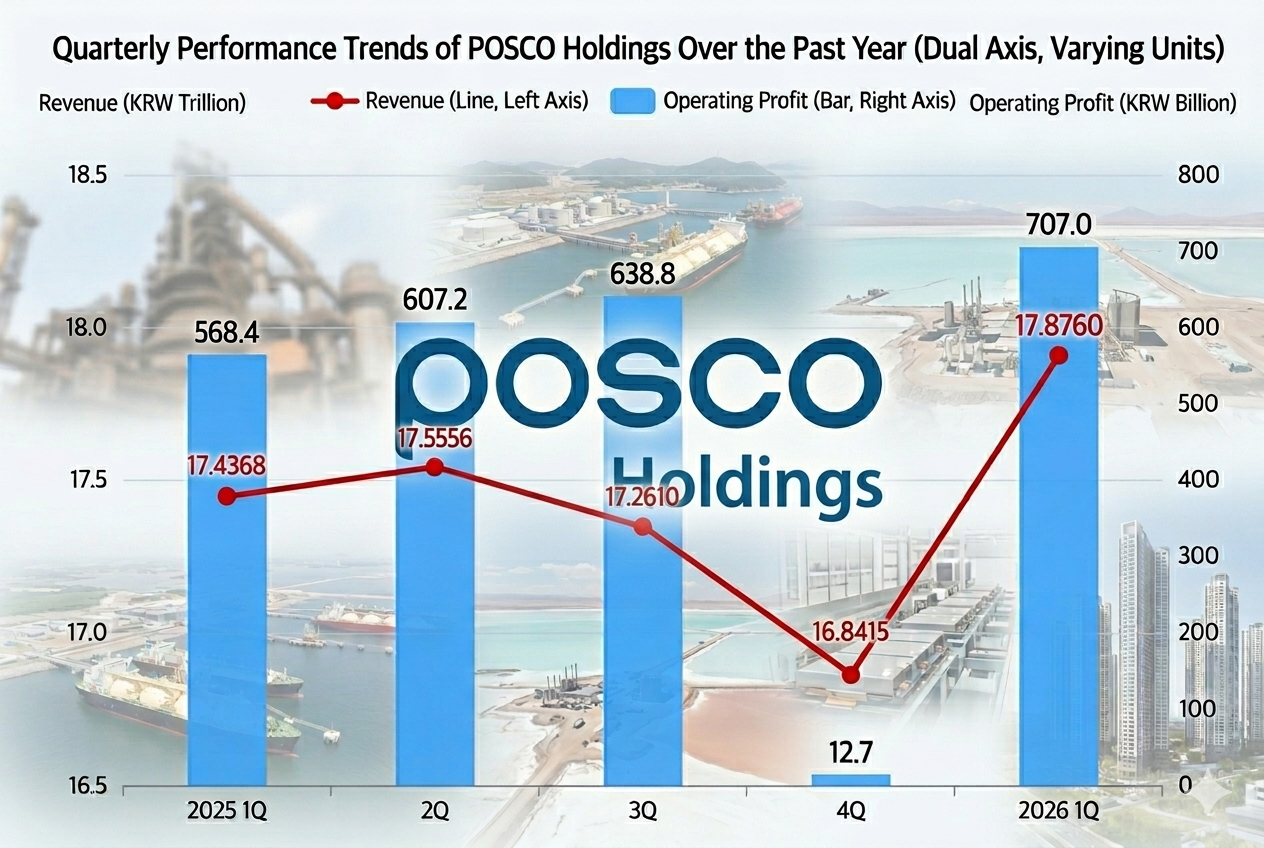
The advance of the secondary battery materials segment was equally noteworthy. POSCO Future M successfully returned to profitability through expanded sales of high value-added products, while POSCO Argentina and POSCO Pilbara Lithium Solutions significantly narrowed their operating losses, supported by rising lithium prices and higher production volumes.
Notably, POSCO Argentina recorded its first monthly operating profit in March, signaling a full-fledged shift to earnings generation in the second quarter. POSCO E&C also bolstered the group's overall earnings capacity as major domestic and overseas construction projects returned to normal progress and overseas subsidiaries — including its Zhangjiagang entity in China — increased their profit contribution.
The strong performances by these subsidiaries demonstrate that POSCO Holdings' earnings structure has broken free from its single-pillar dependence on steel and has entered a genuinely diversified orbit. Analysts interpret this as evidence that the strategy of reducing exposure to the highly volatile steel cycle while pivoting the portfolio toward resources and energy is delivering tangible results.
POSCO Holdings Finds New Revenue Engine in Energy, but Debt Shadow DeepensPOSCO Holdings Completes 6% Share Cancellation Pledge — But Core Profit Recovery Remains the Missing PieceSix Years Locked Away: What Will Hyundai Steel Decide on Its Treasury Shares at This AGM?Korea's Four SI Firms Race to Own the Humanoid Operating System
After Confirming Results, the Rally Accelerates: China Output Cuts and Price Hike Expectations Priced In
Market attention is now squarely focused on the sharp share price reaction that has followed the solid earnings confirmation. As of the closing price on May 7, POSCO Holdings shares stand at KRW 535,000. What is particularly striking is the pace of the ascent: having retreated to KRW 318,000 as of March 4, the stock has surged 68.2% in just over two months.The market views the current price as already discounting catalysts well beyond the confirmed first-quarter scorecard — namely, second-half product price increases and the commercial launch of lithium operations. Observers say signals are emerging that the steel industry, after an extended slump, has entered a genuine turnaround.
Photo courtesy of POSCO Holdings
Above all, the intensification of global supply-demand imbalances has served as a powerful trigger lifting the share price. Iran, a major Middle Eastern steel producer, recently decided to impose a blanket ban on exports of steel slabs and plates through the end of next month, heightening supply tension across global supply chains.
Adding to the positive backdrop, China — the world's largest steel producer — officially confirmed that crude steel output last year fell 4.4% year-on-year to 961 million tons, making its production-cut stance unmistakably clear. As supply-side bottlenecks sharpened, POSCO Holdings appears to have reclaimed pricing leadership in the market.
The company raised prices for hot-rolled and cold-rolled steel sheet by KRW 50,000 per ton in the second quarter, beginning to pass rising costs through to product prices. Hyundai Steel and other industry peers have followed suit, sending a clear signal of price normalization across the sector.
Lithium Business Takes Shape: Corporate Value Restructured Around Secondary Battery Materials
The other key variable that prevents POSCO Holdings from being pigeonholed as a conventional steel stock is lithium.This year, with the first-phase plant at the Hombre Muerto salar in Argentina entering commercial operations in the first half, the company has established a lithium hydroxide production system capable of generating 25,000 tons annually — enough to supply batteries for approximately 600,000 electric vehicles.
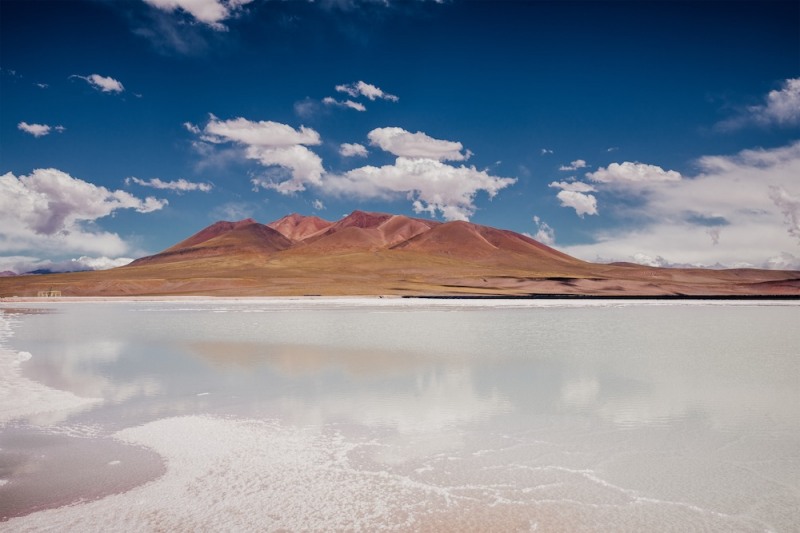
A panoramic view of the Hombre Muerto salt flat in Argentina. / Photo courtesy of POSCO Holdings
이미지 확대보기
When construction at Australia's Greenbushes mine and the expansion of the Gwangyang Plant 2 are completed, the group's total lithium production capacity will expand to 93,000 tons — a level sufficient to rank the company among the top 5 to 10 lithium producers globally.
Major investment institutions, including Meritz Securities, are currently valuing POSCO Holdings' lithium business at approximately KRW 8.2 trillion and are leading a broad-based valuation re-rating.
Ultimately, the sharp surge in POSCO Holdings' share price is being interpreted as the convergence of a near-term tailwind — recovery in steel — and a medium-to-long-term momentum driver: the materialization of its lithium business. Having long languished in deeply undervalued territory at a price-to-book ratio (PBR) of around 0.5x, POSCO Holdings is now expected to command a premium as a materials company.
"If the first-quarter results confirmed the company's fundamental staying power," said one industry official, "the share price is now racing toward the future. As the point approaches when the lithium value chain begins translating into actual cash flows, the re-rating of POSCO Holdings' corporate value will only accelerate further."
Jeong Chaeyun (chaeyun@fntimes.com)


















