





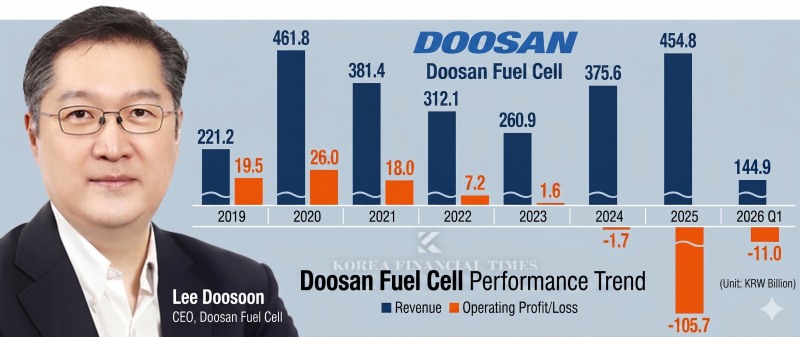
This infographic, originally published by Korea Financial Times, has been reconstructed using generative AI (Gemini).
이미지 확대보기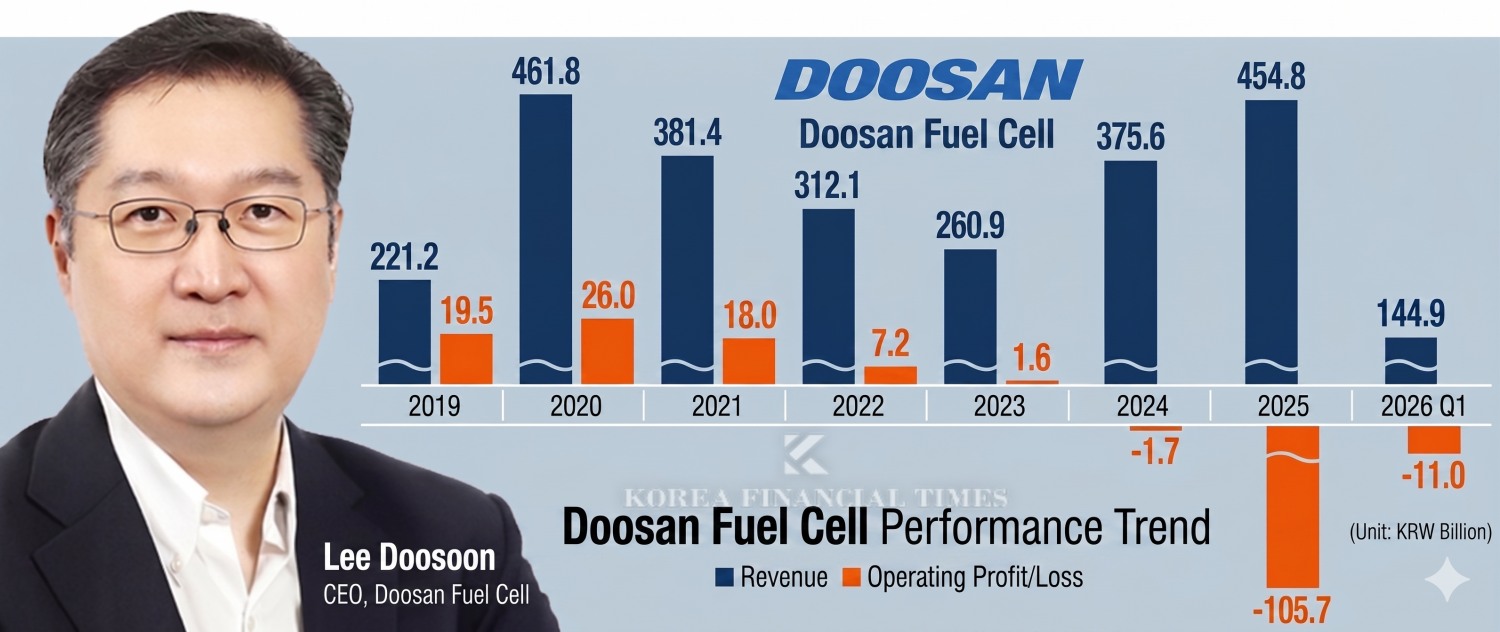
TSR and Financial Performance Out of Step
According to an analysis of Doosan Fuel Cell's cumulative total shareholder return (TSR) conducted by Korea Financial Times using corporate data platform DeepSearch, the figure reached 1,003.45% from October 18, 2019 to April 30, 2026.The share price, which stood at KRW 5,510 on the first day of the analysis period, had surged to KRW 60,800 by the end date. As Doosan Fuel Cell has never paid a dividend since its inception, share price appreciation alone directly determines the cumulative TSR.
TSR is a metric that reflects total returns actually available to shareholders by combining share price gains and dividend yield over a given period. In practical terms, an investor who put in KRW 1,000,000 at the time of Doosan Fuel Cell's listing and held through to the present would find approximately KRW 11,030,000 in their account — an 11-fold return delivered to shareholders even amid persistently weak financial results.
Looking back at Doosan Fuel Cell's history, the trajectory is all the more dramatic. The company was established on October 1, 2019 through a spin-off of the fuel cell division of Doosan Corporation and made its Korea Stock Exchange (KOSPI) debut approximately 17 days later.
After setting an all-time high of KRW 63,800 in February 2021, the stock languished in the KRW 10,000s through the first half of last year. A recovery that began in the second half of last year, however, saw the share price break back above KRW 60,000 on April 30, the last trading day of that month.
Beneath the surface, financial strain is substantial. Revenue peaked at KRW 461.8 billion in 2020 before contracting to KRW 260.9 billion by 2023, then partially recovered to KRW 375.6 billion in 2024 and KRW 454.8 billion in 2025.
Profitability, meanwhile, has been on a steady downward trajectory since recording operating profit of KRW 26 billion in 2020. It declined to KRW 18 billion in 2021, KRW 7.2 billion in 2022, and KRW 1.6 billion in 2023. The company swung to an operating loss of KRW 1.7 billion in 2024, and then posted an operating loss of KRW 105.7 billion in 2025.
The Robot Gamble: Doosan Robotics CEO Bets Big on North America Despite 11 Straight Years in the Red'From Heavy Industry to Humanoids' — Doosan Robotics Charts a New Future in Physical AI [K-Humanoid Wars, Part 3]Kumho Petrochemical's Treasury Shares Face Governance Test After 20 Years [Treasury Share Report]
The 2024 deterioration was driven largely by the acquisition of HyAxium Motors, an electric and hydrogen bus manufacturer, as a wholly owned subsidiary. Doosan Fuel Cell's standalone operating profit, excluding HyAxium Motors, came in at KRW 300 million.
Additional headwinds included rising fixed costs associated with investment in a solid oxide fuel cell (SOFC) plant and the acquisition of electrode production facilities, as well as lower average unit selling prices.
In 2025, the losses widened further due to a confluence of one-time factors: rising raw material costs including platinum, early replacement expenses for initial domestically produced Cell Stack Assembly (CSA) products, and costs stemming from early-stage setbacks in SOFC commercialization.
Can AI Data Center Tailwinds Overcome Policy Risks?
Despite the persistent losses, market sentiment remains broadly constructive, as the company's connections with Big Tech firms — a potential solution to looming order cliffs — are becoming more tangible. In particular, hydrogen fuel cells are attracting growing attention as a power supply solution for data centers fueled by the artificial intelligence (AI) boom.Meritz Securities recently stated in a research report that "Big Tech's interest in phosphoric acid fuel cells (PAFC) is genuine." With Bloom Energy, the world's leading fuel cell company, seeing its stock surge after signing a supply agreement with Oracle, Meritz noted that Doosan Fuel Cell is also in concrete discussions on supply agreements with North American Big Tech companies, with deals expected within the year.
KB Securities also stated that "additional new orders for PAFC systems destined for North American data centers are expected to materialize during the first half of this year, with cumulative annual orders of 170 megawatts (MW) anticipated."
One industry official described Doosan Fuel Cell's hydrogen fuel cells as essentially a type of "hydrogen container" — capable not only of generating electricity from hydrogen, but also of storing that electricity directly on-site. The official added, however, that "there are still many hurdles to clear before actual commercialization, including establishing economic viability and verifying safety."
Doosan Fuel Cell has completed development of an SOFC-based marine fuel cell and is currently in the demonstration phase.
Domestic partnership building is also progressing actively. In February of this year, Doosan Fuel Cell partnered with LG Electronics to develop energy convergence business models, including a heating, ventilation and air conditioning (HVAC) system utilizing fuel cell waste heat. In November last year, the company signed memoranda of understanding (MOUs) with SK Ecoplant and Hyosung Heavy Industries to pursue a data center power supply solution business.
Policy uncertainty remains an outstanding challenge. South Korea's domestic fuel cell industry has built its ecosystem on the foundation of the Renewable Portfolio Standard (RPS) and the hydrogen economy revitalization roadmap. Following the enactment of the Hydrogen Act in 2021, the Clean Hydrogen Power Standard (CHPS) was introduced alongside a 2022 revision to the law.
A competitive bidding market for hydrogen power generation was formally launched in 2023, with Doosan Fuel Cell taking a leading position on the strength of its proprietary PAFC technology and dominant supply capability. The company backed that position with results: it won more than 50% of total capacity — measured by installed capacity — in the general hydrogen power generation auctions of both 2023 and 2024.
The concern now centers on government policy direction. The Ministry of Climate, Energy and Environment is reportedly reviewing options to be disclosed this month via an official CHPS notice, including a reduction in general hydrogen auction volumes or an outright abolition of that market segment. The CHPS currently operates with separate auction tracks for general hydrogen and clean hydrogen; the anticipated restructuring appears intended to shift the system toward clean hydrogen — reducing the share of fossil fuel-derived "gray hydrogen."
Another industry official noted that "the general hydrogen market was originally designed to expand distributed power generation, and its structure accommodates gray hydrogen," while cautioning that "South Korea's domestic clean hydrogen production capacity remains insufficient."
The market, however, is looking past domestic policy risks to the potential of export markets. Meritz Securities assessed that "the potential order pipeline in export markets — running from hundreds of megawatts to the gigawatt (GW) scale — is far larger than the domestic market, which operates at the scale of tens of megawatts."
Hana Securities noted that "with growing room for a reduction in dedicated fuel cell auction volumes due to domestic policy changes, it remains to be seen whether the company can offset this through overseas expansion," adding that "an SOFC supply agreement with an overseas client is expected during the second quarter of this year, and a large-scale contract targeting the United States is also within sight."
Shin Haeju (hjs0509@fntimes.com)


















