





OTOKI has made a bold bet on global expansion. To recover the profitability that deteriorated last year and to secure a new growth engine, the company has decided to establish a local subsidiary in Japan. The move is seen as a strategy to break through the slump in domestic consumption and to lift the company's financial soundness indicators, which lag behind those of its competitors.
Overcoming Domestic Limits Through Direct Global Expansion
According to industry sources on June 9, OTOKI completed the establishment of a local sales subsidiary in Tokyo, Japan, on the 15th of last month. The subsidiary is scheduled to begin full-scale operations after September this year. The Japanese unit is OTOKI's fourth overseas local subsidiary, following those in New Zealand, the United States, and Vietnam.Regarding the move, OTOKI explained that it "plans to broaden points of contact with local consumers in the Japanese market and strengthen the foundation for expanding its overseas business." In the Japanese market, OTOKI plans to sell products including ramen, sauces, and sesame oil.
OTOKI's swift move to secure an overseas foothold is a preemptive measure aimed at solidifying the recently confirmed trend of an earnings rebound while building a long-term source of profit.
OTOKI's first-quarter revenue this year stood at KRW 955.2 billion on a consolidated basis, up 3.7% from the same period a year earlier. Operating profit over the same period rose 3.3% to KRW 59.4 billion. Increased sales of major product lines such as rice products and cooking oils drove the improvement in earnings.
Overseas business is also sailing smoothly. In the first quarter, OTOKI's overseas revenue rose 9.6% year-on-year, and the share of overseas revenue in total revenue expanded from 10.9% in the first quarter of last year to 11.5%.
While the increase in first-quarter revenue and profitability is positive, last year the company suffered an earnings slump that exposed the limitations of its domestic-focused business structure. Last year, OTOKI's consolidated revenue was KRW 3.6745 trillion, up 3.8% from the previous year. However, operating profit over the same period fell 20.2% to KRW 177.3 billion.
SK's Holding Subsidiaries Diverge: SK Discovery Falls Behind the PackLG Electronics CEO Ryu Jae-cheol's Robot Ambitions: What's Behind the CompetitivenessRebounding from a Plunge: Does POSCO Future M's Z-Score Signal a Revival?Solid Finances, Underwhelming Returns: Yuhan Corporation's Capital Efficiency ChallengeSamsung SDS Taps KKR to Fuel AI and M&A Overhaul with KRW 7.6 Trillion
OTOKI cited the rise in exchange rates, higher raw material unit prices, and increased labor and advertising and promotional expenses as the reasons behind the decline in profitability. In particular, the analysis suggests that the contraction of the domestic market worsened the domestic business environment, weighing on profitability.
Low Z-Score Alongside Overseas Share in the 10% Range
Last year, OTOKI's overseas revenue grew 13.4%, and the share of overseas revenue in total revenue rose 1.0 percentage point from the previous year to 11.2%. Although the share of overseas revenue in total revenue has grown, it remains in the low 10% range — far short of its competitors. Nongshim's figure stands at 40%, while Samyang Foods maintains a level in the 80% range.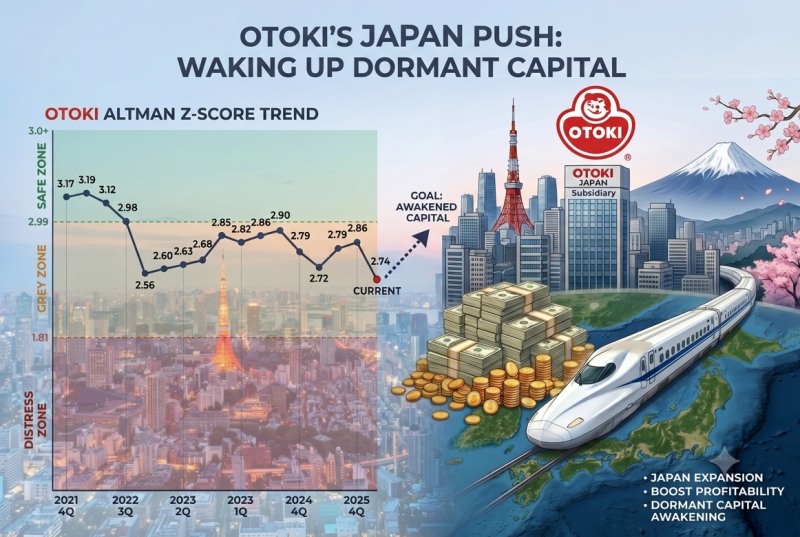
This infographic, originally published by Korea Financial Times, has been reconstructed using generative AI (Gemini).
이미지 확대보기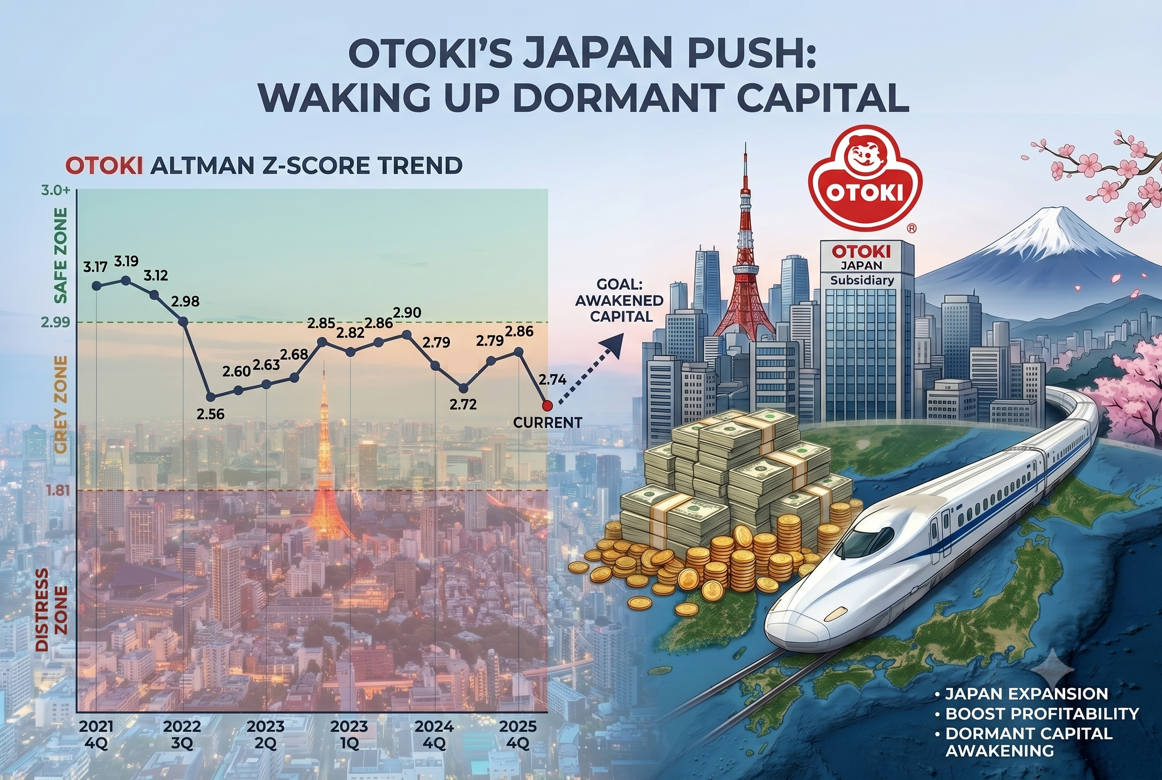
Nongshim and Samyang Foods, both with large overseas revenue shares, are overcoming domestic limits and significantly boosting the profitability of their entire businesses through overseas sales. In the first quarter of this year, on a consolidated basis, Nongshim's overseas subsidiary revenue rose 23.1% year-on-year to KRW 312.8 billion, while operating profit increased 20.1% to KRW 67.4 billion. Samyang Foods likewise achieved overseas revenue of KRW 585.0 billion, up 38.0% over the same period, with operating profit rising 32.2% to KRW 177.1 billion.
The low overseas revenue share has affected not only profitability but also financial soundness and capital efficiency. OTOKI's Altman Z-Score was 2.85 in 2023, 2.79 in 2024, and 2.74 in 2025. This stands in stark contrast to Nongshim (4.41 in 2023, 3.89 in 2024, 3.97 in 2025) and Samyang Foods (3.90 in 2023, 7.12 in 2024, 8.77 in 2025), both of which are generating profits on the back of overseas earnings.
The Altman Z-Score is one of the indicators that investors and financial institutions use to assess a company's credit risk or to decide on investment and lending. A Z-Score of 3 or higher is considered stable, while a score below 1.8 is seen as indicating a high probability of bankruptcy.
A Full Treasury, but Efficiency Has Plunged
Looking at the raw figures alone, OTOKI's financial condition appears solid. The company's current assets stood at KRW 1.4057 trillion in 2023, KRW 1.4788 trillion in 2024, and KRW 1.5013 trillion in 2025, comfortably exceeding its current liabilities (KRW 904.9 billion in 2023, KRW 1.0288 trillion in 2024, and KRW 1.0476 trillion in 2025). Retained earnings — representing the cash piled up in the treasury — have also steadily grown, reaching KRW 1.9134 trillion in 2023, KRW 2.0112 trillion in 2024, and KRW 2.0331 trillion in 2025. In other words, there is no immediate problem with liquidity.The problem lies in the deterioration of asset quality and capital efficiency. The Altman Z-Score assigns a high weighting not merely to the size of assets but to actual profit-generating capacity, such as operating profit margin relative to total assets. As retained earnings accumulated, the company's total asset base grew, but the core metric — operating profit — plunged nearly 20% from the previous year, dragging down the overall Z-Score.
This is in line with the decline in the return on invested capital (ROIC) indicator, which shows how much profit a company has earned relative to the capital it has invested in its business operations. OTOKI's ROIC fell from 7.1% in 2023 to 6.0% in 2024 and 4.3% in 2025. This means that despite stockpiling massive retained earnings of more than KRW 2 trillion, the company has failed to channel them into high-yield businesses, resulting in inefficient capital allocation.
Ultimately, OTOKI's overseas territorial expansion, including the establishment of the Japanese subsidiary, is a strategic decision to awaken dormant capital. The idea is to avoid tying up money in a domestic market where growth has stalled, and instead aggressively reallocate capital to overseas markets that offer relatively higher margins and steeper growth.
An OTOKI official said, "Our overseas revenue target for 2030 is KRW 1.1 trillion, and there are no specific plans regarding the use of internal reserves."
Yang Hyunwoo (yhw@fntimes.com)


















