





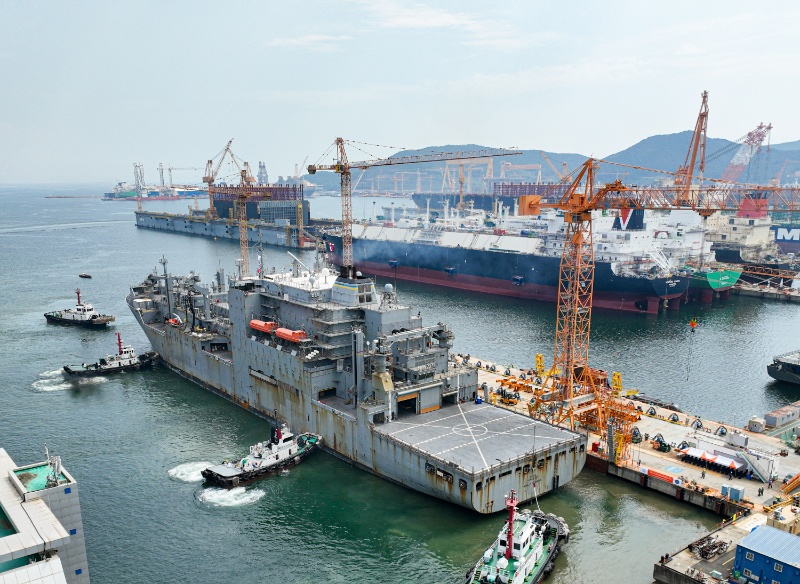
The US Navy logistics support ship 'Wally Sheera' approaches the quay wall after arriving at Hanwha Ocean's Geoje facility for ship maintenance. /Photo courtesy of Hanwha Ocean
이미지 확대보기
According to financial information firm FnGuide, the consensus (average forecast of securities firms) for Hanwha Ocean's third-quarter operating profit was KRW 55.8 billion, down 24.73% year-on-year.
In the same period, HD Hyundai Heavy Industries (CEO Lee Sang-gyun) and Samsung Heavy Industries (CEO Choi Sung-an) were forecast to earn 181.2 billion won and 114.8 billion won, up 1303.54 % and 51.26 %, respectively, from the same period a year earlier.
The three shipbuilders' operating profit estimates for the third quarter of this year were generally set at a high level. Shipbuilding orders were good enough for the shipbuilding industry to enter the super boom (super cycle), and the fall in backplate prices, which account for 15 to 20 percent of manufacturing costs, was a positive factor in improving the shipbuilder's performance.
According to Clarkson Research, a shipbuilding and marine analysis agency, the new shipbuilding price index recorded 189.95 points as of the end of September, the highest since August 2008. In the first half of this year, new orders in Korea were 7200 CGT (tonne equivalent to the standard line), up about 34% year-on-year.
In line with this trend, Hanwha Ocean is also expected to turn into a surplus in the third quarter of this year. Despite the depreciation of the won against the dollar, the company expects to make a profit in the third quarter due to the reflection of high-priced ship volume and the effect of the provisions and outsourcing costs taken in the second quarter. Hanwha Ocean posted an operating loss of 9.7 billion won in the second quarter.
Nevertheless, the year-over-year decline in operating profit was due to one-time factors in the previous year. In the third quarter of last year, about 157 billion won in advance payments were returned due to the restoration of fair value as it won a lawsuit for arbitration of the return of advance payments for two drillships. This resulted in an operating profit of KRW 74.1 billion, the only quarterly profit last year.
However, Hanwha Ocean's performance is expected to continue to improve in the future. Since the first half of 2021, the company has seen a rise in ship price, a significant increase in new orders, and a quantitative and qualitative improvement in its backlog.
This year, Hanwha Ocean has secured orders totaling USD 6.1 billion (approx. KRW 8.3 trillion), including 17 liquefied natural gas (LNG) carriers and floating storage and regasification units (LNG-FSRUs), seven supertankers, two ammonia carriers, one gas carrier, one offshore, and three specialty vessels. This is significantly higher than the $3.52 billion (KRW 4.79 trillion) in orders received last year.
In August, the company became the first Korean shipbuilder to win the maintenance, repair and overhaul (MRO) business for the 40,000-ton (t) Wally Schirra, a U.S. Navy logistics support ship, marking its entry into the U.S. battle ship market, which is worth about KRW 20 trillion annually.
Shin Haeju (hjs0509@fntimes.com)




















